
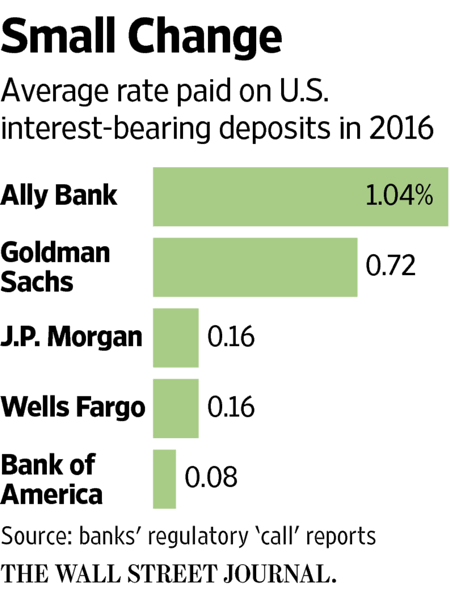
After last week’s WSJ article about interest rates, I noticed that both Goldman Sachs Bank USA (GS Bank) and Ally Bank have both been hiking rates on their CDs. Competition is good and I like that they both still show the desire to stay at the top as rates start rising again. (GS Bank is formerly GE Capital Bank, which also had a good history of maintaining high rates.) I’ll still chase a good limited-time CD rate if it’s high enough, but I like not having to move my cash around constantly.
Is Ally or Goldman Sachs a better overall place to keep your cash? Here is a direct rate comparison at various terms (as of 5/15/17). Both have hikes rates already this month.

In terms of side-by-side rate comparison, GS Bank is either the top or tied for the top at all the term lengths as of 5/15/17. Things could change with future rate changes. However, I would point out that their early withdrawal penalties are slightly different, with Ally being more lenient across the board.
Ally Bank Early Withdrawal Penalty Schedule
- Terms less than 24 months = 60 days of interest
- Terms 25 months to 36 months = 90 days of interest
- Terms 37 months to 48 months = 120 days of interest
- Terms 39 months and longer = 150 days of interest
Goldman Sachs Bank Early Withdrawal Penalty Schedule
- Terms less than 12 months = 90 days of interest
- Terms of 12 months to 5 years = 270 days of interest
- Terms of more than 5 years = 365 days of interest
Both offer fast transfers between external bank accounts as quickly as one business day. I have not opened a Goldman Sachs Bank account (yet) so I haven’t done a side-by-side comparison of transfer speeds.
Bottom line. Both Ally Bank and Goldman Sachs Bank are solid, all-around online banks and offer least highly competitive rates across all term lengths. Goldman has slightly higher rates at certain terms lengths, but Ally has smaller early withdrawal penalty. Alliant Credit Union is another worthy all-around competitor that I also considered, but Alliant’s certificate rates are lower across the board other than their 1.05% APY savings account which is tied. I hope to continue to take regular rate snapshots.

 Santander Bank has a new promotion offer a $225 cash bonus for new deposit customers that satisfy the following conditions:


 Wells Fargo has a $250 bonus offer for new checking account customers. You can open any consumer checking account except for Teen Checking. The prepaid Wells Fargo EasyPay® Card is not eligible. You must open the account from the special bonus page with a minimum opening deposit of $25 by February 17, 2017. (You can charge the opening deposit on a credit card.) Within 60 days of account opening, you must also do one of the following:

 This time of year, we are surrounded by discounts. 40% off here. 80% off there. I always wonder to myself, does it really make any difference? If you save $35 on a $50 sweater, you feel good that you got a bargain. But where does that “savings” go? Are you actually any richer? Don’t you just go out and buy more stuff? Does chasing all these sales actually help or hurt your net worth?


 Updated with online maturity information and screenshots. If you have money in a bank certificate of deposit (CD), you should be aware that most of them will renew automatically for the same term length upon maturity. That means if you don’t specifically tell them otherwise, your 5-year CD will roll over for another 5 years if you’re caught snoozing during the grace period. Different banks set different grace period lengths and renewal instructions; the best ones in my opinion let you set the decision ahead of time (i.e. Pentagon Federal Credit Union).


 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)