Fidelity, Schwab Won’t Let You Trade Money Market ETFs (That Aren’t Theirs)

In case you aren’t aware that a huge profit source for every broker is your idle cash, Bloomberg reports that Fidelity and Schwab are blocking all new purchase trades of new money market ETFs (gift article) from Blackrock and Texas Capital. Here’s what Fidelity and Schwab say about it:

A Schwab spokesperson said its decision is consistent with the firm’s “long-standing approach” of only making available Schwab affiliate money-market mutual funds, while a Fidelity spokesperson said this is an extension of the company’s policy to “generally restrict” third-party money-market mutual funds.

The inflows to those new ETFs weren’t even that big, making this an interesting development:

Yet, the move stands out because trading platforms like Schwab and Fidelity typically don’t restrict exchange-traded funds, even if those funds are in competition with existing in-house offerings.

Indeed, I hope this doesn’t start a trend of more bans of competitor ETFs. Fidelity and Blackrock have worked very closely together in the past, so this is probably rather awkward.

For now, I still own lots of shares of iShares 0-3 Month Treasury Bond ETF (SGOV) and probably soon Vanguard 0-3 Month Treasury Bill ETF (VBIL). Fidelity and Schwab haven’t banned those, yet. Of course, Vanguard continues to not play funny games with their money market sweep funds. C’mon Vanguard, time for your own money market ETF to create even more tension…

I know that these brokers have to make their money somewhere, but they may have to become more transparent about it soon.
Best Interest Rates Survey: Savings Accounts, Treasuries, CDs, ETFs – March 2025

Here’s my monthly survey of the best interest rates on cash as of March, roughly sorted from shortest to longest maturities. Banks love taking advantage of our idle cash, and you can often earning more money while keeping the same level of safety by moving to another FDIC-insured bank or NCUA-insured credit union. Check out my Ultimate Rate-Chaser Calculator to see how much extra interest you could earn from switching. Rates listed are available to everyone nationwide. Rates checked as of 3/9/2024.

TL;DR: Short-term savings accounts dropped very slightly overall, with top rates varying widely from 3.7% to 5% APY. Short-term T-Bill rates at around 4.3%. Top 5-year CD rates are ~4.30% APY, while 5-year Treasury rate is ~4.1%.

High-yield savings accounts*
Since the huge megabanks still pay essentially no interest, everyone should at least have a separate, no-fee online savings account to piggy-back onto your existing checking account. The interest rates on savings accounts can drop at any time, so I list the top rates as well as competitive rates from banks with a history of competitive rates and solid user experience. Some banks will bait you with a temporary top rate and then lower the rates in the hopes that you are too lazy to leave.

  • The top saving rate at the moment: Roger.bank is at 5.00% APY (no min), but does require an additional companion checking account. CIT Platinum Savings is now at 4.30% APY with $5,000+ balance, but also has a $225/$300 deposit bonus you can stack on top.
  • SoFi Bank is at 3.80% APY + up to $325 new account bonus with direct deposit. You must maintain a direct deposit of any amount (even $1) each month for the higher APY. SoFi has historically competitive rates and full banking features. See details at $25 + $300 SoFi Money new account and deposit bonus.
  • Here is a limited survey of high-yield savings accounts. They aren’t the top rates, but a group that have historically kept it relatively competitive such that I like to track their history.

Short-term guaranteed rates (1 year and under)
A common question is what to do with a big pile of cash that you’re waiting to deploy shortly (plan to buy a house soon, just sold your house, just sold your business, legal settlement, inheritance). My usual advice is to keep things simple and take your time. If not a savings account, then put it in a flexible short-term CD under the FDIC limits until you have a plan.

  • No Penalty CDs offer a fixed interest rate that can never go down, but you can still take out your money (once) without any fees if you want to use it elsewhere. Marcus has a 13mo No Penalty CD at 4.15% APY ($500 minimum deposit). Farmer’s Insurance FCU has 9-month No Penalty CD at 4.25% APY ($1,000 minimum deposit). Credit Human has 12-month Liquid CD at 4.26% APY ($5,000 minimum) that allows unlimited deposits and two allowed withdrawals. Consider opening multiple CDs in smaller increments for more flexibility.
  • Security State Bank has a 12-month certificate special at 4.65% APY ($25,000 min). Early withdrawal penalty is 180 days of interest.

Money market mutual funds
Many brokerage firms that pay out very little interest on their default cash sweep funds (and keep the difference for themselves). Note: Money market mutual funds are highly-regulated, but ultimately not FDIC-insured, so I would still stick with highly reputable firms.

  • Vanguard Federal Money Market Fund (VMFXX) is the default sweep option for Vanguard brokerage accounts, which has an SEC yield of 4.24% (changes daily, but also works out to a compound yield of 4.32%, which is better for comparing against APY). Odds are this is much higher than your own broker’s default cash sweep interest rate.
  • Vanguard Treasury Money Market Fund (VUSXX) is an alternative money market fund which you must manually purchase, but the interest will be mostly (100% for 2024 tax year) exempt from state and local income taxes because it comes from qualifying US government obligations. Current SEC yield of 4.25% (compound yield of 4.33%).

Treasury Bills and Ultra-short Treasury ETFs
Another option is to buy individual Treasury bills which come in a variety of maturities from 4-weeks to 52-weeks and are fully backed by the US government. You can also invest in ETFs that hold a rotating basket of short-term Treasury Bills for you, while charging a small management fee for doing so. T-bill interest is exempt from state and local income taxes, which can make a significant difference in your effective yield.

  • You can build your own T-Bill ladder at TreasuryDirect.gov or via a brokerage account with a bond desk like Vanguard and Fidelity. Here are the current Treasury Bill rates. As of 3/7/25, a new 4-week T-Bill had the equivalent of 4.31% annualized interest and a 52-week T-Bill had the equivalent of 4.06% annualized interest.
  • The iShares 0-3 Month Treasury Bond ETF (SGOV) has a 4.20% SEC yield (0.09% expense ratio) and effective duration of 0.09 years. SPDR Bloomberg Barclays 1-3 Month T-Bill ETF (BIL) has a 4.13% SEC yield (0.136% expense ratio) and effective duration of 0.15 years. The Vanguard 0-3 Month Treasury Bill ETF (VBIL) hasn’t been around long enough to generate an SEC yield (0.07% expense ratio).

US Savings Bonds
Series I Savings Bonds offer rates that are linked to inflation and backed by the US government. You must hold them for at least a year. If you redeem them within 5 years there is a penalty of the last 3 months of interest. The annual purchase limit for electronic I bonds is $10,000 per Social Security Number, available online at TreasuryDirect.gov.

  • “I Bonds” bought between November 2024 and April 2025 will earn a 3.11% rate for the first six months. The rate of the subsequent 6-month period will be based on inflation again. More on Savings Bonds here.
  • In mid-April 2025, the CPI will be announced and you will have a short period where you will have a very close estimate of the rate for the next 12 months. I will have another post up at that time.

Rewards checking accounts
These unique checking accounts pay above-average interest rates, but with unique risks. You have to jump through certain hoops which usually involve 10+ debit card purchases each cycle, a certain number of ACH/direct deposits, and/or a certain number of logins per month. If you make a mistake (or they judge that you did) you risk earning zero interest for that month. Some folks don’t mind the extra work and attention required, while others would rather not bother. Rates can also drop suddenly, leaving a “bait-and-switch” feeling.

  • OnPath Federal Credit Union (my review) pays 7.00% APY on up to $10,000 if you make 15 debit card purchases, opt into online statements, and login to online or mobile banking once per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization. You can also get a $100 Visa Reward card when you open a new account and make qualifying transactions.
  • Genisys Credit Union pays 6.75% APY on up to $7,500 if you make 10 debit card purchases of $5+ each per statement cycle, and opt into online statements. Anyone can join this credit union via $5 membership fee to join partner organization.
  • La Capitol Federal Credit Union pays 5.75% APY (down from 6.25%) on up to $10,000 if you make 15 debit card purchases of at least $5 each per statement cycle. Anyone can join this credit union via partner organization, Louisiana Association for Personal Financial Achievement ($20).
  • (new) First Southern Bank pays 5.50% APY on up to $25,000 if you make at least 15 debit card purchases, 1 ACH credit or payment transaction, and enroll in online statements.
  • Credit Union of New Jersey pays 6.00% APY on up to $25,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit, online bill payment, or automatic payment (ACH) per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Andrews Federal Credit Union pays 6.00% APY on up to $25,000 if you make 15 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization.
  • Find a locally-restricted rewards checking account at DepositAccounts.

Certificates of deposit (greater than 1 year)
CDs offer higher rates, but come with an early withdrawal penalty. By finding a bank CD with a reasonable early withdrawal penalty, you can enjoy higher rates but maintain access in a true emergency. Alternatively, consider building a CD ladder of different maturity lengths (ex. 1/2/3/4/5-years) such that you have access to part of the ladder each year, but your blended interest rate is higher than a savings account. When one CD matures, use that money to buy another 5-year CD to keep the ladder going. Some CDs also offer “add-ons” where you can deposit more funds if rates drop.

  • KS State Bank has a 5-year certificate at 4.30% APY ($500 minimum), 4-year at 4.30% APY, 3-year at 4.30% APY, 2-year at 4.25% APY, and 1-year at 4.30% APY. $500 minimum. The early withdrawal penalty (EWP) for the 5-year is a huge 540 days of interest.
  • Mountain America Credit Union (MACU) has a 5-year certificate at 4.25% APY ($500 minimum), 4-year at 4.25% APY, 3-year at 4.25% APY, 2-year at 3.95% APY, and 1-year at 4.25% APY. Early withdrawal penalty for the 4-year and 5-year is 365 days of interest. Anyone can join this credit union via partner organization American Consumer Council for a one-time $5 fee (or try promo code “consumer”).
  • Lafayette Federal Credit Union (LFCU) has a 5/4/3/2/1-year certificates at 4.28% APY ($500 min). Slightly higher rates with jumbo $100,000+ balances. Note that the early withdrawal penalty for the 5-year is a relatively large 600 days of interest. Anyone nationwide can join LFCU by joining the Home Ownership Financial Literacy Council (HOFLC) for a one-time $10 fee.
  • You can buy certificates of deposit via the bond desks of Vanguard and Fidelity. You may need an account to see the rates. These “brokered CDs” offer FDIC insurance and easy laddering, but they don’t come with predictable early withdrawal penalties. Right now, I see a 5-year non-callable CD at 4.10% APY (callable: no, call protection: yes). Be warned that both Vanguard and Fidelity will list higher rates from callable CDs, which importantly means they can call back your CD if rates drop later. (Issuers have indeed started calling some of their old 5%+ CDs during 2024.)

Longer-term Instruments
I’d use these with caution due to increased interest rate risk (tbh, I don’t use them at all), but I still track them to see the rest of the current yield curve.

  • Willing to lock up your money for 10 years? You can buy long-term certificates of deposit via the bond desks of Vanguard and Fidelity. These “brokered CDs” offer FDIC insurance, but they don’t come with predictable early withdrawal penalties. You might find something that pays more than your other brokerage cash and Treasury options. Right now, I see a 10-year CDs at [n/a] (non-callable) vs. 4.32% for a 10-year Treasury. Watch out for higher rates from callable CDs where they can call your CD back if interest rates drop.

All rates were checked as of 3/9/25.

* I no longer recommend fintech companies due to the possibility of loss due to poor recordkeeping and lack of government regulation. (Ex. Evergreen Wealth at 5% APY is a fintech.)

Photo by insung yoon on Unsplash

Raisin Marketplace: Up to $400 Deposit Bonus (and Why I’m Skipping It)

Raisin is a financial marketplace that allows you to access high-interest certificates of deposit and savings accounts from multiple different banks and credit unions without having to open up a new account at each one. Right now, they have some new deposit bonuses that are pretty solid based on the bonus-to-deposit ratios and minimum holding periods. However, I will personally not be taking advantage of them due to their use of custodial FBO accounts. I think it’s most useful to both point out the existence of these bonuses and explain my take on them. Details below.

Here are the new bonuses:

  • New customer $250 bonus. Open a new account with promo code GET250, deposit $25,000 within 14 days, and maintain for 90 days for the $250 bonus.
  • Existing customer deposit bonus, up to $400. Must deposit $50,000 in new money. $200 on a 3–6 month CD. $300 on a 7–11 month CD. $400 for a 12+ month CD. Must maintain for full CD maturity period.

How Raisin works. The benefit of Raisin is that you can easily access aggressively high rates at a new bank or credit union without having to open yet another new account (and endure credit checks, identify verification hurdles, join partner organizations, leave funds in share savings accounts, etc). The price is added complexity, higher risk for miscommunication and errors, and a place in a regulatory shadow zone.

Instead of opening a direct account at a new partner bank, there are at least three different parties.

  • Raisin, which is the overall business (“financial technology company”) and not a bank and not a credit union. (Source #1)
  • There are the middlemen, Custodial Bank(s) and Service Bank. The Custodial Bank opens up FBO (For Benefit Of) accounts at each of the Partner Banks/Credit Unions in THEIR names. These FBO accounts are basically big pooled accounts, and the Custodial Bank is supposed to keep track of all the money going in and out for all the individual Raisin customers in their own virtual ledger. The Service Bank is in charge of moving your funds amongst the various banks. Central Bank of Kansas City (CBKC), Member FDIC, is the Service Bank. CBKC, Lewis & Clark Bank and Starion Bank, each Member FDIC, are the Custodial Banks. (Source #2)
  • There are the partner banks. These banks and credit unions are looking to grow deposits, but they have no idea who you are as an individual. They come and go on the Raisin platform. They only see that they opened a single, huge FBO account for the Custodial Bank. (Source #3)

While this setup appears to be perfectly legal (as far I can tell, I am not a lawyer), that doesn’t mean that there is someone to clean up the mess if something goes wrong. It’s like if someone steals your wallet and the cops are too busy with violent crime to track them down, it doesn’t matter if it’s illegal, you’re still not getting your money back.

The real-world example is what happened with Juno, Yotta, Synapse, and Evolve Bank & Trust. They had major disagreements about the ledger tracking all the deposits and withdrawals. They all blamed each other for the missing funds (~$50 million). Since no bank actually failed, the FDIC did not step in. No other regulatory agency stepped in. I was surprised. It was all left to a severely-underfunded bankruptcy court, and the mess still isn’t figured out. Someone ran off with tens of millions of dollars, and innocent individuals were left holding the bag.

Source #1:

Raisin is not a bank and your money is always handled by a federally regulated financial institution — whether in transit, stored in the Cash Account, or in an account at a partner bank. The Custodial Bank keeps records of all funds deposited through the Raisin platform for added security.

Source #2

Custodial accounts are accounts held on for the benefit of Raisin customers by a custodial bank at the banks and credit unions where customers deposit their money through Raisin. When a customer makes a deposit through the Raisin platform into a savings product offered by a given financial institution, the funds move from the customer’s external bank account (also referred to as their reference account) to a custodial account held by one of Raisin’s partner custodial banks at the financial institution offering the savings product. Central Bank of Kansas City (CBKC), Lewis & Clark Bank and Starion Bank, each Member FDIC, are the Custodial Banks.

Source #3:

An FDIC-supervised custodial bank opens the “For Benefit Of” account for each customer and agrees directly with Raisin’s customers to act as the custodian of their funds. This custodial bank is authorized by Raisin customers, as their agent, to hold their deposits at federally regulated banks and credit unions on their behalf in a custodial capacity. Customer funds are never co-mingled with Raisin funds.

Again, if everyone does what they say they will, then it’s all good. The problem is what happens when they don’t. If it happens with Raisin (or any of the parties involved, all relatively small institutions), it has the potential to be a complete mess that could take years to untangle. In today’s regulatory environment, I have zero interest in putting my cash into any sort of regulatory grey area.

In contrast, the CIT Bank $225/$300 deposit offer involves a simple, direct relationship with CIT Bank, an FDIC-insured bank, where you have an individual/joint account directly held in your name. There is a single system. There is no potential pointing of figures between multiple parties. There is a long, established history of the FDIC stepping in resolve a bank failure within days. It’s about as safe as it gets.

Bottom line. I’m doing the CIT bank offer, but not the Raisin offer.

SGOV, STIP, TIP iShares ETFs: Claim Your State Income Tax Exemption (2024/2025)

As a follow-up to my posts for Vanguard and Fidelity money market funds, iShares ETFs (Blackrock) has also recently released their US GOI percentages for 2024 tax year. US Government Obligation Interest (US GOI) like Treasury bills and bonds are generally exempt from state and local income taxes. However, in order to claim this exemption, you’ll likely have to manually enter it on your tax return after digging up a few extra details.

The tax document has a pretty good summary of the situation for all brokers:

The Form 1099-DIV (or substitute form) you received from your financial advisor or brokerage firm may include income derived from U.S. Government and agency obligations. This income may be excluded from state income tax (although in many states, only the income from Treasury obligations is exempt from personal state income tax). The information below is provided to assist with the completion of shareholder state income tax returns. The amount in Box 1a of 2024 IRS Form 1099-DIV should be multiplied by the applicable percentages below to obtain the dollar amount of income derived from the sources categorized below. Because the qualifications for exclusion vary by state (some states have investment threshold requirements), please consult your tax advisor for details.

It’s notable that even things like the iShares iBonds 20XX Term TIPS ETFs are not 100% US government obligations, so it’s important to reference this document and not assume. For iShares TIPS Bond ETF (TIP) and iShares 0-5 Year TIPS Bond ETF (STIP) the USGOI percentage for 2024 was indeed at 100.00%.

For iShares 0-3 Month Treasury Bond ETF (SGOV), the USGOI percentage for 2024 was 97.53%. This is pretty good and why SGOV is my default cash position at most brokers. The tax document also confirms that at least 50% of the assets of the fund were invested in Federal Obligations at the end of each quarter of the fiscal year. That means that SGOV met the minimum criteria for the dividend income to be exempt in the states of California, Connecticut, and New York.

Personal Finance Stack: Portfolio Simplification Progress for 2024

I recently found a handwritten note from early 2024 that outlined my goals to “SIMPLIFY!” my portfolio. The overall idea was to make things easier for my spouse to manage in case something happened to me. Even though I still have a rat’s nest of accounts overall, I wanted a streamlined “Core” group of accounts that held 99% of my portfolio. Here’s the current state of the investment side of my personal finance stack.

Vanguard. Vanguard still holds the majority of my investment portfolio, while at the same time has the least amount of transaction activity. The idea is to let it just grow, but also to avoid the need to deal with customer service. Vanguard has the best cash sweep if you don’t use automatic dividend reinvestment. I also want to give the new CEO a bit of time to see how things go.

In 2024, I did convert all my mutual funds into ETFs, so they are easily portable if I do want to move assets. In addition, perhaps the slightly lower ETF expense ratios will make a difference.

Fidelity. Fidelity holds the 2nd-largest total balance, and is where I keep my high-touch accounts. My Fidelity Cash Management Account (CMA) handles most of my monthly cashflows (direct deposit in; BillPay out). My Solo 401k with the manual contributions and ability to buy individual TIPS/Treasuries. My self-directed account with individual stock holdings. In the future, I plan on opening any custodial accounts for kids there.

TreasuryDirect (Sold all Savings Bonds!). A major reason to sell was to achieve simplification and no longer be reliant on the customer service of TreasuryDirect, mostly in for estate planning scenarios. In addition, their policy states that if my account is hacked, they maintain zero liability for any losses. I will miss the additional effective tax-deferred space of savings bonds, but it just wasn’t worth the additional hassle. I just don’t see things improving there in the future, it feels more like gradual decay. This was my 3rd largest balance.

Many of these savings bonds had fixed rates in the 0% to 1%; only a few were at higher fixed rates. The proceeds were reinvested into long-term TIPS (bought/held at Fidelity) with real yields of 2% to 2.6%. Finally, it worked out because the capital gains from this sale were offset from capital losses harvested from selling a bond fund previously when rates rose. (I did an ETF swap to harvest the tax losses while maintaining a similar bond holding without incurring a wash sale.)

Robinhood (setback!). In an unexpected setback for simplification, I ended up transferring my Vanguard IRAs to Robinhood in 2024 due to their 3% transfer promo. When the 5-year hold ends, my plan is to move them to Fidelity unless there is another lucrative offer. This was a new brokerage account to track, but I just couldn’t turn down an additional ~$18,000 in Roth IRA balances.

Utah My529. Thanks to some big early contributions and a very aggressive asset allocation, this is now my next largest investment account, although theoretically it should be completely obliterated within 12 years or so when the tuition bills hit. I consolidated 529 plans several years ago; it can be a lot of paperwork but it’s nice to have everything at one place. Utah seems to be on top of the game for 529 plans.

Bank of America/Merrill Edge to US Bank swap? I keep $100,000 in brokerage assets at Merrill Edge in order to qualify for the Bank of America Preferred Rewards Tier which essentially gets me a flat 2.625% cash back on all my purchases. However, in 2024, US Bank debuted their Smartly credit card that offers up to 4% cash back, also if you keep $100,000 in asset at their brokerage arm.

Should I set up yet another new account at US Bank to take advantage? Should I then close down BofA/Merrill Edge to offset? The problem is that I’m not convinced that US Bank will keep the 4% cash back for very long. US Bank has a history of rolling out new products and then shutting them down abruptly. On the other hand, they also have a history of sometimes keeping the existing perks for grandfathered customers. So maybe it’s best to get in early? Simplification vs. optimization. I didn’t take any action in 2024.

Honestly, as the now-5th largest balance, the BofA/Merrill Edge is the account that I should probably get rid of next, but it’s been so reliable with minimal hassles. I don’t like to mess with what works.

401k Custodians (consolidated with direct 401k-to-401k transfers). These are pre-tax accounts, so I didn’t want to go 401k-to-IRA since then I would have Pre-tax IRAs which would complicate my Backdoor Roth IRA conversions. This makes one less place I have to track my investments. Eventually, if/when our marginal tax brackets are lower, I’d plan to convert some of these accounts to Roth IRAs.

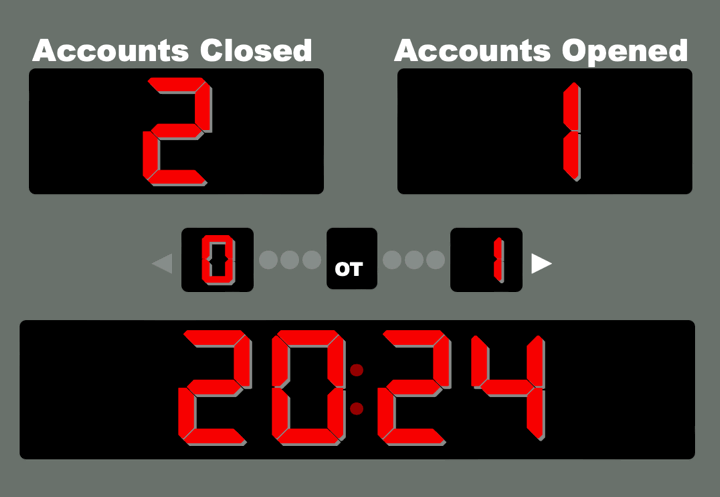
Final score: Two accounts closed (TreasuryDirect and 401k), one account opened (Robinhood).

Vanguard T-Bill/Ultra-Short Treasury ETF, iShares Money Market ETFs Now Live

Vanguard’s new index ETFs that hold short-term US Treasury Bonds are now live (press release).

  • Vanguard 0-3 Month Treasury Bill ETF (VBIL). Tracks the Bloomberg US Treasury Bills 0-3 Months Index, which holds T-Bills with maturities of 3 months or less. Expense ratio of 0.07%.
  • Vanguard Ultra-Short Treasury ETF (VGUS). Tracks the Bloomberg Short Treasury Index, which includes U.S. Treasury Bills, Notes, and Bonds with less than 12 months until maturity. Expense ratio of 0.07%.

Both are the lowest-cost ETF in their respective categories. As a result, I expect they will grow to be popular as now you can access low-cost cash from Vanguard without opening a brokerage account at Vanguard.

For now though, they’ve only been around for several days, so the volume is still relatively low and the bid/ask spreads are relatively high. For now, I am keeping my current favorite cash ETF holding: iShares 0-3 Month Treasury Bond ETF (SGOV) with an expense ratio of 0.09%, close enough for now.

This ETF.com article points out that this is a growing sector for ETFs, with iShares also launching two of the earliest money market ETFs this month:

  • iShares Prime Money Market ETF (PMMF). Actively managed money market ETF. Expense ratio of 0.20%.
  • iShares Government Money Market ETF (GMMF). Actively managed money market ETF. Expense ratio of 0.20%.

These ETFs do not hold only US Treasuries, but instead hold a basket of cash-equivalents that satisfy the strict SEC money market rules under Rule 2a-7 that help to ensure both safety of principal and liquidity in times of market stress. However, this covers a variety of “safe” stuff besides Treasuries so the interest paid out may not be exempt of state and local income taxes. The “Government” money market is more likely to have a higher percentage that qualifies, but when I looked at their holdings there are a lot of various swaps and/or derivatives that probably don’t count as US government obligation interest.

Anyway, interesting that you can buy money market funds as ETFs now. If they are successful, I don’t see why Vanguard wouldn’t enter this sector as well. I’m confident they could beat those expense ratios.

Best Interest Rates Survey: Savings Accounts, Treasuries, CDs, ETFs – February 2025

Here’s my monthly survey of the best interest rates on cash as of February, roughly sorted from shortest to longest maturities. Banks love taking advantage of our idle cash, and you can often earning more money while keeping the same level of safety by moving to another FDIC-insured bank or NCUA-insured credit union. Check out my Ultimate Rate-Chaser Calculator to see how much extra interest you could earn from switching. Rates listed are available to everyone nationwide. Rates checked as of 2/9/2024.

TL;DR: Liquid, short-term rates slightly lower overall. Longer-term rates actually went up a little; there are 4%+ APY 5-year CDs. Compare against Treasury bills and bonds at every maturity, taking into account state tax exemption. I no longer recommend fintech companies due to the possibility of loss due to poor recordkeeping and lack of government regulation. (Ex. Evergreen Wealth at 5% APY is a fintech.)

High-yield savings accounts
Since the huge megabanks still pay essentially no interest, everyone should at least have a separate, no-fee online savings account to piggy-back onto your existing checking account. The interest rates on savings accounts can drop at any time, so I list the top rates as well as competitive rates from banks with a history of competitive rates and solid user experience. Some banks will bait you with a temporary top rate and then lower the rates in the hopes that you are too lazy to leave.

  • The top saving rates at the moment top out at about what Quontic Bank offers at 4.75% APY (No min). Roger.bank is at 5.00% APY (no min), but does require an additional checking account. I have no direct experience with either, but those are top rates. CIT Platinum Savings is now at 4.30% APY with $5,000+ balance.
  • SoFi Bank is at 3.80% APY + up to $325 new account bonus with direct deposit. You must maintain a direct deposit of any amount (even $1) each month for the higher APY. SoFi has historically competitive rates and full banking features. See details at $25 + $300 SoFi Money new account and deposit bonus.
  • Here is a limited survey of high-yield savings accounts. They aren’t the top rates, but a group that have historically kept it relatively competitive such that I like to track their history.

Short-term guaranteed rates (1 year and under)
A common question is what to do with a big pile of cash that you’re waiting to deploy shortly (plan to buy a house soon, just sold your house, just sold your business, legal settlement, inheritance). My usual advice is to keep things simple and take your time. If not a savings account, then put it in a flexible short-term CD under the FDIC limits until you have a plan.

  • No Penalty CDs offer a fixed interest rate that can never go down, but you can still take out your money (once) without any fees if you want to use it elsewhere. Marcus has a 7mo/13mo No Penalty CD at 4.15% APY with a $500 minimum deposit. Farmer’s Insurance FCU has 9-month No Penalty CD at 4.25% APY with a $1,000 minimum deposit. Consider opening multiple CDs in smaller increments for more flexibility.
  • Abound Credit Union has a 8-month certificate special at 4.75% APY ($500 min). Anyone can join this credit union nationwide with $10 fee. Early withdrawal penalty is 90 days of interest.

Money market mutual funds
Many brokerage firms that pay out very little interest on their default cash sweep funds (and keep the difference for themselves). Note: Money market mutual funds are highly-regulated, but ultimately not FDIC-insured, so I would still stick with highly reputable firms.

  • Vanguard Federal Money Market Fund (VMFXX) is the default sweep option for Vanguard brokerage accounts, which has an SEC yield of 4.27% (changes daily, but also works out to a compound yield of 4.35%, which is better for comparing against APY). Odds are this is much higher than your own broker’s default cash sweep interest rate.
  • Vanguard Treasury Money Market Fund (VUSXX) is an alternative money market fund which you must manually purchase, but the interest will be mostly (100% for 2024 tax year) exempt from state and local income taxes because it comes from qualifying US government obligations. Current SEC yield of 4.26% (compound yield of 4.35%).

Treasury Bills and Ultra-short Treasury ETFs
Another option is to buy individual Treasury bills which come in a variety of maturities from 4-weeks to 52-weeks and are fully backed by the US government. You can also invest in ETFs that hold a rotating basket of short-term Treasury Bills for you, while charging a small management fee for doing so. T-bill interest is exempt from state and local income taxes, which can make a significant difference in your effective yield.

  • You can build your own T-Bill ladder at TreasuryDirect.gov or via a brokerage account with a bond desk like Vanguard and Fidelity. Here are the current Treasury Bill rates. As of 2/7/25, a new 4-week T-Bill had the equivalent of 4.32% annualized interest and a 52-week T-Bill had the equivalent of 4.24% annualized interest.
  • The iShares 0-3 Month Treasury Bond ETF (SGOV) has a 4.27% SEC yield (0.09% expense ratio) and effective duration of 0.09 years. SPDR Bloomberg Barclays 1-3 Month T-Bill ETF (BIL) has a 4.18% SEC yield (0.136% expense ratio) and effective duration of 0.15 years.

US Savings Bonds
Series I Savings Bonds offer rates that are linked to inflation and backed by the US government. You must hold them for at least a year. If you redeem them within 5 years there is a penalty of the last 3 months of interest. The annual purchase limit for electronic I bonds is $10,000 per Social Security Number, available online at TreasuryDirect.gov.

  • “I Bonds” bought between November 2024 and April 2025 will earn a 3.11% rate for the first six months. The rate of the subsequent 6-month period will be based on inflation again. More on Savings Bonds here.
  • In mid-April 2025, the CPI will be announced and you will have a short period where you will have a very close estimate of the rate for the next 12 months. I will have another post up at that time.

Rewards checking accounts
These unique checking accounts pay above-average interest rates, but with unique risks. You have to jump through certain hoops which usually involve 10+ debit card purchases each cycle, a certain number of ACH/direct deposits, and/or a certain number of logins per month. If you make a mistake (or they judge that you did) you risk earning zero interest for that month. Some folks don’t mind the extra work and attention required, while others would rather not bother. Rates can also drop suddenly, leaving a “bait-and-switch” feeling.

  • OnPath Federal Credit Union (my review) pays 7.00% APY on up to $10,000 if you make 15 debit card purchases, opt into online statements, and login to online or mobile banking once per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization. You can also get a $100 Visa Reward card when you open a new account and make qualifying transactions.
  • Genisys Credit Union pays 6.75% APY on up to $7,500 if you make 10 debit card purchases of $5+ each per statement cycle, and opt into online statements. Anyone can join this credit union via $5 membership fee to join partner organization.
  • La Capitol Federal Credit Union pays 6.25% APY on up to $10,000 if you make 15 debit card purchases of at least $5 each per statement cycle. Anyone can join this credit union via partner organization, Louisiana Association for Personal Financial Achievement ($20).
  • Falcon National Bank pays 6.00% APY on up to $25,000 if you make at least 15 debit card purchases, 1 direct deposit OR ACH credit transaction, and enroll in online statements.
  • Credit Union of New Jersey pays 6.00% APY on up to $25,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit, online bill payment, or automatic payment (ACH) per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Andrews Federal Credit Union pays 6.00% APY on up to $25,000 if you make 15 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization.
  • Find a locally-restricted rewards checking account at DepositAccounts.

Certificates of deposit (greater than 1 year)
CDs offer higher rates, but come with an early withdrawal penalty. By finding a bank CD with a reasonable early withdrawal penalty, you can enjoy higher rates but maintain access in a true emergency. Alternatively, consider building a CD ladder of different maturity lengths (ex. 1/2/3/4/5-years) such that you have access to part of the ladder each year, but your blended interest rate is higher than a savings account. When one CD matures, use that money to buy another 5-year CD to keep the ladder going. Some CDs also offer “add-ons” where you can deposit more funds if rates drop.

  • KS State Bank has a 5-year certificate at 4.30% APY ($500 minimum), 4-year at 4.30% APY, 3-year at 4.30% APY, 2-year at 4.25% APY, and 1-year at 4.30% APY. $500 minimum. The early withdrawal penalty (EWP) for the 5-year is a huge 540 days of interest.
  • Mountain America Credit Union (MACU) has a 5-year certificate at 4.35% APY ($500 minimum), 4-year at 4.30% APY, 3-year at 4.25% APY, 2-year at 4.05% APY, and 1-year at 4.35% APY. Early withdrawal penalty for the 4-year and 5-year is 365 days of interest. Anyone can join this credit union via partner organization American Consumer Council for a one-time $5 fee (or try promo code “consumer”).
  • You can buy certificates of deposit via the bond desks of Vanguard and Fidelity. You may need an account to see the rates. These “brokered CDs” offer FDIC insurance and easy laddering, but they don’t come with predictable early withdrawal penalties. Right now, I see a 5-year non-callable CD at 4.25% APY (callable: no, call protection: yes). Be warned that both Vanguard and Fidelity will list higher rates from callable CDs, which importantly means they can call back your CD if rates drop later. (Issuers have indeed started calling some of their old 5%+ CDs during 2024.)

Longer-term Instruments
I’d use these with caution due to increased interest rate risk (tbh, I don’t use them at all), but I still track them to see the rest of the current yield curve.

  • Willing to lock up your money for 10 years? You can buy long-term certificates of deposit via the bond desks of Vanguard and Fidelity. These “brokered CDs” offer FDIC insurance, but they don’t come with predictable early withdrawal penalties. You might find something that pays more than your other brokerage cash and Treasury options. Right now, I see a 10-year CDs at [n/a] (non-callable) vs. 4.48% for a 10-year Treasury. Watch out for higher rates from callable CDs where they can call your CD back if interest rates drop.

All rates were checked as of 2/9/25.

Photo by Giorgio Trovato on Unsplash

US Bank Smartly Checking Account New User Bonus (Up to $450)

Updated. US Bank has a up to $450 new checking promotion when you open a Bank Smartly Checking account with $25 minimum and complete the following within 90 days:

  • Enroll in the U.S. Bank Mobile App or online banking.
  • Complete two or more direct deposits.

Your bonus is determined by the total amount of your direct deposits in those 90 days:

  • Earn $250 when your direct deposits total $2,000 to $4,999.99.
  • Earn $350 when your direct deposits total $5,000 to $7,999.99.
  • Earn $450 when your direct deposits total $8,000 or more.

The Smartly Checking account has a $6.95 monthly fee which that is waived with any one of the following:

  • Your combined monthly direct deposits total $1,000 or more.
  • You keep a minimum average account balance of $1,500 or more.
  • You are age 24 and under.
  • You are age 65 and over.
  • You are a member of the military.
  • You hold an eligible US Bank credit card
  • Qualify for one of the four Smart Rewards® tiers (Primary, Plus, Premium or Pinnacle).
  • Are a member of another of their “special customer groups”.

You may still be considered a “new” account even if you had a US Bank account years ago:

U.S. Bank Smartly® Checking bonus: To be eligible, you or any owner(s) on your new Bank Smartly Checking account cannot have an existing U.S. Bank consumer checking account, had a U.S. Bank consumer checking account in the last 12 months or received other U.S. Bank consumer checking bonus offers within the past 12 months.

Note: US Bank often restricts their financial products to those states where US Bank has a physical branch presence. They will filter you out by zip code.

Tip: However, people outside this footprint may be allowed to open an account if they have other US Bank products. I was more recently able to get this bonus even though I was outside their physical branch footprint by opening a Smartly Savings account first. I think they may have opened just the Smartly Savings nationwide recently (or was it just me?). If that isn’t working for you, you may also try to open a small certificate of deposit (CD) or even a brokerage account or go directly for a credit card. It’s strange, but once they let you open one account, they’ll let you open the rest quite easily.

This offer comes around regularly, but is still a pretty solid bonus if you haven’t done it before. You may also find it worth the effort now due to the new US Bank Smartly credit card that can earn up to 4% cash back with enough assets at US Bank.

Laurel Road High Yield Savings Deposit Bonus: 4.15% APY + Up to $200 (Referral Offer)

Updated and back for 2025. Laurel Road is a digital subsidiary of KeyBank (not a fintech) that reminds me of SoFi in that they are building a relationship that starts with student loan refinances and then expands to personal loans, mortgages, bank accounts, and credit cards.

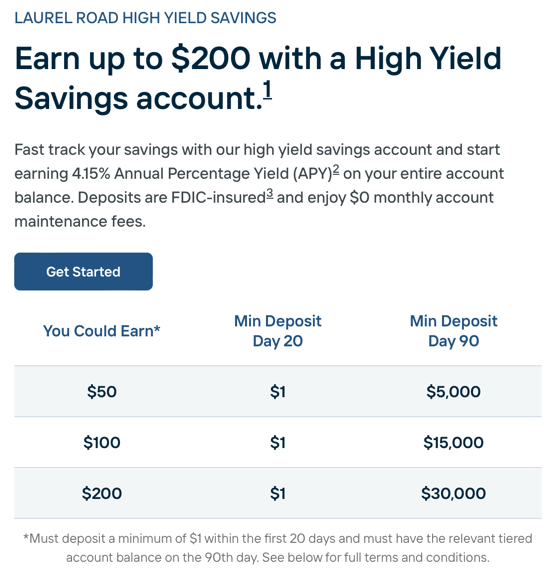
Laurel Road is again offering up to a $200 deposit bonus (my referral link) for their High Yield Savings Account by referral only. This bonus is on top of the standard interest rate, which is currently a relatively competitive 4.15% APY. Here are the steps:

  • Open a High Yield Savings account before June 30, 2025 using a referral link that shows this offer. Offer not available on their regular website.
  • Deposit at least $1 in the first 20 calendar days of account open.
  • Have at least $5,000 (or whatever tier you pick) in your account by calendar day 90 after open. $50 bonus for deposit total between $5,000–$14,999.99. $100 bonus for deposit total between $15,000–$29,999.99. $200 bonus for deposit total of $30,000+.
  • Once the requirements are met, the bonus amount will mailed to you as a check within 45 days of meeting the requirements. Your account must be open to receive the bonus, no other form of payment will be provided.

Note that it says that the “Referred individuals cannot be the owner or co-owner of a Laurel Road account in the last twelve (12) months.”.

Importantly, my reading of the terms is that there is no minimum hold period. The actual fine print:

Starting at 12:00AM EST on January 16, 2025, through 11:59PM EST on June 30, 2025 (“Campaign Period”), a $50 bonus (the “Bonus”) will be awarded to existing Laurel Road members (“Referrer”) for each friend who opens a new Laurel Road High Yield Savings (HYS) account (the “Referred”) and meets the following requirements, the Referred must: 1) submit the HYS account application through the Referrer’s link during the Campaign Period, 2) have a minimum HYS account balance of at least $1 by 7PM EST within the first twenty (20) calendar days of account opening, and 3) have a minimum balance of $5,000 by 11:59PM EST on the ninetieth (90th) calendar day of HYS account opening for Referrer to earn the Bonus. This offer cannot be combined with any other programs.

In other words, technically you just have to put $1 there by Day 20, and the rest can land on the 85th day or so to be safe.

Napkin math. Given that there is no minimum hold period, the annualized yield is theoretically sky-high. Note that the $50 bonus is at best a 1% bonus on $5,000 deposited, while the $100 and $200 bonuses are at best a 0.67% bonus on either $15,000 or $30,000, respectively. This is pretty solid since the standard APY is already competitive. Even if you held the money in there for 30 days, the $100/$200 bonuses would work out to an extra 8% annualized. Added to the 4.15% APY standard yield, that would be a total of 12.15% annualized interest.

Truist Bank $400 New Checking Account Bonus 2025 (Limited States)

Updated for 2025. Truist Bank formed from the merger of BB&T and Suntrust Banks, now roughly the 10th largest US bank with branches in 17 states and DC. Trust has brought back a $400 checking bonus for new checking customers that have a mailing address within a state in their branch footprint: AL, AR, FL, GA, IN, KY, MD, MS, NC, NJ, OH, PA, SC, TN, TX, VA, WV or DC. I usually don’t list bonuses that aren’t nationwide, but this is a sizable bonus with a large regional bank. If I lived in this area, I’d certainly rather open an account when they are giving out 400 bucks. Here are the steps:

  • Open a new Truist One Checking account online from October 31, 2024 through April 30, 2025. Minimum opening deposit is $50. Must open online with promo code DC2425TR1400 (or AFL2425TR1400 from alternate link)
  • Receive at least 2 qualifying Direct Deposits* totaling $1,000 or more within 120 days of account opening.
  • The reward will be deposited to the new checking account within 4 weeks after the qualification requirements have been met and verified. Truist verification will occur one time after the qualification requirements are initially met. The new checking account must be open and in good standing with a balance of at least $0.01 at the time of Truist verification and until the reward is deposited to receive the reward.

Compared to an earlier offer, they have increased the direct deposit requirement, but removed the 15 debit card purchases requirement.

Note the following definitions for new customers:

Clients that are the primary account holder on an existing personal checking account with Truist or who have closed a personal checking account with Truist on or after 10/31/23 are not eligible to participate.

The Truist One Checking account has a $12 monthly maintenance fees that is waived each statement cycle by any one of the following:

  • $500+ in total qualifying Direct Deposits
  • Maintain a total combined ledger balance of $500 or more in Truist related accounts across personal deposits (excluding Truist HSA) and all investments as reflected on the business day before your statement cycle end date.
  • Having a personal Truist credit card, mortgage or consumer loan, excluding LightStream®.
  • Having a linked Small Business Checking Account.
  • Students under the age of 25.
  • Primary account owner age 62 and older.

Huntington Bank $600 New Checking Account Bonus (No Direct Deposit Required, Limited States)

Huntington Bank is offer a $600 bonus when you open a new Platinum Perks Checking account and make total new money deposits of $25,000 or more within 90 days of account opening and keep account open for 90 days. No monthly maintenance fee with $25,000 in total relationship balances, otherwise $25 a month. Expiration shown is 2/7/25.

Note that this offer is limited geographically to residents to certain states:

To be eligible for this offer, click Apply Online or Open at a Branch from this page, so that the promotion code is claimed at time of account opening. This offer is only available to applicants residing in Colorado, Illinois, Indiana, Kentucky, Michigan, Minnesota, Ohio, Pennsylvania, West Virginia or Wisconsin.

I usually try to stick to offers that are available nationwide, but this was a big bonus that is pretty straightforward with no direct deposit requirement. Earning $600 on a $25,000 deposit for 90 days works out to a 9.6% annualized yield.

My Cash Setup: Checking and Liquid Savings (2025/2024 Year-End)

Although I continue to monitor the best interest rates out there, in 2024 I made the conscious decision to tone down my rate-chasing and look for a lower maintenance setup that still gets a solid interest rate on my cash. Warning: This is going to be an informal, rambling post with a lot of personal opinions. Let me know what you think in the comments. I’ll list them by most activity to least activity.

Fidelity Cash Management Account (Direct Deposit and Internal Push)
I consider the Fidelity Cash Management Account my primary cashflow account. The vast majority of my household cash flows are direct deposit into my CMA, and then bill payment out via their BillPay service. In other words, I have to manually schedule any money going out. I like that I can transfer money quickly to and from my other Fidelity brokerage accounts, if necessary.

The Fidelity CMA is not a bank account. It is a full brokerage account with bank features bolted-on like a debit card, check-writing, and Bill Pay. The core position is the Fidelity Government Money Market Fund (SPAXX), which has a 4.01% 7-day yield as of 1/12/25. However, at ~40% US Government Obligations in 2023, it did not meet the requirements of having interest exempt from state taxes for California, Connecticut, and New York.

However, I use automatic recurring purchase system to keep it mostly in Fidelity Treasury Only Money Market Fund (FDLXX), which has a 4.03% 7-day yield as of 1/12/25. At ~90% US Government Obligations in 2023, it did meet the requirements of having interest exempt from state taxes for California, Connecticut, and New York. If you assume a 10% state income tax rate, this works out to a tax-effective yield of ~4.4%.

Money market funds are not FDIC-insured, but they are highly-regulated after the 2008 financial crisis and I am comfortable with their safety as they hold 90% Treasury bonds and as long as I am buying from a reputable name like Fidelity.

Fidelity uses various third parties to provide their banking features. The Fidelity debit card is issued by Leader Bank, and the debit card program is administered by BNY Mellon Investment Servicing Trust Company. Fidelity works with UMB, NA to process checks and ACH transfers. The ACH routing number for Fidelity accounts is 101205681 and belongs to UMB, NA. If you experience fraud from using the debit card, then you will have to deal with BNY Mellon. These third-party providers do not have the same level of customer service reputation as Fidelity, and Fidelity seems to punt to them, and I wish to avoid dealing with any of that.

Accordingly, I never use the Fidelity Debit Card (it is locked), and I never give out the ACH routing number and account number linked to my Fidelity CMA account (besides direct deposit). Therefore, no outside entity should have the ability to “pull” money out of my CMA account. My Fidelity CMA account is also on “Fidelity Lockdown” which prevents an unauthorized ACAT transfer of my entire account. (Lockdown does not interfere with ACH transfers.)

A reader asked if Fidelity should be treated as a “Fintech” to avoid since they use a third-party to provide some of their banking services. As you can see, I do treat them with extra care because whenever there are extra parties involved, there is room for confusion and blaming each other. However, the problem with many fintechs is that they open up what is called a “FBO” (For Benefit Of) account at their partner banks, which is a big pooled account of all their customers’ money mixed together, and then the fintech or middleman keeps a ledger of individual account balances. Even though there are routing numbers and account numbers, the bank does not open an individual account for everyone. What happens when the ledger from the fintech isn’t kept accurately? How do they split up the big pool of money? Ask the Yotta app users who completely lost access to their funds for several months, and many are still waiting to this day. Apparently, if the middleman or fintech company fails, it’s a poo show. If the bank itself failed, then the depositors would supposedly have been covered.

In my case, most funds are invested in a SEC-regulated money market fund from Fidelity inside an SIPC-insured brokerage fund.

Ally Checking and Savings (ATM card, checks, Venmo, etc)
For a long time, Ally was my primary checking and savings account. Even though they are an online bank with no physical branches and thus lower overhead costs, it still offered solid customer service and well, it simply knows to be a traditional bank. I have deposited large paper checks remotely, made large wire transfers, made large ACH transfers regularly, and used their ATM card around the world. My limited interactions found a knowledgeable human on the other side of the phone. Live chat is also available.

Their website interface is also clear and reliable, with the ability to link many external accounts (many of which won’t otherwise initiate transfers themselves) and make reasonably fast transfers between all of them. For each transfer, Ally will clearly tell me ahead of time the date that the funds will be pulled from the source account, and also the date that the funds will arrive at the destination account. I’ve moved over a million dollars in aggregate around, chasing various bonuses and bringing it back. Ally never bothered me.

The interest rate is 3.80% APY as of 1/13/25, and while that isn’t horrible, Ally used to keep themselves closer to the top rates. Given the differential is now up to a full 1% APY higher at my other options when taking into account the state tax exemption, that was enough to move some funds out. I still keep enough money at Ally to cover other cash needs (ATM card, checks, Venmo, etc).

I can keep minimal amount in Ally Checking as they offer free automatic overdraft protection from a chosen Ally Savings account. If you overdraw your checking, they just pull from Ally Savings in $100 increments on demand at no cost.

The Ally ATM card has domestic ATM rebates (up to $10 per statement cycle) and does not charge a fee on their side on international withdrawals. If I am facing a lot of international ATM fees, I can unlock my Fidelity ATM card temporarily for the rebates. However, in reality, I’d rather deal with Ally rather than Fidelity/BNY Mellon if I have a problem with a foreign ATM skimmer or something, so I just use my reliable Ally ATM card, pay the $5 or whatever, and take all the cash out I need in one transaction per trip.

Vanguard Treasury Money Market Fund
One of the main draws of keeping a Vanguard account remains that they don’t play any funny games with cash sweep. Fidelity charges what I would say is a reasonable amount for its services, while Schwab straight-up hopes you aren’t paying attention while they pay you nearly nothing. Your cash sweep is the Vanguard Federal Money Market Fund (VMFXX), which has a 4.27% 7-day yield as of 1/12/25. However, based on history it also may not qualify for state tax exemptions in any given tax year.

(Keep in mind that 7-day yields quoted on money market funds do not include compounding, so a constant 4.27% 7-day yield is the equivalent of 4.35% APY.)

For larger cash balances, I use the Vanguard Treasury Money Market Fund VUSXX which has a 4.34% 7-day yield as of 1/10/25. At ~80% US Government Obligations in 2023, it did meet the requirements of having interest exempt from state taxes for California, Connecticut, and New York. If you assume a 10% state income tax rate, this works out to a tax-effective yield of ~4.8%. This is as good as the top 1% of savings rates out there.

I don’t use VUSXX for any bank features, so there is little need to contact customer service. It just earns a reliably high interest rate due to its low expense ratio (0.09%) and mostly holding short-term US Treasury bonds directly.

Note: An honorable mention goes out to iShares 0-3 Month Treasury Bond ETF (SGOV), which has the same low expense ratio (0.09%). Trading it will expose you to a small bid/ask spread of about 0.01% for each trade, though. But if I’m holding at some new brokerage for a while, then SGOV is my go-to cash equivalent holding.

The rest
I maintain minimal balances in a local megabank bank account and a local credit union account, in case a physical bank branch is useful for whatever reason – unlimited ATM access, cash deposits/withdrawals, safety deposit box, notary, medallion guarantee, etc.

I also have some existing certificates of deposit from credit unions that I am waiting to mature, like the 5-year 5.00% APY CD I bought in 2023. I just don’t like the idea of my wife having to track down four different credit unions one day to piece together my crazy CD ladder.

Recap. My simplified cash setup utilizes existing brokerage account relationships and the fact that US Treasury interest is exempt from state income taxes to maximize my tax-effective yield earned on cash while minimizing the work required to chase rates across several smaller banks, fintechs, and credit unions. It also minimizes exposure to poor customer service. I maintain liquid access to cash, and my top option pays roughly an effective 4.80% APY, and overall is quite competitive with what I could achieve if I did constantly chase rates.