Why I Open My Junk Mail… 12,000 More Miles From Discover

I always read my junk mail. You never know when you’ll get a juicy targeted offer not available to the general public. It may be extra cashback on a specific category, or just 0% APR with no balance transfer fees from a bank that usually charges fees. Besides, I have to open it to shred it anyways, and after a while you become a pro at sifting through the fine print instantly.

In this case, I got my Discover Miles Card back when it was offering a 5,000 mile signup bonus. Now, it’s offering a 12,000 miles bonus over 12 months. I cashed in my bonus miles and have been happily earning 5+% interest on my borrowed free money. But for some reason, I just got a letter saying I’m getting a replacement card and I get the 12,000 miles bones offer as well. Same rules, I have to make a purchase once a month (still 0% for purchases for me, so no problem). So if you have this card, keep an eye out. 12,000 miles is worth over $75 in gift cards.

Of course, you may not agree with me and want to save some trees (though I do recycle). In that case, you can opt out of pre-screened credit offers by either calling 1-888-5OPTOUT or going here. For more information visit (and proof that these sites aren’t scams), visit FTC.gov.
American Express Version of Citi Dividend Card

Citi plus Amex logos

(This entry used to be about the Citi Dividend Card, but it has been discontinued. I’m going to wait for the dust to settle and put up some good alternatives.)

Another option is the one I took, which is to get the Citi Driver’s Edge Card.

Getting A Credit Card to Give Me A Free Set of Tires

free tiresI just applied for the Citi Driver’s Edge Platinum MasterCard that I wrote more about previously. I’m driving a lot more this summer and therefore also spending a lot more on gas, so the 6% cash back on gas and groceries will come in handy. I’m also getting close to the $300 annual cap on my Dividend card this year, so I need another card anyways to fill that gap.
Also, I’ll also be able to rack up those Drive Rebates that give me cash for driving miles. If you drive enough, it effectively doubles your cash back percentage as the drive rebates match the cashback rebates. So in this case, you could get up to 12% back in the first year, and 6% back in subsequent years. I figured out that I can pay for my complete next set of 4 tires with this card:
[Read more…]

Fidelity 529 CashBack Deposit

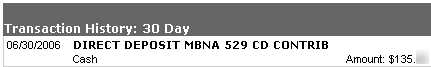
The end of the 2nd quarter of 2006 brings me a nice $135 deposit from my MBNA Fidelity 529 Card into my 529 account. Paying for everything humanly possible with credit cards has its rewards!*

529 money deposit

[Read more…]

And You Thought You Had A Hard Time Cancelling!

If you’ve already hard about the guy who had the worst time ever cancelling his AOL account… and recorded the entire conversation, then skip the rest of this post. Otherwise, turn down the volume in your office cubicle and watch this:
[Read more…]

Best ATM or Credit Card For Foreign Travel?

Just because you’re overseas on vacation, doesn’t mean you shouldn’t still pay attention to fees. Visa and Mastercard charge a standard 1% “conversion” fee on all foreign transactions (even if they are in US dollars!.) Many major credit card issuers charge you up to another 3% on top of that. Why? Because they can.

But by selected the best credit card in your arsenal, you can minimize the damage. Flyertalk has a great resource listing all the card issuers and the rates they charge. Don’t forget to also take into account the cashback program of your specific card, as you’ll still earn it on foreign purchases.
[Read more…]

What’s a Hard Credit Check, And Why They’re Valuable

I talk a lot about “hard” and “soft” credit pulls. I don’t think I’ve ever actually seen these terms used by FICO officials, so it may be kind of confusing. Money geek slang, who knew? A credit check, also known as credit pull or credit inquiry, is (logically) when a third party wants to examine at your credit history.

A “soft” pull is one that does not affect your credit score. You can get 1,000 of these and it won’t matter as they are not visible to other people checking your credit. These are often done without your knowledge as long as they have a “permissible purpose by law”, and may include:
[Read more…]

Credit Score Myths – Don’t Cancel Old Accounts

Credit scores remain all the rage, but there are a lot of misconceptions out there. Four common ones are outlined in this MSN Money article titled ‘4 Credit-Scoring Myths‘. What’s the first myth? That closing credit cards will help your score.

No, no, no. For the umpteenth time: Closing accounts can never help your credit score, and may hurt it… It?s true that having too many open accounts can hurt your score. But once you?ve opened the accounts, you?ve done the damage. You can?t repair it by shutting the account, and you may actually make things worse… The credit score looks at the difference between your available credit and what you?re using. Shut down accounts, and your total available credit shrinks, making your balances loom larger, which typically hurts your score.

[Read more…]

Drive A Lot? Use the Citi Driver’s Edge MasterCard

I’ve realized that I am in the minority when it comes to driving. I put on maybe 6,000 miles a year. Many people log over 20,000 miles on their car every year! If you are one of these road warriors, I just got e-mailed about the Citi Driver’s Edge Platinum Select MasterCard (Thanks JW). It looks great in multiple ways:

» You get rewards just for driving. You?ll earn $1 in Drive Rebates for every 100 miles you drive?up to $500 in Drive Rebates a year. Drive 20,000 miles a year? That’s $200 a year just for driving! To track miles and get rebates you just mail in your receipt whenever you get an oil change or other receipt.

» 6% cashback on gas for the first year. Obviously driving a lot = $$$ for gas. Assume you get 20 miles per gallon. Driving 20,000 miles, that’s 1,000 gallons. At $3 a gallon, that’s $3,000. Times 6%, that’s another $180 cashback on gas alone.

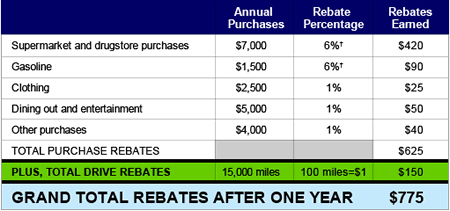
» You also get 6% back at supermarkets and drugstores for the first year (3% after that). That beats out the Citi Dividend Card (which I have) for the first year. You earn 1% on everything else. Here is Citi’s example chart of how this could add up:

Rewards Table

» There is a cap of $1,000 per year, which is significantly higher than the $300 or the Dividend card as well and allows you to rack up more cash.

Come to think of it, this is not a bad card just to keep around. If you drive 10,000 miles in a year, that’s still $100 a year just for
driving. There is also no annual fee. What other card does that?

Rebates do expire if you don’t make a purchase in a year or if you don’t redeem within 5 years. Not too harsh. It’s all spelled out in the fine print on the application, so be sure to save a copy.

There is also a 0% APR balance transfer offer with this card, and as such is for people with good credit. But do not use it if you want to get these rebates. Remember, all payments go towards the balance at lowest interest rate.

What’s the catch?
The DriveRebates are redeemable as straight cash only towards car expenses. But that’s any car expenses – buying a car, leasing a car, oil changes, new tires, repairs, etc.

But, they can also be converted to ThankYou points. Each $1 in Driver?s Edge rebates is equivalent to 100 ThankYou Points, or put another way $100 in rebates can be converted to a $100 Gift Card at Target, Chevron, Gap, etc. Note: If you have student loans, you can still get straight cash towards those.

I think the easiest way to cash in on these points is just to get gas cards. Sure, you won’t be able to get 6% back anymore by buying with this credit card, but even after accounting for that you’re still getting 5.64% back which is still very good.

Hmmm…
As I write this, I’m convincing myself more and more to apply for this card. Even if I only drive 6,000 miles a year, that’s $60 – which will basically pay for all my oil changes and tires every year.

Update: I applied for this card myself, going to redeem for either gas or a set of tires.

Free Equifax Credit Alerts via PayPal

Equifax and PayPal have teamed up to provide a basic credit monitoring service that is free to anyone. I say it’s free to anyone because after you click on the sign-up link, there is no verification that you actually use PayPal when signing up. In fact, I already had an Equifax login from my free government-mandated credit reports, so I just used that and it grabbed all my info automatically. Two types of alerts are included:

  • Upon an Equifax credit inquiry, or a
  • Balance change over a chosen percentage or dollar amount.

I signed up a few days ago, and got my first balance alert today. It doesn’t tell you which credit card triggered the alert, which is a bummer. Still, not bad for free and now I’ll know when my Equifax credit is pulled.

Are Credit Card CashBack Rebates Taxable?

Hmm… the media seems to be addressing all my questions today. This Wall Street Journal column addresses the taxation of credit card rebates:

The IRS hasn’t issued any specific public guidance on whether cash-back card rebates are subject to income tax, says an agency spokesman. But the IRS did issue a private-letter ruling in 2002 that said certain card rebates aren’t included in a taxpayer’s gross income. Although a private-letter ruling applies only to the taxpayer that applied for it, such rulings are considered to be a gauge of the agency’s thinking on a particular issue. Tax advisers say rebates are generally considered to be a reduction in purchase price, and not likely to be taxed. Rebates on purchases made for business or investment may have more complex treatment, so consult a tax adviser.

In short, the IRS hasn’t said anything specific either way, but has ruled in specific cases that they are not taxable. Although certainly not concrete, this is still reassuring as I personally have never reported any of my cashback as income.

I would estimate I pull in well over $1,000 a year in free money from credit cards, with my 2 to 5% back on all my purchases as well as signing up for $100 to $250 in upfront incentives. The great thing is that anyone with decent credit can get in on these offers. Article via Boston Gal’s Open Wallet.

Deconstructing My 3 Free Credit Reports

For some reason, I felt like I should check all of my credit reports today. I think it was because I knew my new landlord had run our credit, and I also haven’t checked them in a while. Remember, the government mandates that everyone gets 1 free credit report (but not score) every year from each of the 3 credit bureaus at AnnualCreditReport.com. You can get all three at once, or space it out. I requested all three so I could compare them all side-by-side.

Besides, if I want my credit report again I can always go to sites like Credit.com and get one free with a trial subscription. I’ll have to cancel within 30 days or get charged something, but you get the credit report instantly, so why wait 30 days? I usually cancel the same or very next day! Another bonus is that you can also get your credit score for free as well, which is usually $8 everywhere else.
[Read more…]