Cashing Out My 529 Plan

As noted in my net worth updates, I have 529 account as part of my Fidelity 2% Cash Back card. The 2% is nice, but the only way to get your contributions and earnings out of the 529 tax-free is to have real college expenses.

Now that I’m in college, no problem right? But then I read that the same college expenses cannot be both reimbursed by a 529 account and be used in claiming my Lifetime Learning Credit. I don’t have more than $10,000 in tuition, and getting 20% back is much better than cashing out my 529 tax-free. So I was bummed, until I read that 529 plans are also allowed to cover room and board, which the Lifetime Learning Credit does not. Yes!
[Read more…]

Tips and Tools for 0% APR Balance Transfers

Please also see my updated guide on
How To Make Money From 0% APR Balance Transfers

do not forgetSo you’ve gotten yourself a nice credit card or two, and have already started or are thinking about playing the 0% APR balance transfer game. Now, there are two simple but very important things that you need to remember to do: pay the minimum balance every month on time, and pay off the entire balance when the 0% APR period is over on time. Here’s one tip/tool for each:

Pay the minimum each month automatically with Online Bill Pay – I love Online Bill Pay, I don’t know how I lived without it. Say I have a $20,000 balance at 0%. When you get the first statement, you’ll see the minimum payment is usually something like 2% of the balance, for example $400. As long as they don’t change this, then every single payment after that will be less than $400 as your remaining balance decreases. So, just set your Online Bill Payment to automatically pay that account $400 every month, and you’re set!
[Read more…]

Credit Transfer Denied, But With Possible $100 Silver Lining

So I asked if I could transfer my credit limit from my other Citi credit cards to my new Citibank Professional Card, as discussed previously. I got the same answer that other readers got – No, because it is considered a professional/business card. So I can’t increase my current $9,000 limit. But then I recalled that most business cards are not reported on your consumer credit report, but on a separate business credit report. I asked a Citi Rep about this but she obviously didn’t know the difference. I’ll have to check my credit report after 30 days to see.

The reason why this is good is because if I it is not on my credit report, then I can take out the whole amount and it won’t affect my regular credit score! Which means I can apply for more cards with bonuses later ๐Ÿ˜‰

Credit Limit Transfer Denied, But With Possible $100 Silver Lining

So I asked if I could transfer my credit limit from my other Citi credit cards to my new Citibank Professional Card, as discussed previously. I got the same answer that other readers got – No, because it is considered a professional/business card. So I can’t increase my current $9,000 limit. But then I recalled that most business cards are not reported on your consumer credit report, but on a seperate business credit report. I asked a Citi Rep about this but she obviously didn’t know the difference. I’ll have to check my credit report after 30 days to see.

The reason why this is good is because if I it is not on my credit report, then I can take out the whole amount and it won’t affect my regular credit score! Which means I can apply for more cards with bonuses later ๐Ÿ˜‰

Redistributing or Moving Credit Limits Between Credit Cards

Please also see my updated guide on
How To Make Money From 0% APR Balance Transfers

When you do one of these 0% balance transfer deals, you want the biggest limit you can get for a couple of reasons.

1) More free money. More borrowed money = more interest earned = more free money.

2) Keep your credit score high. Say you already have a $9,000 balance. A $9,000 balance on a card with a $10,000 limit hurts your credit more than the same balance with a $20,000 limit.

3) Feed your ego. Knowing I could buy that Mini Cooper right now on my credit card gives me the warm fuzzies. ๐Ÿ˜‰

For example, now that I have a new Citi Professional card with a $9,000 limit and a 0% balance transfer that I can take advantage of at any time within the next year, I am going to shift all the limits on my other Citi cards onto this one.
[Read more…]

Recent Citi / Discover Credit Card Application Updates

Recently I gave into temptation and applied for two new credit cards with nice perks and no-fee balance transfers: the Citi Professional Card and the Discover Miles Card. I got approved for the Citi card right away and got a $9,000 credit limit. I’m going to make a purchase right away and get my $100 gift card. I’ll also call Citi and move my credit limits from my dormant Citibank cards to this one increase the limit to close to $20,000, making it nice and ripe for a future 0% APR balance transfer.

I haven’t heard from Discover yet, the online application said it might take up to four weeks for a decision? Sounds like a long time to me. I did request $15,000 in balance transfers, so maybe they’re pondering if I’m worthy ๐Ÿ˜‰ I also moved recently (less than a year).

Maximizing Your Citi / Chase 5% Cash Back Cards

For those of you that have the Citi Dividend Platinum Card that gives you 5% cash back for supermarkets, drugstores, and gas stations – be sure to use them to their fullest.

1) Gift Cards – Don’t buy at the retail store, try to buy them at the supermarket and earn yourself 5% cash back! (They can’t tell the difference, a purchase is a purchase) Safeway is my favorite, they have a great selection which includes AMC Theatres, REI, Barnes & Noble, Bed Bath and Beyond, Blockbuster, Chili?s, SpaWish, Circuit City, Starbucks, CompUSA, Home Depot, Toy’s R Us, Old Navy, and more! [Full list]

2) Super Targets – Reportedly, people have had Super Targets treat all purchases as a grocery purchase! That means even if you buy a $500 LCD TV or other toys, they’ll give you 5% cash back! If you have a Super Target nearby, that is an awesome deal. I would try it out for a month first and see if it shows up as 5% back on your next statement.

Giving In To The Credit Cards

(Typing quietly while the parents are still asleep, shh…) I’ve decided to take advantage of two recent credit card offers:

1) The Citi Professional Card for it’s 3% back on restaurants, $100 bonus, and save-able 0% balance transfer, and

2) The Discover Miles Card for it’s no-fee 0% balance transfer for 12 months.

I was going to apply for another Citi Card, but I decided that would be redundant since you can move credit limits around with Citi and simply put all your credit limit onto the one card you are using for 0%. I am going to apply for both at the same today, hopefully today. I’ll post more on why later, but it’s basically so the credit agencies won’t be able to see I applied for the other card, maximizing my credit limit and chance at acceptance for both cards. Now to figure out exactly how to cook a turkey.

$100 Gift Cards for Citi Professional Card and AT&T Universal Card

I just came across some tasty cards that are currently offering $100 gift cards for opening!

Citi Professional MasterCard – 10,000 Thank You Points after your first $250 in purchases, which is the same as a $100 gift card at various places like Gas Stations, Home Depot, Target, Gap, and more. For students you can get $100 in straight cash for college loans.

You also get 3 points per dollar (~3% back in gift cards) on restaurant, gas station, auto rentals, and certain office supply merchants. 3% cash back on restaurants is nice. Auto rentals and office supplies stores, not so much, but hey it’s there. They also add some other features like expense tracking and special phone reps. I wish I had this card when I was consulting and and travelling all the time. I miss my expense account ๐Ÿ™‚ Oh, and you don’t need to be a “Professional” to apply.

$100 Bonus + up to 100,000 miles/points from American Express
This is for the New Business Gold Rewards Card from American Express OPEN. You can get $100 + 5,000 miles just for applying and making a purchase, and a lot more points if you use the card more. More details on the bonus and card here. You can get $100 + 5,000 miles just for applying and making a purchase, and a lot more points if you use the card more. Remember, anyone can apply for a business credit card.

Update: The above promotion is now expired. The New Business Gold Rewards Cardยฎ from American Express OPEN now offers 3X points on airfare, 2X points on advertising, gas, and shipping and 1X point on everything else. The annual fee for this card is $175 but it is waived for all new cardholders. You can also get unlimited additional gold cards for an extra annual fee of $50 but this fee is waived for the first year as well.


What Makes Up Your FICO Score?

I just stumbled upon this article at Bankrate.com titled ‘How credit scores work‘. It seems a little old, but it’s new to me. The credit score powerhouse Fair Isaac (think FICO), is interviewed in the article, so that gives it some credibility. Here’s the skinny on what makes up your credit score, from most important to least:

35% – How you pay your bills (on time or not) – I don’t really have to worry about this one.

30% – Amount of money you owe and the amount of available credit – It’s not just how much debt you’re carrying, it’s how much of your available debt you’re taking advantage of. Another reason why it may not be a good idea to cancel unused credit cards.
[Read more…]

Holding Off On Credit Cards… For Now

With all these higher interest rate opportunities like T-Bills ans SavingsBonds, I’ve been itching to apply for another of my favorite 0% balance transfer offers after recently paying off one of my current ones, but I’ve decided to wait at least another couple weeks. My reason? I figured since I just went from over 50% utilization of one credit card to zero, my credit score will jump up once all the credit bureaus hear about it. (Also supported by the FICO Score Estimator.) But since they only seem to get information once a month, they may not know about my good deeds yet. And I want the fattest credit limit I can get so I can maximize my earn interest off of borrowed free money.

So for now, I’ll have to be patient, and maybe find some more tasty credit offers.

Choosing Card Issuers for 0% APR Balance Transfer Offers

Please also see my updated guide on
How To Make Money From 0% APR Balance Transfers

I haven’t been as active in the 0% APR balance transfers game recently (still have $20k in borrowed money), but sometimes the trickiest part after finding the best 0% offer is to figure out how to get your cash.

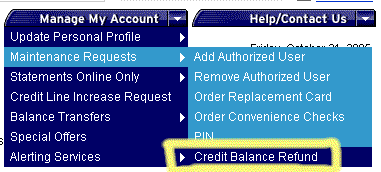
It seems like some issuers are not playing well with others recently. Flexo at Consumerism Commentary reports having his credit balance request sent from Discover denied by MBNA. I’ve heard similar problems with American Express, although I have gotten checks from them before. The good news is that if you transfer to Citibank, they now let you request a check for any credit balance online. So for sure they let you do it, and on top of that there’s no human to question your motives (not that you’re doing anything wrong). Definitely the best choice, if you have to go that route.

Of course ideally, they just let you write a check directly to yourself for the money, or take your bank info and electronically transfer it there. Banks that I have done this with before, and from what I hear continue to do so, include Citibank, MBNA, and Chase. Bank of America used to, but they just bought MBNA, so I’d double-check. Overall, Citibank seems to be the most flexible care issuer, either as the place you get the balance transfer or the place to send it to. Nice that they also back it up with great Rewards cards.

I’ve updated my How-To Play the 0% APR Game post to reflect these changes.

Added: Here is a screenshot of me requesting a credit balance refund on my Citi card:

Credit Balance Request Screenshot