Best Interest Rates on Cash: Bank Accounts, Treasury Bills, Money Markets, ETFs – August 2026

Here’s my monthly survey of the best interest rates on cash as of August 2026, roughly sorted from shortest to longest maturities. Banks and brokerages love taking advantage of idle cash, and you can often earn more interest while keeping the same level of safety by moving to another FDIC-insured bank or NCUA-insured credit union. Check out my Ultimate Rate-Chaser Calculator to see how much extra interest you could earn from switching. Rates listed are available to everyone nationwide. Rates checked as of 8/16/26.

TL;DR: Savings account interest rates dropped slightly overall, while rates on longer-term CD rose slightly. You can get 4.34% APY if you accept certain hoops/restrictions, but most are under 4% now. Short-term T-Bill rates ~3.7%. Top 5-year CD rates are ~4.5% APY, while the 5-year Treasury rate is ~4.4%.

High-yield savings accounts*
Since the huge megabanks still pay essentially zero interest, everyone should at least have a separate, no-fee online savings account to piggy-back onto your existing checking account. The interest rates on savings accounts can drop at any time, so I list the top rates as well as competitive rates from banks with a history of competitive rates and solid user experience. Some banks will bait you with a temporary top rate and then lower the rates in the hopes that you are too lazy to leave.

  • The top saving rate at the moment: Elevault (no min) is at 4.34% APY, a division of Southern Bancorp Bank.
  • SoFi Bank is at 3.10% APY (new customers can get up to $475 in bonuses with qualifying direct deposit. You must maintain a direct deposit of any amount (even $1) each month for the higher ongoing APY. SoFi has historically competitive rates and full banking features.
  • Here is a limited survey of high-yield savings accounts. They aren’t the top rates, but a group that have historically kept it relatively competitive such that I like to track their history. This month they start at 3.00% APY on up.

Short-term guaranteed rates (1 year and under)
A common question is what to do with a big pile of cash that you’re waiting to deploy shortly (plan to buy a house soon, just sold your house, just sold your business, legal settlement, inheritance). My usual advice is to keep things simple and take your time. If not a savings account, then put it in a flexible short-term CD under the FDIC limits until you have a plan.

  • No Penalty CDs offer a fixed interest rate that can never go down, but you can still take out your money (once) without any fees if you want to use it elsewhere. Marcus has a 11-month No Penalty CD at 4.00% APY ($500 minimum deposit). Farmer’s Insurance FCU has a 9-month No Penalty CD at 4.00% APY ($1,000 minimum deposit). USALLIANCE Financial CU has a 11-month No Penalty CD at 4.00% APY ($500 minimum deposit).
  • CFG Bank has a 12-month CD at 4.30% APY (no minimum deposit). Early withdrawal penalty is not clearly disclosed, I would assume at least 180 days of interest.

Money market mutual funds
Many brokerage firms that pay out very little interest on their default cash sweep funds (and keep the difference for themselves). Note: Money market mutual funds are highly-regulated, but ultimately not FDIC-insured, so I would still stick with highly reputable firms.

  • Vanguard Federal Money Market Fund (VMFXX) is the default sweep option for Vanguard brokerage accounts, which has a 7-day SEC yield of 3.61% (changes daily, but also works out to a compound yield of 3.67%, which is better for comparing against APY). Odds are this is much higher than your own broker’s default cash sweep interest rate.
  • Vanguard Treasury Money Market Fund (VUSXX) is an alternative money market fund which you must manually purchase, but the interest will be mostly (100% for 2025 tax year) exempt from state and local income taxes because it comes from qualifying US government obligations. Current 7-day SEC yield of 3.68% (compound yield of 3.74%).

Treasury Bills and Ultra-short Treasury ETFs
Another option is to buy individual Treasury bills which come in a variety of maturities from 4-weeks to 52-weeks and are fully backed by the US government. You can also invest in ETFs that hold a rotating basket of short-term Treasury Bills for you, while charging a small management fee for doing so. T-bill interest is exempt from state and local income taxes, which can make a significant difference in your effective yield.

  • You can build your own T-Bill ladder at TreasuryDirect.gov or via a brokerage account with a bond desk like Vanguard and Fidelity. Here are the current Treasury Bill rates. As of 8/14/26, a new 4-week T-Bill had the equivalent of 3.70% annualized interest and a 52-week T-Bill had the equivalent of 3.97% annualized interest.
  • The iShares 0-3 Month Treasury Bond ETF (SGOV) has a 3.60% 30-day SEC yield (0.09% expense ratio) and effective duration of 0.10 years. The Vanguard 0-3 Month Treasury Bill ETF (VBIL) has a 3.62% 30-day SEC yield (0.06% expense ratio) and effective duration of 0.10 years.

US Savings Bonds
Series I Savings Bonds offer rates that are linked to inflation and backed by the US government. You must hold them for at least a year. If you redeem them within 5 years there is a penalty of the last 3 months of interest. The annual purchase limit for electronic I bonds is $10,000 per Social Security Number, available online at TreasuryDirect.gov.

  • “I Bonds” bought between May 2026 and October 2026 will earn a 4.26% rate for the first six months. The rate of the subsequent 6-month period will be based on inflation again. More on Savings Bonds here.
  • In mid-October 2026, the CPI will be announced and you will have a short period where you will have a very close estimate of the rate for the next 12 months. I will post another update at that time.

Rewards checking accounts
These unique checking accounts pay above-average interest rates, but with unique risks. You have to jump through certain hoops which usually involve 10+ debit card purchases each cycle, a certain number of ACH/direct deposits, and/or a certain number of logins per month. If you make a mistake (or they judge that you did) you risk earning zero interest for that month. Some folks don’t mind the extra work and attention required, while others would rather not bother. Rates can also drop suddenly, leaving a “bait-and-switch” feeling.

  • La Capitol Federal Credit Union pays 6.50% APY on up to $10,000 if you make 15 debit card purchases of at least $5 each per statement cycle. Anyone can join this credit union via partner organization, Louisiana Association for Personal Financial Achievement ($20).
  • OnPath Federal Credit Union (my review) pays 6.00% APY on up to $10,000 if you make 15 debit card purchases, opt into online statements, and login to online or mobile banking once per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization. You can also get a $150 Visa Reward card when you open a new account and make qualifying transactions.
  • Genisys Credit Union pays 6.75% APY on up to $7,500 if you make 10 debit card purchases of $5+ each per statement cycle, and opt into online statements. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Oklahoma Central Credit Union pays 6.00% APY on up to $10,000 if you make 15 debit card purchases (non-ATM) per statement cycle. Anyone can join this credit union if they are “affiliated with another credit union”.
  • First Southern Bank pays 5.50% APY on up to $25,000 if you make at least 15 debit card purchases, 1 ACH credit or payment transaction, and enroll in online statements.
  • Credit Union of New Jersey pays 6.00% APY on up to $25,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit, online bill payment, or automatic payment (ACH) per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Andrews Federal Credit Union pays 5.25% APY on up to $25,000 if you make 15 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization.
  • Capitol Credit Union pays 6.00% APY on up to $15,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization ($5 to Wild Basin Wilderness).
  • Find a locally-restricted rewards checking account at DepositAccounts.

Certificates of deposit (greater than 1 year)
CDs offer higher rates, but come with an early withdrawal penalty. By finding a bank CD with a reasonable early withdrawal penalty, you can enjoy higher rates but maintain access in a true emergency. Alternatively, consider building a CD ladder of different maturity lengths (ex. 1/2/3/4/5-years) such that you have access to part of the ladder each year, but your blended interest rate is higher than a savings account. When one CD matures, use that money to buy another 5-year CD to keep the ladder going. Some CDs also offer “add-ons” where you can deposit more funds if rates drop.

  • NASA Federal Credit Union has a 5-year certificate at 4.38% APY ($1,000 minimum), 4-year at 4.30% APY, 3-year at 4.25% APY, 2-year at 4.20% APY, and 1-year at 4.15% APY. Early withdrawal penalty for the 5-year is 365 days of interest. Anyone nationwide can join via a complimentary membership to the National Space Society (NSS).
  • Advancial Federal Credit Union has has a 5-year certificates at 4.28%/4.39%/4.49% APY APY based on either a $1,000/$25,000/$50,000 opening balance. Early withdrawal penalty for the 5-year is 365 days of interest. Anyone nationwide should be able to join via membership with partner organization US Dog Agility Association, but I would call to verify first.
  • Popular Direct has a 5-year certificate at 4.50% APY ($10,000 minimum) but with a huge early withdrawal penalty of 730 days of interest.
  • You can buy certificates of deposit via the bond desks of Vanguard and Fidelity. You may need an account to see the rates. These “brokered CDs” offer FDIC insurance and easy laddering, but they don’t come with predictable early withdrawal penalties. Right now, I see a 5-year non-callable brokered CD at 4.50% APY (callable: no, call protection: yes). Be warned that both Vanguard and Fidelity will list higher rates from callable CDs, which importantly means they can (and will!) call back your CD if rates drop significantly later.

Longer-term Instruments
I’d use these with caution due to increased interest rate risk (tbh, I don’t use them at all), but I still track them to see the rest of the current yield curve.

  • Willing to lock up your money for 10 years? You can buy long-term certificates of deposit via the bond desks of Vanguard and Fidelity. These “brokered CDs” offer FDIC insurance, but they don’t come with predictable early withdrawal penalties. You might find something that pays more than your other brokerage cash and Treasury options. Right now, I see a 10-year CDs at 4.65% APY (non-callable) vs. 4.67% for a 10-year Treasury. Watch out for higher rates from callable CDs where they can call your CD back if interest rates drop.

All rates were checked as of 8/16/26.

* I no longer recommend fintech companies due to the possibility of significant loss due to poor recordkeeping and the lack of government protection in such scenarios. The point of cash is absolute safety of principal.

Photo by Giorgio Trovato on Unsplash

Citi AAdvantage Platinum Select Credit Card Review: 80,000 Bonus Miles (Limited-Time Offer)

Limited-time offer is back. The Citi AAdvantage Platinum Select World Elite Mastercard is the co-branded American Airlines card from Citi. The sign-up bonus varies, but since you can only get it once every 48 months, right now is a good time with an elevated 80k bonus and the annual fee being waived. Here are the updated card highlights:

  • 80,000 American Airlines miles after $3,500 in purchases within the first 4 months of account opening.
  • First checked bag free on domestic American Airlines itineraries for you and up to 4 travel companions on the same reservation – savings of up to $500 per round trip.
  • 2X AAdvantage® miles for every $1 spent at gas stations
  • 2X AAdvantage® miles for every $1 spent at restaurants
  • 2X AAdvantage® miles for every $1 spent on eligible American Airlines purchases*
  • 1 Loyalty Point for every 1 eligible AAdvantage(R) mile earned from purchases.
  • $125 American Airlines Flight Discount after you spend $20,000 or more in purchases during your cardmembership year and renew your card.
  • No Foreign Transaction Fees*
  • Preferred boarding on American Airlines flights
  • 25% savings on inflight food and beverage purchases when you use your card on American Airlines flights
  • $0 intro annual fee for the first year, then $99.

Bonus details. Note the following language for the personal card, which has been changed from 24 to 48 months. Having the business version is okay.

American Airlines AAdvantage® bonus miles are not available if you have received a new account bonus for a Citi® / AAdvantage® Platinum Select® account in the past 48 months or if you converted another Citi credit card account on which you earned a new account bonus in the last 48 months into a Citi® / AAdvantage® Platinum Select® account.

To clarify, you can have one of both the consumer version of this card and the CitiBusiness® version designed for businesses under your name. The bonuses are also separate.

Baggage fee value. American Airlines now charges a whopping $50 one-way for the first checked bag if you don’t prepay online ($45 if you prepay online). That’s $100 roundtrip for a single checked bag, per person. With this card, your first checked bag is free on domestic American Airlines itineraries for you and up to four companions traveling with you on the same reservation. $100 roundtrip x 5 people = $500 potential benefit.

Bottom line.  The Citi® / AAdvantage® Platinum® Select® World® Elite® Mastercard® has® a® nice® bonus® offer®. As with most of these co-branded cards, a lot of the ongoing value comes when you fly on American and utilize the free first checked bag benefit for you and up to 4 companions (value of up to $100 per person, round-trip).

Paze Promo: $10 Credit x 10 Uses = $100 Total Per Linked Card (Old Discover Cards Now Work)

As of 9/27/26, most Discover cards were transitioned to Capital One. Capital One cards work with Paze, so now you might have some new sources of $10 credits! My family just ordered another 3 x $10 of Domino’s last week. To add them, log into Paze at www.paze.com, look to add a new card, click on Capital One, and log into your Capital One account.

Paze is a new online checkout shortcut where you don’t have to type in your credit card number and billing address details repeatedly (think of how “Apple Pay” or “Google Pay” are so convenient), this time backed by a bunch of different banks and credit unions. In order to build a habit, Paze is running a Spend $10, Get $10 promo that works up to 10 times per linked card. That means it could be worth $100 per linked card, and so if you have 5 linked cards for example, that’s up to $500 in credits. Here is a list of current Paze merchants.

Between June 15, 2026 and September 10, 2026, each time you spend $10 or more using Paze® in a single transaction at a participating merchant, you’ll receive a $10 statement credit.

You can earn this credit up to 10 times, for up to $100 back per card in your Paze wallet. Paze is accepted at a growing list of online merchants – see the full list here.

Note: Chase Sapphire and Freedom cards are also offering a separate promo for 10X points per $1 spent on Paze purchases right now. You can verify this in your Chase App under the Benefits section for your Sapphire Preferred/Reserve and Freedom Flex/Unlimited cards. A nice stacking opportunity. You can also link them to Paze directly in your Chase App under “More” in the bottom right corner and then “Digital Wallets”.

Here are a few ideas on how to spend this credit efficiently. Remember, each purchase just has to total $10 to trigger the credit, so you want to get as close to that minimum as possible.

  • $10 Dunkin gift cards. Dunkin App, Scan/Pay, Pay Another Way, Add A Dunkin Card, No, Next, $10, Paze. You now need to wait 24 hours per $10 load.
  • $10+ Domino’s pizza for carry-out. You can’t buy a $10 gift card through their app, but you can make multiple takeout orders for just over $10 and just pick them up all at once.
  • $10 Fanatics gift card (limited). I was able to buy one but not a second immediately after. According to a commenter on Reddit who contacted customer support, there is a cooldown period. But since this promo lasts until September, you could still accumulate a decent amount of gift cards over time.
  • Meals just over $10 from Wendy’s. Order in the app or online.
  • Items just over $10 from Sephora. Order in the app or online.
  • Items just over $10 from Newegg.com Gift cards are no longer a good option.
  • Any other ideas?

PFS Buyers Club: New US Mint Coin Arbitrage Opportunity (~$138 Net Profit, 7/21/26)

(Update 7/13: There are additional new deals on July 16th, which is even higher demand. One has a cost of $755.95 and a profit of $244.05 per order. Basic deal structure is the same. Sign-up for an account below to get the details. Good luck!)

New deal July 21st, 2026. The US Mint regularly releases limited-edition coins to collectors. The coin sets are often limited to one per household, but end up with a market value greater than the initial cost. PFS Buyers Club is a website broker that recruits regular folks to buy their allotted coin set with a set markup amount, with the agreement that they will sell only to PFS Buyers Club. For example, you might pay $300 for a coin and they’ll agree to pay you $350 for it – a fixed profit of $50.

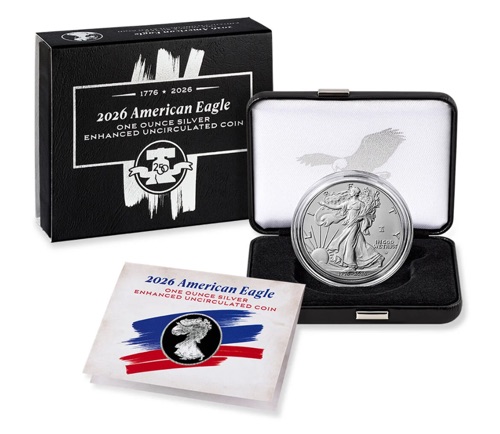
On Tuesday, July 21st at 12:00 pm Noon Eastern Time, there is a new guaranteed profit opportunity. A limited edition American Eagle 2026 One Ounce Silver Enhanced Uncirculated Coin will be released then, with a purchase limit of ten (10) per household.

PFS will pay you a fixed commission of $104.05 for 10 coins (must be exactly 10), on top of your cost for the set. The total paid is $1,800. The cost of each order of ten coins will be $1,690. After including the $5.95 shipping charge, each order’s total will be $1,695.95. If you subscribed to these or have already made three purchases with the Mint this year, you should get free shipping.

You’ll also earn credit card rewards on your ~$1,700 purchase (worth another ~$34 at 2% cash back), or also possibly satisfying the requirements for some $500+ value credit card bonuses. This makes the total net profit safely around $138.

Note that the eventual value of the set may exceed that elsewhere – you may see a higher bid on eBay, for example – but if you want to make that bet, don’t promise to sell to PFS Buyers Club. Just buy it on your own and try to sell it yourself. Keep in mind that eBay seller fees can be quite high (13.25%+ of the final selling price + PayPal fees), and you’ll be responsible for other costs like the proper shipping with adequate insurance. PFS Buyers Club will send you a free prepaid mailing label (including tracking and insurance) and pay you via eCheck, paper check, or PayPal. Even as an experienced eBay seller, I still prefer a low-stress experience when dealing with these types of valuables. You don’t have the risk of a price drop, or a random eBay user who claims never to have received your coin.

My past experience. I have used PFS successfully several times since 2021. Everything has gone smoothly each time and I have been paid my money in full without issue. The amount of communication was great and in fact better than expected; I was kept up-to-date every step of the way.

The total time commitment was the stop at the Fedex store to drop off the box with prepaid label. The eCheck option worked great – I printed the check out at home and deposited immediately via mobile app. PFS has a very solid reputation online. Their success has spawned many competitors, and some may offer you more money than PFS. I have nothing positive or negative to say about the competitors, as I have never used them. As always, I try to write based on my own personal experience. However, if this is your very first deal, I would consider PFS because they have the longest reputation and a time-tested process. I think it’s a good setup for beginners (well, those who are good at following directions) and folks who want minimal risk like myself.

If this interests you, you can sign up to join PFS Buyers Club here to see the details on the current offers (there may be another deal coming up soon on 7/16). Sometimes these deals fill up, so I would sign-up (it’s free) and opt-in sooner rather than later. You can still opt out of the deal until an hour prior to the coins going on sale. They will provide very detailed instructions. Follow them carefully, and it was pretty easy for me as a first-time buyer. If you use that link, I will receive a referral fee the first time you successfully sell your coin for a profit. Thanks for those that use it, and for those that already used it years ago! You’ll also be notified for future deals, some of which have very little upfront notice.

(p.s. I don’t write about coin deals often, the last one I wrote about was back in 2022 I think, this one just seemed to be a good mix of profit and spend. Some deals require a huge upfront purchase, and others the profit is under $100 and not worth my time.)

Best Interest Rates on Cash: Bank Accounts, Treasury Bills, Money Markets, ETFs – July 2026

Here’s my monthly survey of the best interest rates on cash as of July 2026, roughly sorted from shortest to longest maturities. Banks and brokerages love taking advantage of idle cash, and you can often earn more interest while keeping the same level of safety by moving to another FDIC-insured bank or NCUA-insured credit union. Check out my Ultimate Rate-Chaser Calculator to see how much extra interest you could earn from switching. Rates listed are available to everyone nationwide. Rates checked as of 7/1/26.

TL;DR: Savings account interest rates dropped slightly overall. You can get 4.4% APY if you accept certain hoops/restrictions, but most are under 4% now. Short-term T-Bill rates ~3.7%. Top 5-year CD rates are ~4.1% APY, while the 5-year Treasury rate is also ~4.1%.

High-yield savings accounts*
Since the huge megabanks still pay essentially zero interest, everyone should at least have a separate, no-fee online savings account to piggy-back onto your existing checking account. The interest rates on savings accounts can drop at any time, so I list the top rates as well as competitive rates from banks with a history of competitive rates and solid user experience. Some banks will bait you with a temporary top rate and then lower the rates in the hopes that you are too lazy to leave.

  • The top saving rate at the moment: Pibank at 4.40% APY (no min), but they have some weird restrictions; you can only use wire/Plaid to deposit and wire transfers to withdraw funds?! Elevault (no min) is at 4.34% APY, a division of Southern Bancorp Bank.
  • SoFi Bank is at 3.10% APY (new customers can get up to $475 in bonuses with qualifying direct deposit. You must maintain a direct deposit of any amount (even $1) each month for the higher ongoing APY. SoFi has historically competitive rates and full banking features.
  • Here is a limited survey of high-yield savings accounts. They aren’t the top rates, but a group that have historically kept it relatively competitive such that I like to track their history. This month they start at 3.00% APY on up.

Short-term guaranteed rates (1 year and under)
A common question is what to do with a big pile of cash that you’re waiting to deploy shortly (plan to buy a house soon, just sold your house, just sold your business, legal settlement, inheritance). My usual advice is to keep things simple and take your time. If not a savings account, then put it in a flexible short-term CD under the FDIC limits until you have a plan.

  • No Penalty CDs offer a fixed interest rate that can never go down, but you can still take out your money (once) without any fees if you want to use it elsewhere. Marcus has a 13-month No Penalty CD at 3.80% APY ($500 minimum deposit). Farmer’s Insurance FCU has a 9-month No Penalty CD at 4.00% APY ($1,000 minimum deposit). USALLIANCE Financial CU has a 11-month No Penalty CD at 3.85% APY ($500 minimum deposit).
  • E-Trade Bank has a 12-month CD at 4.10% APY (no minimum deposit). Early withdrawal penalty is 90 days of interest.
  • Farmer’s Insurance FCU has a 12-month CD at 4.00% APY with new money required. $1,000 minimum to open. Early withdrawal penalty is 90 days of interest.

Money market mutual funds
Many brokerage firms that pay out very little interest on their default cash sweep funds (and keep the difference for themselves). Note: Money market mutual funds are highly-regulated, but ultimately not FDIC-insured, so I would still stick with highly reputable firms.

  • Vanguard Federal Money Market Fund (VMFXX) is the default sweep option for Vanguard brokerage accounts, which has a 7-day SEC yield of 3.58% (changes daily, but also works out to a compound yield of 3.64%, which is better for comparing against APY). Odds are this is much higher than your own broker’s default cash sweep interest rate.
  • Vanguard Treasury Money Market Fund (VUSXX) is an alternative money market fund which you must manually purchase, but the interest will be mostly (100% for 2025 tax year) exempt from state and local income taxes because it comes from qualifying US government obligations. Current 7-day SEC yield of 3.63% (compound yield of 3.69%).

Treasury Bills and Ultra-short Treasury ETFs
Another option is to buy individual Treasury bills which come in a variety of maturities from 4-weeks to 52-weeks and are fully backed by the US government. You can also invest in ETFs that hold a rotating basket of short-term Treasury Bills for you, while charging a small management fee for doing so. T-bill interest is exempt from state and local income taxes, which can make a significant difference in your effective yield.

  • You can build your own T-Bill ladder at TreasuryDirect.gov or via a brokerage account with a bond desk like Vanguard and Fidelity. Here are the current Treasury Bill rates. As of 7/1/26, a new 4-week T-Bill had the equivalent of 3.63% annualized interest and a 52-week T-Bill had the equivalent of 3.98% annualized interest.
  • The iShares 0-3 Month Treasury Bond ETF (SGOV) has a 3.54% 30-day SEC yield (0.09% expense ratio) and effective duration of 0.10 years. The Vanguard 0-3 Month Treasury Bill ETF (VBIL) has a 3.57% 30-day SEC yield (0.06% expense ratio) and effective duration of 0.10 years.

US Savings Bonds
Series I Savings Bonds offer rates that are linked to inflation and backed by the US government. You must hold them for at least a year. If you redeem them within 5 years there is a penalty of the last 3 months of interest. The annual purchase limit for electronic I bonds is $10,000 per Social Security Number, available online at TreasuryDirect.gov.

  • “I Bonds” bought between May 2026 and October 2026 will earn a 4.26% rate for the first six months. The rate of the subsequent 6-month period will be based on inflation again. More on Savings Bonds here.
  • In mid-October 2026, the CPI will be announced and you will have a short period where you will have a very close estimate of the rate for the next 12 months. I will post another update at that time.

Rewards checking accounts
These unique checking accounts pay above-average interest rates, but with unique risks. You have to jump through certain hoops which usually involve 10+ debit card purchases each cycle, a certain number of ACH/direct deposits, and/or a certain number of logins per month. If you make a mistake (or they judge that you did) you risk earning zero interest for that month. Some folks don’t mind the extra work and attention required, while others would rather not bother. Rates can also drop suddenly, leaving a “bait-and-switch” feeling.

  • La Capitol Federal Credit Union pays 6.50% APY on up to $10,000 if you make 15 debit card purchases of at least $5 each per statement cycle. Anyone can join this credit union via partner organization, Louisiana Association for Personal Financial Achievement ($20).
  • OnPath Federal Credit Union (my review) pays 6.00% APY on up to $10,000 if you make 15 debit card purchases, opt into online statements, and login to online or mobile banking once per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization. You can also get a $150 Visa Reward card when you open a new account and make qualifying transactions.
  • Genisys Credit Union pays 6.75% APY on up to $7,500 if you make 10 debit card purchases of $5+ each per statement cycle, and opt into online statements. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Oklahoma Central Credit Union pays 6.00% APY on up to $10,000 if you make 15 debit card purchases (non-ATM) per statement cycle. Anyone can join this credit union if they are “affiliated with another credit union”.
  • First Southern Bank pays 5.50% APY on up to $25,000 if you make at least 15 debit card purchases, 1 ACH credit or payment transaction, and enroll in online statements.
  • Credit Union of New Jersey pays 5.50% APY on up to $20,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit, online bill payment, or automatic payment (ACH) per statement cycle. Anyone can join this credit union via $5 membership fee to join partner organization.
  • Andrews Federal Credit Union pays 5.25% APY on up to $25,000 if you make 15 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization.
  • Capitol Credit Union pays 6.00% APY on up to $15,000 if you make 12 debit card purchases, opt into online statements, and make at least 1 direct deposit or ACH transaction per statement cycle. Anyone can join this credit union via partner organization ($5 to Wild Basin Wilderness).
  • Find a locally-restricted rewards checking account at DepositAccounts.

Certificates of deposit (greater than 1 year)
CDs offer higher rates, but come with an early withdrawal penalty. By finding a bank CD with a reasonable early withdrawal penalty, you can enjoy higher rates but maintain access in a true emergency. Alternatively, consider building a CD ladder of different maturity lengths (ex. 1/2/3/4/5-years) such that you have access to part of the ladder each year, but your blended interest rate is higher than a savings account. When one CD matures, use that money to buy another 5-year CD to keep the ladder going. Some CDs also offer “add-ons” where you can deposit more funds if rates drop.

  • NASA Federal Credit Union has a 5-year certificate at 4.28% APY ($1,000 minimum), 4-year at 4.20% APY, 3-year at 4.15% APY, 2-year at 4.10% APY, and 1-year at 4.05% APY. Early withdrawal penalty for the 5-year is 365 days of interest. Anyone nationwide can join via a complimentary membership to the National Space Society (NSS).
  • Advancial Federal Credit Union has has a 5-year certificates at 4.14%/4.24%/4.34% APY APY based on either a $1,000/$25,000/$50,000 opening balance. Early withdrawal penalty for the 5-year is 365 days of interest. Anyone nationwide should be able to join via membership with partner organization US Dog Agility Association, but I would call to verify first.
  • Mountain America Credit Union (MACU) has a 5-year certificate at 4.15% APY ($500 minimum), 4-year at 4.09% APY, 3-year at 4.09% APY, 2-year at 4.30% APY, and 1-year at 4.00% APY. Early withdrawal penalty for the 4-year and 5-year is 365 days of interest. Anyone can join this credit union via partner organization American Consumer Council (use promo code “consumer” when joining).
  • You can buy certificates of deposit via the bond desks of Vanguard and Fidelity. You may need an account to see the rates. These “brokered CDs” offer FDIC insurance and easy laddering, but they don’t come with predictable early withdrawal penalties. Right now, I see a 5-year non-callable brokered CD at 4.40% APY (callable: no, call protection: yes). Be warned that both Vanguard and Fidelity will list higher rates from callable CDs, which importantly means they can (and will!) call back your CD if rates drop significantly later.

Longer-term Instruments
I’d use these with caution due to increased interest rate risk (tbh, I don’t use them at all), but I still track them to see the rest of the current yield curve.

  • Willing to lock up your money for 10 years? You can buy long-term certificates of deposit via the bond desks of Vanguard and Fidelity. These “brokered CDs” offer FDIC insurance, but they don’t come with predictable early withdrawal penalties. You might find something that pays more than your other brokerage cash and Treasury options. Right now, I see a 10-year CDs at [none available] APY (non-callable) vs. 4.47% for a 10-year Treasury. Watch out for higher rates from callable CDs where they can call your CD back if interest rates drop.

All rates were checked as of 7/1/26.

* I no longer recommend fintech companies due to the possibility of significant loss due to poor recordkeeping and the lack of government protection in such scenarios. The point of cash is absolute safety of principal.

Photo by Giorgio Trovato on Unsplash

CIT Bank Review: 11-Month No-Penalty CD at 3.90% APY, Platinum Savings 3.75% APY

Rate hike for No-Penalty CD. CIT Bank (not to be confused with Citi Bank) is an online-only bank that has a multi-year history of competitive rates, although they do like to start up new product lines while keeping low rates on their older product lines. Here are the current noteworthy accounts:

  • 11-Month No-Penalty CD at 3.90% APY***. $1,000 minimum balance and no monthly fees.
  • Platinum Savings Account at 3.75% APY* if you maintain a $5,000 daily balance or higher. 0.25% APY if your daily balance is under $5,000. No monthly fees. If you have any other savings accounts at CIT and can meet the minimum balance, you should consider moving funds over to this account. You can also open this new account without having to open another bank or credit union account.
  • Savings Connect Account at 3.65% APY** if you open with $100. No minimum balance and no monthly fees.
  • Member FDIC.

Check out my rate chaser calculator to see if it makes sense for you to move money over.

New customer? Opening process overview. Here’s my review of the opening process if you are a new customer.

  • The application process was completely online. You provide the usual personal information.
  • You must submit to a credit check, but in my experience it was a “soft” pull which did not harm my credit. None of my various credit monitoring services showed it was a hard pull.
  • You may fund via (1) electronic ACH transfer, (2) wire transfer, (3) mobile check deposit via CIT Bank mobile app (iOS and Android), and (4) mailing in a paper check. There was no option for credit card funding. I picked online ACH funding and you need to provide routing and account numbers, followed by manual verification via micro-deposits after a day or two. There was no instant linking option via login information.

After deposit verification, then your funding will go through.

You have successfully verified your external account. Please allow up to 5 business days for your funds to appear in your CIT Bank account.
No further action is required for this account. Thank you!

Existing savings or money market customer? Check your rate. If you already have an existing High Yield Savings account, it may remain at a lower interest rate than the currently-promoted accounts. If so, take a minute and upgrade yourself to the better interest rate.

Bottom line. CIT Bank is a lean bank offering targeted products for folks looking to get higher interest rates on their cash balances. They don’t maintain physical bank branches or fancy apps. However, I have been pleasantly satisfied with their customer service on my accounts with them.

* Here are the disclosures for the Platinum Savings:

Platinum Savings is a tiered interest rate account. Interest is paid on the entire account balance based on the interest rate and APY in effect that day for the balance tier associated with the end-of-day account balance. APYs — Annual Percentage Yields are accurate as of July 1, 2026: 0.25% APY on balances of $0.01 to $4,999.99; 3.75% APY on balances of $5,000.00 or more. Interest Rates for the Platinum Savings account are variable and may change at any time without notice. The minimum to open a Platinum Savings account is $100.

** Here are the disclosures for the Savings Connect:

APY — Annual Percentage Yield is accurate as of July 1, 2026. Interest Rates for the Savings Connect Account are variable and may change at any time without notice. The minimum to open a Savings Connect account is $100. Fees could reduce earnings on the account.

For complete list of account details and fees, see the CIT Bank Personal Account disclosures.

*** Here is the fine print (disclosures) for the 11-month No-Penalty CD:

APY — Annual Percentage Yield is accurate as of July 1, 2026. $1,000
minimum to open the account.

With a No-Penalty CD, you may withdraw the total balance and interest earned, without penalty, beginning 7 days after funds have been received for your CD. No withdrawals are permitted during the first 6 days following the receipt of funds.

Marriott Bonvoy Boundless Card Review: 125,000 Points + Free Night Award + $100 in Airline Credits

Updated offer. The Marriott Bonvoy Boundless credit card is one of the co-branded rewards card for Marriott hotels (which includes The Ritz-Carlton, St. Regis, JW Marriott, W Hotels, Sheraton, Westin, Marriott, Renaissance, Courtyard, Residence Inn, and Fairfield brands). Right now, there is a special offer that is higher than the standard offer. Here are the highlights:

  • 125,000 Bonus Points + 1 Free Night Award after spending $3,000 on eligible purchases within 3 months of account opening Free Night award worth up to 50k points; you are also now allowed to top off the award nights with up to 25,000 of your own points, in order to reach a 75,000 point award night. Certain hotels have resort fees.
  • Special Offer: Get up to $100 in statement credits after spending $500 on eligible airline purchases. The credit are split up semi-annually. Spend $250 between July 1 and Dec. 31, 2026 to earn a $50 statement credit. Earn another $50 statement credit after spending $250 or more between Jan. 1 and June 30, 2027.
  • Earn 3X points per $1 on the first $6,000 spent in combined purchases each year on grocery stores, gas stations, and dining.
  • 1 Free Night Award (valued up to 35,000 points) every year after account anniversary.
  • 1 Elite Night Credit towards Elite Status for every $5,000 you spend.
  • Earn up to 17X total points per $1 spent at over 7,000 hotels participating in Marriott Bonvoy(R) with the Marriott Bonvoy Boundless(R) Card.
  • 2X points for every $1 spent on all other purchases.
  • Automatic Silver Elite Status each account anniversary year. Gold Status when you spend $35,000 on purchases each account year.
  • 15 Elite Night Credits each calendar year.
  • No Foreign Transaction Fees.
  • $95 annual fee.

Keep in mind the following:

This credit card is not available to you if (1) you currently have any of the following cards or (2) you received a new cardmember bonus for any of the following cards within the last 24 months: Marriott Bonvoy® Premier credit card, Marriott Rewards® Premier credit card, Marriott Bonvoy Boundless® credit card, Marriott Rewards® Premier Plus credit card, Marriott Bonvoy Bold® credit card.

The new cardmember bonus is not available to you if (1) you currently have or had any of the following cards within the last 30 days: Marriott Bonvoy® American Express® Card, The Starwood Preferred Guest® Credit Card from American Express; or if (2) you applied and were approved for any of the following cards within the last 90 days or (3) received a new cardmember bonus or upgrade bonus for any of the following cards within the last 24 months: Marriott Bonvoy Business® American Express® Card, Starwood Preferred Guest® Business Credit Card from American Express, Marriott Bonvoy Brilliant® American Express® Card, Starwood Preferred Guest® American Express Luxury Card, Marriott Bonvoy Bevy™ American Express® Card.

What is a reasonable estimate for the value of a Marriott Bonvoy point? Since 2022, Marriott no longer has a fixed hotel category chart for booking points. You can still use these points at either long-time Marriott brands (Ritz-Carlton, Renaissance Hotels, Courtyard, Residence Inn, Springhill Suites, Fairfield Inn & Suites) or former Starwood brands (Westin, Sheraton, The Luxury Collection, Four Points by Sheraton, W Hotels, St. Regis, Le Méridien, Aloft), but now it is “dynamic” awards where the points required are more linked to the actual cash cost than before.

Based on multiple real-world searches of redeemable properties, I choose to use a conservative estimate of 0.70 cents per Bonvoy point. Other estimates that I’ve seen are 0.8 cents per point. That means 50,000 Bonvoy points = estimated $350 redeemable value. Remember to compare the full price of the hotel price with all taxes, as that is what you would have to pay instead of just points. With the flexibility of points, you could book a week stay at a modest hotel or a couple nights at a luxury resort.

You can use the Marriott free night search tool to price out some sample hotels for yourself.

NEW: Certificates can be combined with up to 25,000 points for nicer hotels. Marriott now allows you to supplement your free night certificates with up to 25,000 points of your own. In other words, if your certificate is worth 50,000 points, the maximum hotel value you can redeem for is 75,000 points after adding 25,000 points of your own. Here are details on the Free Night Award Top Off option.

Bonvoy Points can also be transferred to airline miles with a bonus. You can convert your Bonvoy points to miles at 39 participating airlines. The standard ratio with most programs is 3:1 (60,000 Bonvoy: 20,000 airlines) miles. Most programs will add on a bonus 5,000 miles for every 60,000 points you transfer to frequent flyer miles (does not apply to American Airlines AAdvantage, Avianca LifeMiles, Delta SkyMiles and Korean Air SKYPASS.) If you’re a United MileagePlus® member, you’ll get 10,000 bonus miles for every 60,000 points you transfer. More information here.

Finally, Marriott points are also convertible to gift cards, but it takes 60,000 points to redeem for a $200 gift card for Marriott or retailers like Best Buy, Home Depot, or Nordstrom. That ratio isn’t all that great, so you’ll definitely get the most value via hotel night redemptions or airline miles transfer.

No annual fee alternative. Look at the Marriott Bonvoy Bold card, which also offers bonus points and some (lesser) perks, but with no annual fee.

Bottom line. The Marriott Bonvoy Boundless credit card is currently offering a special offer for new cardholders. As with all hotel cards, the value is dependent on your unique travel preferences. If you stay at Marriott properties regularly, the free night award every year should easily cover the annual fee.

Amazon Prime Day 2026: Live Deals (Apple, LEGO, YETI, Away, Darn Tough, Osprey), Gift Cards, Free Trials, Shop w/ Points

Amazon Prime Days 2026 is now over, but it ran from June 23-26, 2026. Look for sales on the brands you like such as Apple, LEGO, Eero WiFi, Away luggage, Darn Tough socks, Osprey backpacks, YETI. Discounted gift cards, $5 pizzas, and $200 bonus on Amazon Prime card now live. I always look out for reset points credits and extended free trials to try out again. As usual, I recommend checking for discounts on the things you already like to buy but rarely go on sale, like Darn Tough socks. Check your “Buy Again” past purchases here. I’ve listed a few of my favorite things below as well.

(Note: If you are reading this in an email/RSS reader, unfortunately I am not allowed to include any Amazon affiliate links in e-mails, so they have been removed. Please click here to view the links.)

As the name suggests, most deals require a Prime membership. New members can sign up for a 30-day free trial. Amazon Prime for Students (age 18-24) has a 7-day trial for 99 cents and $7.49/month after that (50% off regular). If you’ve already done the trial, you can simply buy a single month of Prime for $14.99 ($6.99 with SNAP, EBT or Medicaid card).

Deals and Offers

Amazon Free Trials

“Shop with Points” Promos (Check again if reset/targeted)

Random Favorite Things & Recent Discoveries

  • Darn Tough wool socks. These live up to the hype and are my favorite brand with their high quality and lifetime warranty, but they can be pricey so I still try to buy them when they are on sale during Prime Day. #buyitforlife
  • Osprey bags and backpacks. Another high-quality brand with a lifetime warranty. I just sent in a claim on got replacement zipper pulls for a 10+ year-old Osprey bag. #buyitforlife
  • Bose Headphones – I have two, the QC15 corded from several years back, and a QC35 from a few years back. Both still work great, I keep one at my desk and the other in my travel bag. I’ve even gone through several replacement ear cushions, but the original Bose branded ones are still the best.
  • Vitamix blenders – I bought one and it’s also probably on Year 10 now. Honestly, I still don’t know if you need a $300+ blender, but it’s a solid blender.
  • Amazon Eero 6E mesh WiFi router system 3-pack (sale). If you have WiFi coverage issues and haven’t upgraded your router recently, I do recommend an upgrade. It just makes WiFi something you don’t worry about anymore. No more dead spots. This “6E” model supports speeds up to 2.5Gbps and up to 6,000 sf, while the cheaper “6” version supports up to 500 Mbps and 4,500 sf.
  • COSORI Air Fryer. We still use our air fryer nearly every day; heats things up like a microwave, except it keeps them crispy instead of soggy. Easy to clean in dishwasher.
  • Coway Airmega AP-1512HH True HEPA Air Purifier. I have two of these air purifiers, one in each of the kids’ rooms. I think they are over 5 years old now and still going fine. Simple design, reliable, and easy to change filters. I use these cheaper VEVA brand replacement filters that are still of good quality.
  • Bosch ICON windshield wipers. These are the most expensive, but they are also the best and longest-lasting in my experience. No lifetime warranty or anything crazy like that, but I no longer mess with the rest.
  • Tiptree Passion Fruit Curd. Delicious on so many things, their lemon curd is excellent as well but the passionfruit (aka “lilikoi butter”) flavor is one of those things that I can only find easily on Amazon.

Wyndham Rewards Earner Cards: Up to 120,000 Bonus Points (Up to 15+ Free Nights)

(Update: Wyndham just announced some changes to their rewards program effective 9/15/2026 – notably a new 45,000 point top tier that was previously only 30,000 points – likely indicates that many of their properties may cost a lot more than before.)

Cards refreshed. The Wyndham Rewards Earner credit cards have a refreshed line-up with some limited-time sign-up offers as well. However, to get the full sign-up bonus you now need to spend a certain amount at Wyndham Hotels. Free nights start at 7,500 points and go as high as 30,000 points. Reminder that as of 2026, Vacasa home rentals are no longer a partner of Wyndham Rewards.

Wyndham Rewards Earner Card highlights:

  • Up to 75,000 total bonus points. 30,000 bonus points after spending $1,000 on purchases in the first 90 days and also earn 45,000 bonus points after spending $500 at Hotels by Wyndham in the first 180 days.
  • 5X points per $1 spent on eligible purchases made at Hotels by Wyndham, including hotels through Wyndham Travel Bundles.
  • 3X points per $1 spent on eligible Vacation Club, dining and grocery store purchases (excluding Target® and Walmart®), as well as eligible gas and EV charging purchases.
  • 1 point per $1 spent on all other purchases (excluding Vacation Club down payments).
  • Automatic upgrade to Wyndham Rewards Gold status.
  • 10% fewer Wyndham Rewards points required for go free® awards.
  • 7,500 bonus points each anniversary year if you spend $15,000 on eligible purchases.
  • No annual fee.

Wyndham Rewards Earner Plus Card highlights:

  • Up to 100,000 total bonus points. Earn 45,000 bonus points after spending $1,000 on purchases in the first 90 days and also earn 55,000 bonus points after spending $500 at Hotels by Wyndham in the first 180 days.
  • 6X points per $1 spent on eligible purchases made at Hotels by Wyndham, including hotels through Wyndham Travel Bundles.
  • 4X points per $1 spent on eligible Vacation Club, dining and grocery store purchases (excluding Target® and Walmart®), as well as eligible gas and EV charging purchases.
  • 1X point per $1 spent on all other purchases (excluding Vacation Club down payments).
  • Automatic upgrade to Wyndham Rewards Platinum status.
  • 10% fewer Wyndham Rewards points required for go free® awards.
  • 15,000 bonus points each anniversary year after payment of your annual fee.
  • $50 Meal Delivery Credit. Enjoy up to $25 in statement credits back every 6 months on eligible meal delivery purchases when you pay with your card—up to $50 each calendar year.
  • $95 annual fee.

Wyndham Rewards Earner Premier Card highlights:

  • Up to 120,000 total bonus points. Earn 90,000 bonus points after spending $6,000 on purchases and paying the annual fee in full, both within the first 120 days, and also earn 30,000 bonus points after spending $750 at Hotels by Wyndham in the first 180 days.
  • 8X points per $1 spent on eligible purchases made at Hotels by Wyndham, including hotels through Wyndham Travel Bundles.
  • 4X points per $1 spent on eligible Vacation Club, dining and grocery store purchases (excluding Target® and Walmart®), as well as eligible gas and EV charging purchases.
  • 1X point per $1 spent on all other purchases (excluding Vacation Club down payments).
  • Automatic upgrade to Wyndham Rewards Diamond status.
  • 10% fewer Wyndham Rewards points required for go free® awards.
  • 15,000 bonus points each anniversary year after annual fee renewal.
  • $100 Wyndham Hotels annual credit. You are eligible to receive a single statement credit of $100 back after spending $100 or more in the aggregate at Wyndham® hotels, Wyndham Grand® hotels, Dolce Hotels and Resorts® by Wyndham, Trademark Collection® by Wyndham and/or Registry Collection Hotels® each calendar year.
  • $65 Wholesale Club annual credit. Receive a $65 statement credit back each calendar year after making qualifying wholesale club membership purchases with your card.
  • $120 in Meal Delivery credits annually. Enjoy up to $10 in statement credits back each month–up to $120 each calendar year–after making qualifying meal delivery purchases with your card.
  • $100 in Streaming annual credits. Receive statement credits on qualifying streaming subscriptions—stream more of what you love.
  • $120 TSA PreCheck/Global Entry credit, once every 4 years.
  • Free Wyndham Insider membership ($95/year value).
  • $395 annual fee.

Wyndham hotels have a relatively simple system that charges 7,500, 15,000, or 30,000 points for a “Go Free” award hotel night with no blackout dates (as long as a standard room is available for cash, you can book it with points). You can also redeem toward a discounted “Go Fast” cash and points rate. Resort fees may apply and cannot be paid with points. Note that when you have one of these credit cards, you get a 10% discount, so for example the 15,000 points tier would be actually be reduced down to 13,500 points.

Wyndham points expiration – Important!

  • Wyndham Rewards points will expire if you have no activity on your account for a period of 18 months.
  • In addition, all Wyndham Rewards points expire 4 years after being earned — regardless of account activity.
  • NEW: The only exception to this is if you are a Wyndham Rewards Earner® Premier Card Cardmember.

From the official Terms & Conditions:

Except as may otherwise be required under applicable law or set forth herein with respect to Wyndham Rewards Earner® Premier Cardmembers, Wyndham Rewards points expire four (4) years after the date on which the applicable points are posted to the Member’s account (the “Four Year Rule”), unless the points are forfeited or cancelled earlier due to membership inactivity (as more particularly described below), or otherwise in accordance with these Terms and Conditions. For clarity, posting dates vary based on the type of activity for which they were earned. Except as may otherwise be set forth herein with respect to Wyndham Rewards Earner® Premier Cardmembers, all accrued points in a Member’s Wyndham Rewards account may be cancelled or forfeited if the Member has no Account Activity (as defined below) for a period of approximately, but never less than, eighteen (18) consecutive months. For purposes of these Terms and Conditions, “Account Activity” means any (i) point earning, and (ii) redemption or transfer activity involving a change in the Member’s Wyndham Rewards point balance, in each case, conducted in accordance with these Terms and Conditions.

Without limiting any other section of these Terms and Conditions, points earned by a Wyndham Rewards Earner® Premier Card Cardmember do not expire under this Section I(14) as long as Cardmember’s account is open and in good standing.

For example, earning points via this credit card will only reset the 18-month inactivity clock. Look for the exact date in your online account page. Again, there is a new exception for the top-tier Premier credit card.

Wyndham Rewards includes over 9,000 hotels worldwide – from Days Inn motels to Wyndham Grand hotels. You can use this link to filter locations easily by country, state, and/or point level. Participating hotel chains include:

  • AmericInn by Wyndham®
  • Dolce Hotels and Resorts® by Wyndham
  • Hawthorn Suites by Wyndham®
  • Howard Johnson by Wyndham®
  • La Quinta by Wyndham®
  • Ramada by Wyndham®
  • Days Inn by Wyndham®
  • Super 8 by Wyndham®
  • Travelodge by Wyndham®
  • Wingate by Wyndham®
  • Wyndham Grand®
  • Wyndham Hotels and Resorts®
  • Wyndham Garden®

I don’t like that the sign-up bonuses now include a requirement for a paid stay at a Wyndham hotel first, so I will probably be skipping this card.

Ink Business Cash Card: $1,000 Cash Bonus w/ No Annual Fee (Limited-Time Offer)

The Ink Business Cash Card has an all-time high sign-up bonus offering $1,000 total cash bonus (or 100,000 Ultimate Rewards points) for new cardholders that meet the spending requirements, along with 5%/2% cash back on select small business categories, all with no annual fee. Here are the details:

  • $1,000 bonus. Earn $1,000 cash back after you spend $8,000 on purchases in the first 4 months after account opening. This matches the all-time high; previous offer was $750.
  • 5% cash back (or 5X Ultimate Rewards per dollar) on the first $25,000 spent in combined purchases at office supply stores and on internet, cable and phone services each account anniversary year.
  • 2% cash back (or 2X Ultimate Rewards per dollar) on the first $25,000 spent in combined purchases at gas stations and restaurants each account anniversary year.
  • 1% cash back on all other card purchases with no limit to the amount you can earn.
  • Free additional cards for employees.
  • No annual fee.

Ultimate Rewards points. The cash sign-up bonus actually comes in the form of Ultimate Rewards points at 1 point = 1 cent in cash. 100,000 points = $1,000 cash.

You can pool all of your Ultimate Rewards points from other Chase cards together (even with your spouse in the same household) with cards like the Chase Sapphire Preferred to take advantage of all the excellent transfer options to programs like Hyatt hotels and United Airlines.

Leveraging the 5% back bonus categories. Putting all of your small business cell phone, landline, and internet bills on the card and getting 5% back is pretty handy. For example, even just $200 a month x 12 months x 5% back is $120 back a year without changing your spending habits. Now let’s take the office supply store category and the fact that you can buy gifts cards to Amazon.com and other retailers at such office supply stores like Staples and OfficeMax… now you can effectively discount many of your other purchasing needs by 5% as well. Putting those purchases on such gift cards upfront can also help you meet the spending requirement for the bonus.

Many people aren’t aware of the fact that they can apply for business credit cards, even if they are not a corporation or LLC. The business type is called a sole proprietorship, and these days many people are full-time or part-time consultants, freelancers, eBay/Amazon/Etsy sellers, or other one-person business owners. This is the simplest business entity, but it is fully legit and recognized by the IRS. On a business credit card application, you should use your own legal name as the business name, and your Social Security Number as the Tax ID.

Note that Chase has an unofficial rule that they will automatically deny approval on new credit cards if you have 5 or more new credit cards from any issuer on your credit report within the past 2 years (aka the 5/24 rule). This rule is designed to discourage folks that apply for high numbers of sign-up bonuses. This rule applies on a per-person basis, so in our household one applies to Chase while the other applies at other card issuers.

Bottom line. The Ink Business Cash Card has a large sign-up bonus and ongoing features of 5X/2X categories with no annual fee. This card is best if you have significant expenses in the special 5% and 2% categories above. If you have certain other Chase credit cards, you can transfer Ultimate Rewards points over to those cards and increase your value.

Planet Fitness High School Summer Pass 2026: Free Gym Membership For Teens 14-19

Offer is back for Summer 2026. Planet Fitness is running the High School Summer Pass again in 2026, which is a free gym membership for teens ages 14-19 to work out at any of its more than 2,500+ locations throughout the US and Canada. Valid Monday, June 1 through Saturday, August 31. Participants must work out at the “home” location they sign up at and are not permitted to use other locations. Here is a gym locator.

This year, you also get a code for 20% off Gymshark clothing, sent to your e-mail 2-3 days after signing up. Parents can also get one free Day Pass.

Participants can work out for FREE at participating Planet Fitness locations (U.S. and Canada, excluding Puerto Rico) starting Monday, June 1 through Monday, August 31. Participants must work out at the location they sign up at and are not permitted to use other locations.

Chase Sapphire Preferred June 2026 Changes, Both Positive and Negative

The Chase Sapphire Preferred Card has been a big hit for Chase since it came out, and they recently announced (press release) several positive changes that will come into effect on June 15th, 2026 for both new and existing applicants and some negative changes (notable Hyatt points transfers) that will be grandfathered for existing cardholders until October 1st, 2026.

Additions / Positive Changes

  • $100 Chase Travel Hotel Credit each account anniversary (increased from $50).
  • 3X points on gas and EV charging.
  • 3X points on vacation rentals (Airbnb, Vrbo, Plum Guide, HomeAway, Homestay.com and Vacasa).
  • $120 credit toward Global Entry, TSA PreCheck or NEXUS every four years.
  • “Emergency Evacuation and Transportation coverage” added to their existing list of travel protections.
  • One-time 12-month Apple TV subscription for free when activated by December 31, 2026.

Removals / Negative Changes

  • Hyatt points transfers devalued by 25%. Before, Ultimate Rewards points transferred to Hyatt at a 1:1 ratio for Sapphire Preferred and Ink Business Preferred cards. Now, it is a 4:3 ratio, which is the same as a 1:0.75 ratio. (Chase Sapphire *Reserve* cardholders will keep the 1:1 ratio.) So every 1,000 Ultimate Rewards points only becomes 750 Hyatt points now, instead of the previous 1,000.

    “Sapphire Preferred and Ink Business Preferred cardmembers’ Ultimate Rewards points will transfer to World of Hyatt at a rate of 4:3. For Sapphire Preferred cardmembers, this is effective immediately for new cardmembers who apply on or after June 15, 2026, and effective October 1, 2026, for cardmembers who applied prior to June 15, 2026. For Ink Business Preferred cardmembers, this is effective October 1, 2026, for existing cardmembers and for new cardmembers who apply on or after October 1, 2026.”

  • 10% anniversary points bonus removed. “The 10% Anniversary Bonus Benefit is being discontinued, effective immediately for cardmembers who apply on or after June 15, 2026. For cardmembers who applied prior to June 15, 2026, eligible purchases made through October 1, 2026, will continue to earn the 10% bonus, which will be awarded by January 31, 2027.”

No change

  • $95 annual fee.
  • 5X points on Chase Travel portal purchases (flights, hotels, car rentals, etc).
  • 2X points on all other travel worldwide.
  • 3X points on dining worldwide, including takeout and eligible delivery services
  • 3X points on select streaming services (Apple Music, Apple TV, Disney+, ESPN+, Fubo TV, Max, Hulu, Netflix, Pandora, Paramount+, Peacock, Showtime, SiriusXM, Sling, Spotify, YouTube Premium, YouTube TV and Vudu)
  • 3X points on online grocery purchases (excludes Target, Walmart, and wholesale clubs).
  • 5X points on Lyft rides through September 30, 2027
  • 5X total points on eligible Peloton equipment and accessory purchases over $150 through December 31, 2027
  • 1X points on all other purchases

The Hyatt points transfer change is a double-whammy. Ultimate Rewards points to Hyatt transfers used to be a relatively hassle-free way to easily get over 2 cents per point value. But not only has Hyatt devalued their own points a lot recently (most of their hotels now cost more points to book), but now the transfer rate from Ultimate Rewards also dropped by 25% for this card. That nudges the value of an Ultimate Rewards points much closer to the basic sad value of 1 cent per point. Now it will take more work to find other transfer partners like a United Airlines redemption to get good value.

Even though these are “improvements” to the Sapphire Preferred, this actually shifts my personal preference a bit more to the Chase Sapphire Reserve, which has its own set of complications, but at least I can still get full 1:1 value to Hyatt points with my large bank of points. You can also transfer your other points over to the Reserve from your other cards and household family members. Right now, I am still in the middle of my first year with the Chase Sapphire Reserve and trying to figure out what I’m really able to get out of all those annual credits. The sign-up bonus is also increased to 150,000 Ultimate Rewards points until 6/15.

Our household strategy in the past has been for at least one person to have the Chase Sapphire Preferred to keep our Ultimate Rewards balance going, sometimes transferring back and forth as needed, and then the other person might have the Reserve for a while.