Here’s a 2013 year-end update of our retirement portfolio, which includes employer 401(k) plans, self-employed retirement plans, Traditional and Roth IRAs, and taxable brokerage holdings. Cash reserves (emergency fund), college savings accounts, experimental portfolios, and day-to-day cash balances are excluded. The purpose of this portfolio is to eventually create enough income on its own to cover all daily expenses.
Target Asset Allocation
This has been mostly the same for over 6 years, although I did make some slight tweaks in my last June 2013 update.

I try to pick asset classes that are likely to provide a long-term return above inflation, as well as offer some historical tendencies to be less correlated to each other. I don’t hold commodities futures or gold because theoretically their prices should only match inflation. In addition, I am not confident in them enough to know that I will hold them through an extended period of underperformance (and if you don’t do that, there’s no point). 2013 turned out to be a tough year for both gold and commodities funds.
Our current ratio is about 70% stocks and 30% bonds within our investment strategy of buy, hold, and rebalance. With low expense ratios and low turnover, we minimize our costs in terms of paying fees, commissions, and taxes.
Actual Holdings
Here is our year-end asset allocation snapshot:

Stock Holdings (Ticker Symbol)
Vanguard Total Stock Market Fund (VTI, VTSMX, VTSAX)
Vanguard Total International Stock Market Fund (VXUS, VGTSX, VTIAX)
WisdomTree SmallCap Dividend ETF (DES)
WisdomTree Emerging Markets SmallCap Dividend ETF (DGS)
Vanguard REIT Index Fund (VNQ, VGSIX, VGSLX)
Bond Holdings
Vanguard Limited-Term Tax-Exempt Fund (VMLTX, VMLUX)
Vanguard High-Yield Tax-Exempt Fund (VWAHX, VWALX)
PIMCO Total Return Institutional* (PTTRX)
Stable Value Fund* (2.6% yield, net of fees)
iShares Barclays TIPS Bond ETF (TIP)
Individual TIPS securities
US Savings Bonds
The holdings haven’t changed through the latter half of this year, just some additional purchases of existing funds.
In terms of performance, in general stocks had a great year while bonds pretty much went nowhere or slightly down. I don’t expect everything to go up every year, not to mention my portfolio is bigger than I could have expected just a few years ago, so I can’t complain. Here are some 2013 YTD total returns for selected representative funds as of 12/27/13:
Stocks
Total US VTI +33%
Total International VXUS +14%
US Small Cap Value DES +37%
Emerging Market Small Cap Value DGS -5%
US REITs VNQ +3%
Bonds
Short-term Muni VMLUX +0.5%
Intermediate-term Muni VWALX -3%
Inflation-protected bonds -9%


 Our goal is to always have a full year of expenses in cash equivalents as our “emergency fund”. (This is not the same as a year of income. Our expenses are much lower than our income.) This is a cushion for a variety of potential events including job loss, health concerns, or other unplanned costs. It also allows us to take a more long-term view with our investment portfolio since we know we won’t have to touch it.
 I don’t think everyone should buy a house (or more accurately, take out a huge loan on a house), as it historically doesn’t necessarily work out to be a very good investment over short or even long periods. However, if you are geographically stable, I do think buying and eventually owning a house free and clear can be a solid component of an early retirement plan. My current forecast is to have our house paid off in
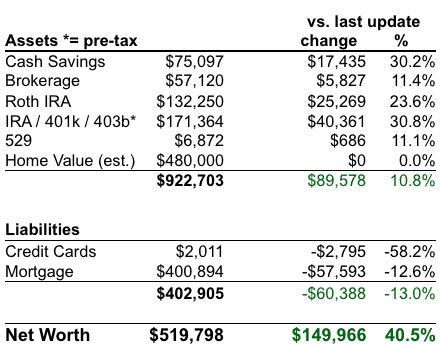
 The goal of my investment portfolio is allow withdrawals to support our needed expenses in “retirement”. Again, income and expenses are not the same thing. After mortgage payoff, I expect our required expenses to be less than 25% of our current income. I like to assume a simple 3% safe withdrawal rate, which means for every $100,000 saved, I can generate $3,000 a year of inflation-adjusted income for the rest of our lives. I used to assume 4%, but since our target “retirement” age is in our 40s and not 60s, I feel that 3% is better. Even 3% is not guaranteed, but again it does provide a quick estimate of progress. Here are recent portfolio updates:
 “I seek the admiration and respect of others.”
 “I like being the boss and giving orders.”
 “I find a higher calling in serving my religion/country/world.”
 “I love my job.”
 “I want be a good wife/husband/mother/father.”
 “I don’t take orders from anyone.”
 “I don’t question the status quo and like to follow others.”


 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)