Updated, including new bonus and tax warning. Fidelity Spire is Fidelity’s new mobile app, which adds fintech-y features and is separate from their main Fidelity app. You can link your external accounts, track balances, and set financial goals. (Fidelity acquired fintech startup eMoney in 2015, and is using that technology for account aggregation.) You can also link up “real” Fidelity accounts like their brokerage accounts and perform commission-free trades within the app.
New $100 Fidelity account bonus. If you open a new, eligible Fidelity account via the Spire app or fidelity.com/spire and maintain an automatic monthly deposit of $25+ for 6 months, you can get a $100 bonus. Hat tip to DoC.
- You must open via the Fidelitiy Spire app or specific link above, not anywhere else.
- Eligible accounts include The Fidelity Account®, Fidelity® Cash Management account, Fidelity Roth IRA, or a Fidelity traditional IRA.
- You must establish a monthly Fidelity Automatic Account Builder (FAAB) plan, an automated deposit feature, on your newly established account for at least $25. First deposit must be within 45 days of opening, and must come from an external, non-Fidelity source. The automatic monthly deposit must remain in effect for at least 6 months (or 6 monthly deposits of at least $25).
- Bonus limited to $100 per individual in 2021.
Fidelity doesn’t offer bonuses very often, so even though it is not that big, it’s still something if you were planning on opening an account anyway.
While not eligible for the bonus, they are also offering their new Fidelity Go robo-advisor service that automatically invests for you, with no minimum to start and the following fee structure:
- $10,000 or less: No advisory fee
- $10,000 to $49,999: Flat $3 a month
- $50,000 or more: 0.35% annually
The flat fee structure for assets under $50,000 is interesting. At $10,000 in assets, $36 dollars a year = 0.36% annually. At $49,999 in assets, $36 dollars a year = 0.07% annually.
In addition, the underlying mutual funds also offer zero expense ratios. Fidelity actually created a new line of mutual funds called Fidelity Flex Funds for their managed accounts, similar to their other passive and actively-managed mutual funds but with zero expense ratios. For example, there is a Fidelity Flex 500 Fund and a Fidelity Flex International Index fund. However, this special also comes with a drawback.
As with other roboadvisors, the portfolio they choose will be based on you filling out a relatively short online questionnaire. If you aren’t sure about the resulting asset allocation, I recommend going back and change your answers to see the effects. With Fidelity Go, you do not gain access to financial advice from a human advisor. However, you will still gain access to their phone/live chat customer service, which has traditionally been rated highly.
Warning: If you decide to move your money out of Fidelity Go in a taxable account, they will force you to sell all your proprietary Flex fund shares and potentially incur capital gains taxes. If you just owned regular ETFs or mutual funds, you should be able to export the shares “in-kind” without selling and maintain your cost basis. I know you can do this with Betterment and Wealthfront. Depending on how much your account grew, you could consider this a significant “exit fee”.
This is why I still prefer to DIY and construct a portfolio using “high-quality interchangeable parts” that I can keep forever. You can still use Fidelity as I think they are reputable firm with overall good customer service, but instead just buy something like Vanguard Total US Market ETF (VTI) or iShares Core Total US (ITOT).
With free trades now available nearly everywhere, the primary “cost” is the hassle of doing the trades yourself. This is why I recommend also looking at M1 Finance, as they will maintain your target asset allocation for free while still allowing your the ability to port out your investments at any time.


 The WSJ article

 Here’s my monthly roundup of the best interest rates on cash as of April 2021, roughly sorted from shortest to longest maturities. There are many lesser-known opportunities to improve your yield while keeping your principal “safe” (FDIC-insured or equivalent). Check out my
 This
 Although I’m still decades away from Social Security, I see a constant stream of articles about the “best” time to start taking benefits. Often, you are told to delay claiming until age 70, as you will receive a more valuable, inflation-adjusted, government-guaranteed payout for the rest of your life. But if you have a spouse, it may be better for one of them to claim as early as possible, at age 62. There are many calculators out there – here is one

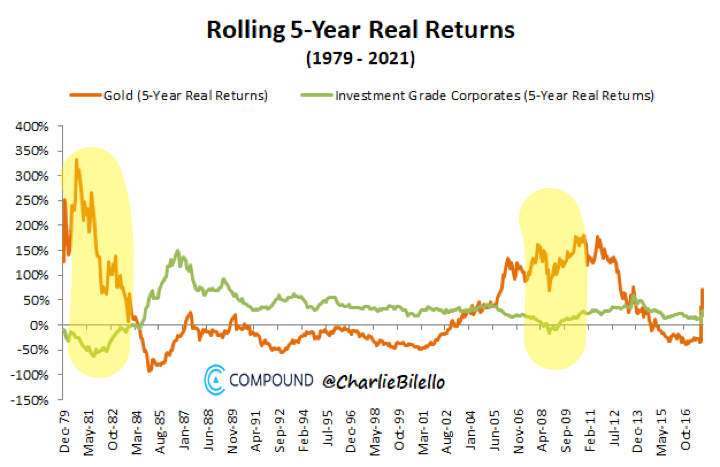
 Perhaps it is because I somehow ended up buying $5,000 in gold coins a couple weeks ago, but I’ve been doing some reading about gold again. The stock market is at higher and higher valuations, while the Fed promises that interest rates will stay low for a long time. The real yield on TIPS remains negative, meaning that it is highly unlikely that any high-quality investment-grade bonds will beat inflation over the next decade. Is there really no alternative?


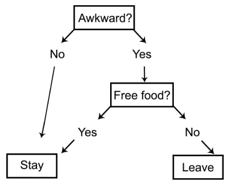 When creating financial statements, there are “generally accepted accounting principles” (GAAP) so that all companies follow the same standardized set of rules. After reading 100+ books on personal finance, you could also create what I would call “generally accepted personal finance principles” (GAPFP?), as organized into a

 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)