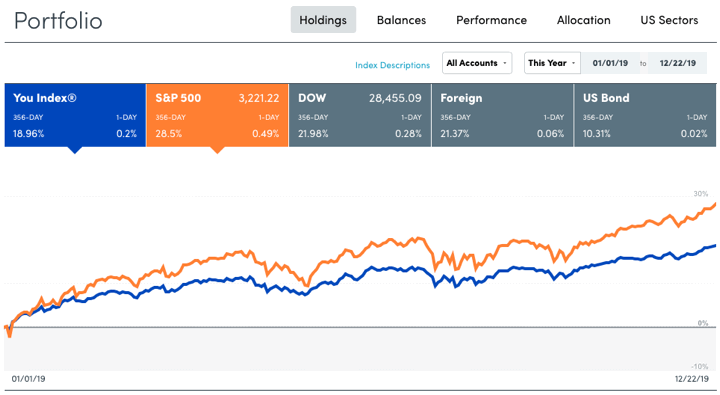
I used to add up my net worth every month (if not more frequently), but nowadays I limit myself to quarterly portfolio checks to coincide roughly with when my dividends arrive. There is so much daily noise about stock market prices these days that I’ve found it much more relaxing this way. However, I do enjoy a brief reflection at the end of the year. Here are the annual returns for select asset classes as benchmarked by ETFs per Morningstar after market close 12/31/19.
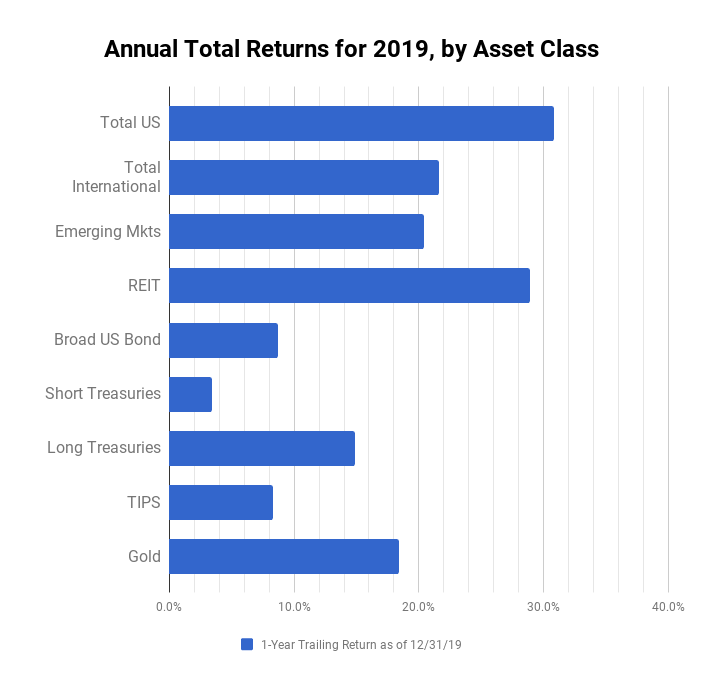
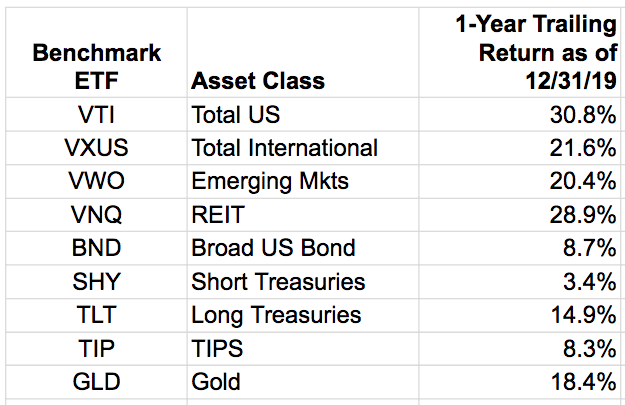
Commentary. As of 2017 year-end, the performance of every asset class was positive. The lowest positive return was from short-term US Treasuries. As of 2018 year-end, the performance of nearly every asset class was negative. The highest return was from short-term US Treasuries.
As of 2019 year-end, we find ourselves again in a situation where the return of nearly every major asset class was positive. And yet again, the lowest positive return was from short-term US Treasuries. Short-term Treasury bonds are slow, steady, and safe… but you also need to be in the risky asset game to reap the rewards when things are hot.
The Vanguard Target Retirement 2045 fund (roughly 90% diversified stocks and 10% bonds) was up 21.4% in 2017, down 7.9% in 2018, and up 24.9% in 2019. The benchmark for our personal portfolio, a more conservative mix of 70% stocks/30% bonds as we are close to living off it, was up 17.1% in 2017, down 5.9% in 2018, and up 21.2% in 2019.
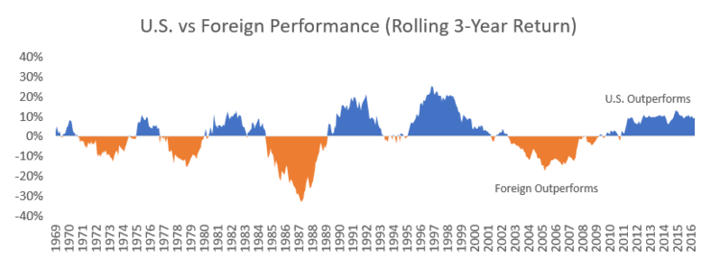
The more stocks keep going up, the more we are reminded that eventually they will go down again. There remains a lot of anxiety about a recession looming around the corner. A famous quote (perhaps by Gary Shilling?) states that “Markets can stay irrational longer than you can stay solvent.” This is usually brought up during stock market crashes, but also applies during bull markets. Yes, stocks will have another bad streak eventually, and future 10-year returns do look rather tepid, but you can also miss out on big gains while sitting on the sidelines waiting for that to happen.
I won’t lie – I am pleasantly surprised at my brokerage statement this year, but I’m also wary about future returns. What keeps me owning a big chunk of stocks is that I am confident that the hundreds of business that I own through these ETFs and mutual funds will collectively make a profit, reinvest some of it to keep growing, and distribute some of it to me in the form of cash dividends. I am also confident that my US government bonds, municipal bonds, and FDIC/NCUA-insured bank certificates will keep the panic if a market drop does come.






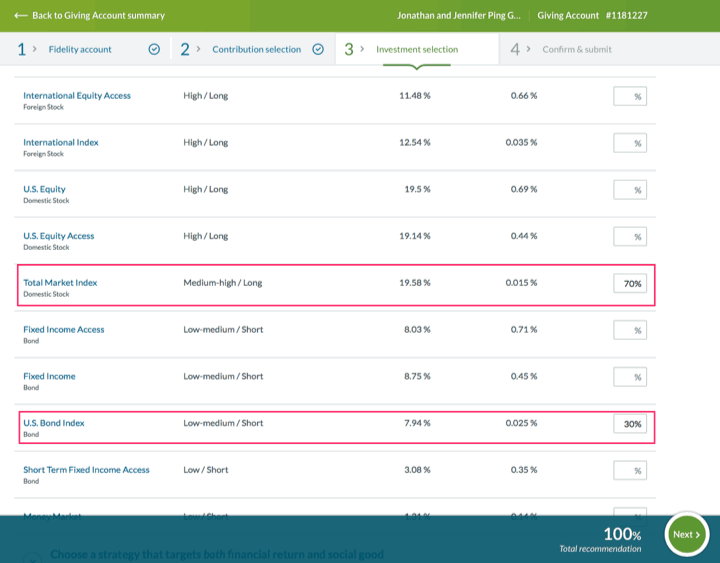
 If you own stocks in a taxable brokerage account and make charitable donations, consider donating your stocks this year instead of just writing a check. Why? Given the all-time market highs, your stocks, mutual funds, and/or ETFs probably have unrealized capital gains. When you donate an appreciated security that you’ve held for at least a year, you’ll both avoid paying long-term capital gains tax AND get a tax deduction for the full current market value.


 Investment research firm Morningstar has released their annual 529 College Savings Plans
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)