 Ally Bank has a new promotion called Ally Payback Time that is offering a 1% cash bonus (up to $1,000) on new deposits on top of their existing interest rates. Valid for both new and existing customers. Given the holding period, this roughly equates to the same total interest paid as a 3-month bank CD at 6% APY. Here’s how it works:
- Enroll by 10/21/18 at ally.com/payback. You must enroll or you won’t get the bonus. Existing customers must enroll with the same e-mail as linked to their Ally bank account.
- Fund account by 10/31/18. This means your account has to be approved, opened and funded by this date. Technically the terms state that the funds must arrive by 11/5/18, but that is likely just a grace period and you should initiate any fund transfers by 10/31/18.
- Maintain funds through 1/15/19. You must keep your new funds there through 1/15/19. This is really only a 2.5 month period if you waited until the last moment. Withdrawals may lower your bonus.
- Get cash bonus on 2/15/19. After another 30 days, they will deposit your cash bonus into your Ally account.
To be clear, the bonus applies to new funds added to an eligible Ally bank account, not your total balance. Eligible accounts include Ally Online Savings, Money Market, Interest Checking, and CD accounts.

Rough math. The current rate on the Ally Online Savings account is 1.90% APY, and the 11-month No Penalty CD is 2.10% APY on $25k+ balances (as of 10/15/18). Given that you can an additional 1% bonus in a bit under 3 months, the bonus itself works out to the equivalent of a 4% annualized yield. 2% plus 4% = 6%, so you’re looking at the equivalent of a 3-month CD at 6% APY for new money deposits between $1,000 and $100,000. At such a high yield, this promo is a “no-brainer” when compared to other liquid savings accounts for the next 3 months.
The promo page has a calculator to show you your total cash earned over a year. If you move over $10,000 at 1.90% APY, you’d get $190 of interest in a year plus a $100 bonus = $290 total. That would work out to a total of 2.9% APY if you were lazy and just kept it all there for a year. Still not too shabby.
Should I move money out of Ally and back in to qualify? No, it won’t make any difference as Ally has already thought of that. All new funds added after 10/8/18 will count as new money for this promotion. They’ve already set the start date in the past, so you gain nothing by delaying your enrollment.
Existing customers. As a longtime Ally accountholder, I’m happy to see that this offer includes existing customers, even if it has to be new money. The promotion should be called the “Ally Money Comeback Time” as lots of people are probably bringing back funds that in the past year or so.
Payback Time? This YouTube ad explains the meaning behind “Payback Time”, basically the megabanks pay you no interest and keep it for themselves:
Bottom line. Ally Bank has a new promotion to attract new money (or bring back old money). You get a 1% cash bonus (up to $1,000) on new deposits on top of their existing interest rates. For their savings account, this works out to a 3-month holding period paying roughly 6% annualized interest. You must enroll soon by 10/21 and your account must be opened and fully funded by 11/5/18 at the very latest.
 Citibank has
 Here’s my monthly roundup of the best interest rates on cash, roughly sorted from shortest to longest maturities. Check out my
 If you use PayPal to accept credit cards for your small business (eBay, Etsy, e-store, freelance, etc), you may not want to keep your money sitting at PayPal (especially if you are earning higher interest in your bank account). There is a feature called Auto Sweep that checks daily and automatically “sweeps” any money that arrives in your PayPal account into your bank account overnight.

 Chase just announced a new free stock trade program as part of a new online brokerage arm called You Invest. This means another megabank is moving more heavily into “relationship banking” where they hope you will keep your bank accounts, credit cards, brokerage accounts, and mortgage all at the same place. This is pretty significant as JP Morgan Chase is the largest US bank in terms of both market value and total customers (over 60 million).


 Interest rates continue to rise, and holders of existing certificates of deposit (CDs) may be wondering if it is a good idea to break their current CDs in order to take advantage of a new higher rate. Most CDs impose an early withdrawal penalty if you take money out before the CD matures. But the new rate is good enough, you might breakeven soon. This question is actually not that simple, as there are a few potential variables involved:
 Update October 2018. Here is a
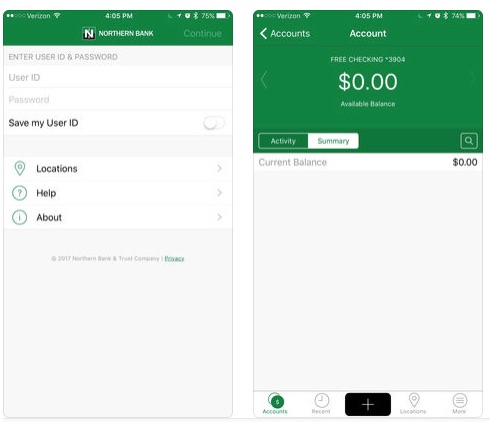
 Here comes another new “Direct” bank leapfrogging the current competition for some attention. The Northern Bank Direct Money Market account is offering 2.26% APY on average daily balances up to $250,000, and the rate is guaranteed through June 30, 2019. Of course, another bank could take the throne tomorrow, but at least this one comes with a rate guarantee. Other highlights:
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)