 Well, it finally happened. IndyMac Bank has been taken over by the FDIC, becoming the second-largest financial institution failure in U.S. history. I’ve been reading a bunch of new stories about it, and here are what I think are the highlights:
Customers: Don’t Panic!
Most people with regular checking or savings accounts don’t have too much to worry about. The FDIC has set up this official information page for customers. You can still use ATMs. Checks you write will still be processed. Electronic deposits and withdrawals will still go through. Online banking, phone banking and even the physical branches will re-open on Monday. You won’t even lose past interest:
All interest accrued through Friday, will be paid at your same rate. IndyMac Federal Bank will be reviewing rates and will provide further information soon. You will be notified of any changes.
From the LA Business Journal:
The Office of Thrift Supervision transferred control of the company to the Federal Deposit Insurance Corp. The FDIC said it will transfer insured deposits and assets of IndyMac Bank to a new federally operated institution called IndyMac Federal Bank that will open Monday. […] Regulators said that customers of IndyMac will have uninterrupted access to their accounts beginning next week at the bank’s 33 branches.
This is consistent with when I explored What happens if my bank fails? The FDIC seems to do a pretty good job of cleaning things up.
…Unless you exceeded the FDIC insurance limits
Customers are insured 100 percent for deposits up to $100,000. The FDIC said the bank has about $1 billion of “potentially uninsured deposits” held by 10,000 depositors. The FDIC said it will begin contacting uninsured customers on July 14. The agency said it plans to give customers with more than $100,000 at least 50 percent of their uninsured deposit amounts.
Wade Francis, president of Long Beach-based Unicon Financial Services, said there is “very little” chance that uninsured depositors will get all their money back because IndyMac had a large number of home loans, which will be difficult to sell off.
It boggles the mind that so many of the very same people who have enough money to exceed FDIC limits in the first place, don’t bother protecting it properly. The whole point of keeping money in banks is so that it is safe… Instead, people are getting 50% and go home and pray to see the rest again. Ouch.
Ouch For the FDIC, Too
From the LA Times:
Federal authorities estimated that the takeover of IndyMac, which had $32 billion in assets, would cost the FDIC $4 billion to $8 billion. […] The agency’s insurance fund has assets of about $52 billion.
That’s a big chunk of the FDIC’s own “emergency fund”…
Reality vs. Perception of Reality
There is a great quote from the 1992 movie Sneakers:
Cosmo: Posit: People think a bank might be financially shaky.
Martin Bishop: Consequence: People start to withdraw their money.
Cosmo: Result: Pretty soon it is financially shaky.
Martin Bishop: Conclusion: You can make banks fail.
Cosmo: Bzzt. I’ve already done that. Maybe you’ve heard about a few? Think bigger.
Martin Bishop: Stock market?
Cosmo: Yes.
Martin Bishop: Currency market?
Cosmo: Yes.
Martin Bishop: Commodities market?
Cosmo: Yes.
Martin Bishop: Small countries?
This is basically what happened to IndyMac bank. From CNN:
The banking regulator said it closed IndyMac after customers began a run on the lender following the [very public!] June 26 release of a letter by Sen. Charles Schumer, D-N.Y., urging several bank regulatory agencies that they take steps to prevent IndyMac’s collapse. In the 11 days that followed the letter’s release, depositors took out more than $1.3 billion, regulators said.
 I love
 RevolutionMoneyExchange $25 Bonus. Offer extended to May 15th, so get in by then if you haven’t already. Just sign-up with this PayPal alternative and grab your $25. You don’t even have to make a deposit or buy anything.
 Well, the CPI-U that I
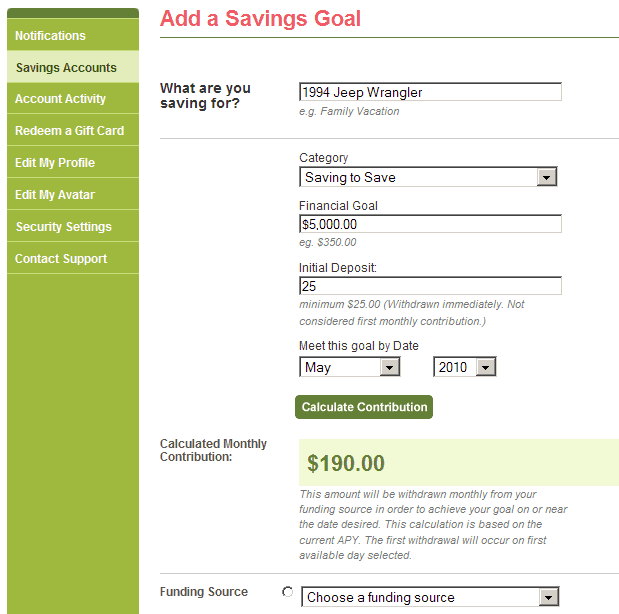
 When I first heard of SmartyPig, it sounded like a pretty cool idea. Give us back the piggy banks we had as kids, but make it virtual and public so that others can help directly with our goal. But a bunch of fees made it expensive and my enthusiasm disappeared. However, the folks at SmartyPig seem to have really listened to feedback, made some changes, and now I think it is deserving of another look. I opened an account to check things out. So, how is service different from a traditional bank?
 You may be expecting a review of the new online service
 How would you like to get returns linked to the S&P 500, with no chance of losing a penny? You can with the
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)