LendingClub P2P Loan Investment Returns Update 2010 Q3

LendingClub.com is a website that securitizes person-to-person loans so that you can lend money to other people in as little as $25 increments, and you collect the interest after some fees. The idea is to replace banks and credit cards as the major middlemen used for lending. “Investors earn better returns, borrowers pay lower rates.” I’ve been investing some money with them since they started in 2007.

Last time I wrote about LendingClub in May, I expressed concerns about their historical performance data living up to their marketed 9.65% returns and then LendingClub responded on why they thought things weren’t that bad. It’s been 3 months, so I figure it’s a good time for another update.

The first part of their argument is that they think that loan performance over time will go like this, with a drop and then significant recovery near the end of the term:
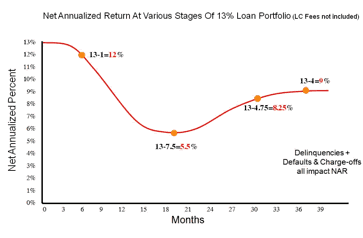
However, I don’t see that behavior happening. As you can see below, the older the loans, the lower the overall performance. Returns just keep dropping for loans going from 1.5 to 3 years old. There is no rise or recovery at the end of the three-year term. Data was taken from actual LC loans with observation date of August 17th, 2010.

Loans Originating Second Half of 2008 (about 1.5-2 years old)
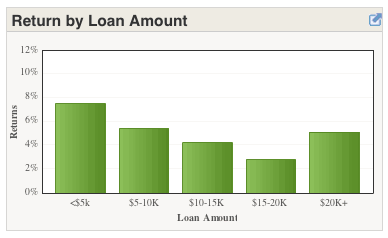
Loans Originating First Half of 2008 (about 2-2.5 years old)
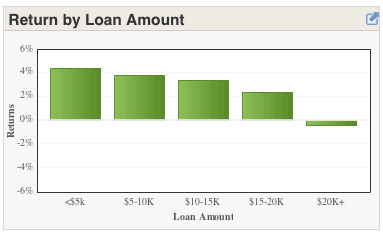
Loans Originating 6/1/2007 to 12/31/2007 (about 2.5-3 years old)
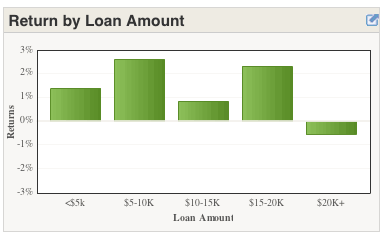

Note the change in the y-axis scale

Now, the next part of their argument was that all the loans that originated before they changed their credit requirements and interest rates at the end of 2008 weren’t a valid data set to be analyzing. (That doesn’t make me feel much better because as an early adopter, I hold a lot of those loans.) While improved underwriting may make the average returns higher, I don’t see why it should affect the overall performance behavior over time.

2009+ Loans Only

Okay, so the newer vintage loans that originated after January 1st, 2009 take into account their current lending criteria. In the end, we’ll just have to see if people really get higher returns. From now on, I’m going to try and track the performance every quarter. Here is the performance of loans originating in the first half of 2009, as of August 17th, 2010. Since it a loan has to be late for 4 months to be actually considered in default, this means the loans only have effective ages of 1 to 1.5 years.
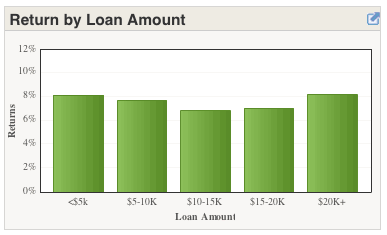
So far, not too bad at about 8% return. Here is the performance of loans originating in the first quarter of 2009 with two observation dates (May 2010 and August 2010) overlaid on top of each other. You can see that the loan performance has decreased slightly over the last 3 months. I hope that I am wrong, and that the performance does start to improve.
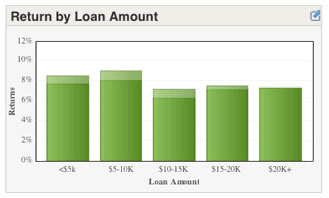
You may call me a LendingClub basher, but I still consider myself an active investor and supporter. I want them to have awesome returns, but the data simply doesn’t support the likelihood of earning 9.5% annually. Investors should go into it with realistic expectations, and ideally an interest in P2P social lending. Despite this, if LendingClub can average, say 6% returns going forward, that would still be quite an accomplishment for this new business model. I know I’d be happy with that.

To Prospective Borrowers
Honestly, LendingClub is more attractive as an option for borrowing money and/or credit card debt consolidation. You can borrow up to $25,000 and you can know your rate before actually applying for the loan. If the rate quote they give you can be beaten elsewhere, then just walk away with no obligation. When writing your loan application, try to include as much applicable information as possible (reason for loan, how will you repay, monthly budget breakdown) and answer all lender questions promptly for the best results.
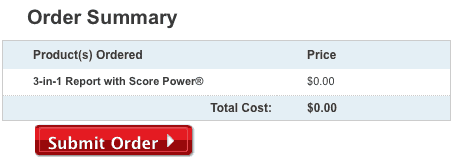
Equifax.com Promotional Code: Free 3-in-1 Credit Report & FICO Score

Visit the 3-in-1 Credit Report with Score page at Equifax and click on “Buy Now”. You’ll have to register on the website or log in with a previously created account. There is no need to enter credit card information. When you are able to, enter the promotion code NOC431 and the price will show as $0.00. Via littlepenguin of SD. Users have reported mixed success with many people getting some sort of error, but it worked fine for me:

You will end up with your credit reports from all three credit bureaus (Experian, Equifax, and TransUnion) as well as your official FICO score based on your Experian credit report. (You know you have 3 different FICO scores – one from each bureau – right?) A pretty good deal, although I wouldn’t say it’s worth the $39.95 retail price. I wouldn’t wait too long on this, the code could expire at any time. (Update: Appears to be expired, some people are calling in manually and applying the code with success.)

Citibank Back-to-School Student Credit Cards

Going back to school? Citibank has some good card options for college students:

  • Citi mtvU Platinum Select Visa Card
  • Citi Forward Card for College Students – $75 Statement Credit

Both the mtvU and Forward cards offer 5x rewards on bookstores, movies, music, and restaurants – boy do they know students. 5x ThankYou points amounts to 3.45% cash back or 5% back in the form of gift cards from certain retailers. Great deal if you can handle credit responsibly. I’m pretty sure I applied for my first credit card in college in exchange for a cheap t-shirt with a Cal logo on it and no rewards whatsoever. Good thing I’ve always hated owing other people money…

As noted previously, 5x points on bookstores also includes anything bought at Amazon.com (a bookstore!). Would go perfectly with your free year of Amazon Prime.

Free Year of Amazon Prime For Students (.edu email)

Amazon Student LogoAmazon.com has a new program called Amazon Student where you can get “exclusive deals”, the best of which is a free one-year subscription to Amazon Prime. This allows you to get the convenience of free 2-day shipping on most products (including textbooks and even some used books) with no minimum order amount. Usually costs $79 a year.

You can even keep your existing Amazon.com account, just click here, enter your .edu e-mail address, and click on the confirmation e-mail to activate. If you have an .edu e-mail, try it!

This is a really nice perk, and would go great with the Citi Forward® Card gives you 5 ThankYou® Points for every $1 you spend at restaurants and on entertainment, like bookstores, of which Amazon.com counts regardless of what you are actually buying at the bookstore. Up to 2% APR reduction when using credit wisely. This equates to 5% back in the form of gift cards at select retailers, or a 3.45% pure cashback return. Really, I’ve done it.  2,500 bonus ThankYou Points after spending $500 within the first 3 months of cardmembership and up to 1,200 bonus ThankYou Points for paying on time and staying under your credit limit. Watch your interest rate go down and your ThankYou Points go up.

See my Citi Forward review and rewards follow-up for more details.

New Credit Card Trend: Rotating Rewards, Swiss Army Style

When you charge something on your credit card, the merchant usually pays about 2-3% in transaction fees for the convenience and benefit of accepting these cards (it makes it easier for people to spend money with them). In order to get their specific card “in your wallet”, issuers often rebate part of these fees in the form of % cashback rewards or frequent flier miles. This makes sense, because many people with good credit and/or higher spending don’t carry balances so that the primary source of profits is from these transaction fees.

Swiss Army Knife

The trick for issuing banks, of course, is to offer as little rewards as possible yet still convince enough people as a group to use the card. The newest trend is to offer a high 3% to 5% back (more than they take in!) but only on a specific group of rotating purchases. Usually the rest earn 1% cashback. If you pay attention to the rules, this can make for some significant savings. I think of it as a Swiss army knife of credit cards; you just need to pick the right one for the job. 🙂 It might even be time to dust off an old card you don’t use anymore.

Here are some popular cards and their current rotating categories. Also, new cardholders can combine with current sign-up bonuses of up to $100 upfront.

Citi® Dividend Platinum Select® Visa® Card
Reward categories change quarterly. From April 1st to June 30th, you can earn 5% cash back on

  • Home Depot
  • Home Furnishing purchases
  • Home & Garden Purchases

After you get your card, you must enroll by logging into your account or calling 1-800-231-0891. There is no cap on the 5% back, except for the $300 overall cap on all dividend rewards annually. All other purchases do earn a standard 1% with no tiers, and rewards do not expire as long as you have activity once every 12 months.

Chase Freedom Visa – $100 Bonus Cash Back
Reward categories change quarterly. From January 1 to March 31, 2012 you can earn 5% cash back on up to $1,500 spent in the following categories:

  • Gas Stations
  • Amazon.com

You must enroll at ChaseBonus.com. All other purchases do earn a standard 1%, with no tiers or expiration of rewards. Currently, the Chase Freedom Visa – $100 Bonus Cash Back has a promotion offering a $100 check if you sign up and make $500 in purchases in your first three months.

Discover More CardDiscover More Card
Reward categories change quarterly. From January 1st to March 31st, you can earn 5% cash back on up to $300 spent in the following categories:

  • Gas
  • Entertainment

In September, you can also earn 5% cash back on up to $200 spent in grocery stores and drugstores. You must enroll online to activate the rewards each quarter. Discover card has a tiered cashback rate (1% unlimited Cashback Bonus on purchases after your total annual purchases exceed $3000; purchases that are part of your first $3000 earn .25%.).

PenFed Platinum Cashback Rewards CardPenFed Platinum Cashback Rewards Card
Bonus categories appear and change regularly for this card, but not on a set schedule.

You can view all the eligible merchants. You don’t need to enroll. This is in addition to the year-round rewards structure of 5% cash back on gas purchases (must pay at pump) and 1% cash back on everything else. Rewards are credited monthly on your next statement.

Note: To get this card, you must also have membership to the Pentagon Federal Credit Union (you can apply for both at the same time). In general, membership is open to the military, US government employees, or the family or household of existing members. However, anyone can become eligible by joining the National Military Family Association (NMFA) for a $20 one-time fee. PenFed also offers other competitive financial products, including low-rate mortgages and long-term CD rates.

In order to keep track of all these, I usually just cut off the top part of a Post-It note with the sticky backing, and use it to label each card in my wallet. Here’s a pic of one of my cards:

Citi Dividend World Mastercard Image
 

myFICO Coupon Code: 20% to 30% Off

Update February 2011: Use coupon code FICO25 for 25% off!

I am not a big fan having to purchase credit scores. I can understand why a lender would pay to get a calculation of your likelihood of defaulting on your loan, but if it’s based on our data, why do we have to pay just to see it? Even if I am declined for a loan, I can only see my report, not the numerical score that supposedly defines my financial life.

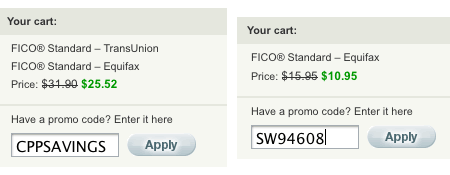
There are plenty of “FAKE-O” credit scores out there, but the only place to get your real FICO score is myFICO.com. If you must order your score, use the promotional code CPPSAVINGS to get 20% off.

For the Equifax credit score only, you can get it for $10.95 using the code SW94608, which is over 30% off. You enter the promo code relatively late in the buying process, right before entering your credit card information.

Whenever you do buy a score, I would recommend trying to correlate your score and the current information on your report. Then you can start to learn what changes really affect your score. I’ve applied for 12 credit cards and canceled 5 with almost no appreciable affect to my scores (see credit score myths) – despite all the “rules” – only to have a huge balance on my mom’s credit card (with me as authorized user) show up and drop it by 30 points.

Penfed Visa Platinum Cashback Rewards Card – 5% Cash Back on Gas

There used to be a bunch of great cashback cards for gas, but now the only one that still offers 5% back to consumers is the PenFed Visa® Platinum Cash Rewards Card. It offers:

  • 5% cash back on gas purchases (must pay at pump)
  • 0.25% cash back on everything else.

No annual fee. The rewards are credited on each monthly statement, so that you don’t have to wait to meet any $50 thresholds or remember to call in. If your family spends $200 on gas per month, that alone will have this card paying you $120 per year in rewards.

The catch? You must also be a member of the Pentagon Federal Credit Union, and you can apply for membership as part of the credit card application. In general, membership is open to members of the military and affiliated organizations, US government employees, or the family or household of existing members. However, anyone can become eligible by joining the National Military Family Association (NMFA) for a $20 one-time fee (and it goes to a good cause). PenFed also offers other competitive financial products, including low-rate mortgages and long-term CD rates.

Lower Your Credit Card APR: Phone Script from DebtGoal

DebtGoal is a new site that helps you track and manage your debt-reduction goals (as opposed to a debt settlement company). After the free trial, it runs $11.95 per month. One of the things they do is try and guide you to lower the interest rates on your credit cards. Here’s a sample script that you can try out yourself for free, which is quite simple but probably also effective:
Hello, my name is _______________. I have been a cardholder since ____. In the past few months, several credit card companies have offered me lower rates than my current rate with you. I value my relationship with you, but I would like you to match the other offers that I have received and reduce my interest rate by ___%. Are you authorized to adjust my interest rate?

It can be handy to actually have offers or other cards in front of you that really have lower rates. Depending on their response, you could also throw in one of these:

  • “Are there other people who have the authority to lower my rate? May I speak with them?”
  • “Do you have a promotional rate that I can take advantage of?”
  • “What would I have to do to get a lower rate? Can I call back later when I meet those criteria?”
  • “Can I qualify for a hardship program?”

Any other success stories or tips?

Quick Tip: Differences Between Bank and Credit Card Sign-up Bonuses

Just a quick tip that a reader brought up… when you receive a “bonus” from a bank, it is usually going to be reported as taxable interest income to the IRS via a 1099-INT form. Since such interest is taxed as ordinary income, you should remember that you will probably owe income tax on the bonus amount multiplied by your marginal tax rate (2010). After personal exemptions and standard deductions, students or other people with lower incomes might find that they don’t owe tax anyway, but it’s still worth noting.

Another way that this can get messy is if the bank offers an item like an mp3 player, and reports the full retail value while the actual market price is much lower. Let’s say they give you an iPod that you can find for $200 but mark it as worth $300. If you’re in the 28% tax bracket, you’ll be paying $84 in taxes for that “free” iPod. Still a good deal, but only if you would really pay that much for it! (Example: iPod Touch from KeyBank.)

However, incentives from a credit card sign-up are usually non-taxable. They don’t report any income on 1099-INTs, and due to a IRS private-letter ruling, tax experts tend to view the bonuses as a rebate on the purchases you make on the cards. (Example: $500 cash bonus from credit cards.)

[Insert “The More You Know” theme song…]

Chase Sapphire Preferred Card: 50,000 Bonus Points Review

Chase Sapphire Preferred ImageThe Chase Sapphire Preferred® Card is a rewards credit card that is now offering new cardholders 50,000 bonus points after you spend $4,000 in purchases within the first 3 months. This is quite a good deal, as 50,000 points can be redeemed for $625 in travel when you redeem through Chase Ultimate Rewards™ (you can buy a more expensive ticket and simply pay the difference). Earn 5,000 additional bonus points after you add the first authorized user and make a purchase in the first 3 months from account opening. No annual fee for the first year, $95 in future years.

[This card is the “big brother” of the regular Chase Sapphire® Card, where you can get 10,000 points after you spend $500 in the first 3 months (no minimum amount) – that’s $100 in travel rewards when you redeem through Chase Ultimate Rewards! and there is no annual fee in the first year or subsequent years. As well as an additional 2,500 bonus points after you add the first authorized user and make a purchase in the first 3 months from account opening. I would personally rather go for the 40,000 points offer since the annual fee is waived for an entire year.]

Rewards Features
As a rewards card, the Sapphire offers 2 points per dollar spent on travel, 2 points per dollar spent on dining at restaurants and 1 point for every dollar on all other purchases (100 points = $1, or the usual 1% back). However, this card separates itself with it’s flexible redemptions. Cash redemptions are easy – you can redeem in $1 increments as long as above $20, so you could cash out $27 or $253 without anything left over. There are no earning caps, or points expiration dates.

As noted above, airplane ticket redemptions can also be maximized because you can book any ticket and simply pay the difference. For example, 25,000 points can be used for any ticket up to $312.50, but if say you wanted a $325 ticket you could just pay the $12.50 difference. On other cards, you would have to go up another tier and spend an extra 10,000 points or similar.

More Details
In addition, Sapphire also promotes a “premium, dedicated service line that gives you access to a live person anytime, 24/7.” I tested this out and it really works! A real person picks up after a couple rings… it’s actually a bit disconcerting. You can also redeem cash rewards over the phone for free, although booking rewards tickets this way costs $20 (doing so online is free).

Fine print:

Earn 50,000 bonus miles – That’s $625 in travel when you redeem through Chase Ultimate Rewards™
You will receive 50,000 bonus points with this bonus offer, which can be redeemed for a round trip ticket on most major airlines up to a $625 value. Ticket value exceeding $625 can be charged to your new card. A service fee of up to $20 per ticket may be charged for the use of our toll-free number to book or change airline itineraries. Redemptions made online do not have a service fee. Cardmember is responsible for any airline or government imposed fees. To qualify and receive your bonus, you must make qualifying transactions totaling $4,000 or more during the first 3 months from account opening. Qualifying transactions include purchases, balance transfers, and any checks that are used to access your account, and exclude cash advances. After qualifying, please allow 6 to 8 weeks for bonus points to post to your account. To be eligible for this bonus offer, account must be open and not in default at the time of fulfillment. This one-time bonus offer is valid only for first-time cardmembers with new accounts. Previous and existing cardmembers/accounts are not eligible for this bonus offer.

I already have the Chase Sapphire regular card and got my $250 (previous offer). But given how easy it was to redeem the reward, I’m going to have Mrs. MMB apply for a Chase Sapphire Preferred® Card as well this time. (I try not to bother her too much unless it’s very juicy.)

  • Chase Sapphire Preferred Card application link

“Disclaimer: This content is not provided or commissioned by the issuer. Opinions expressed here are author’s alone, not those of the issuer, and have not been reviewed, approved or otherwise endorsed by the issuer. This site may be compensated through the issuer’s Affiliate Program.  “The responses below are not provided or commissioned by the bank advertiser. Responses have not been reviewed, approved or otherwise endorsed by the bank advertiser. It is not the bank advertiser’s responsibility to ensure all posts and/or questions are answered.”

Chase Sapphire Card: $100 Signup Bonus

Chase Sapphire Card BannerThe Chase Sapphire Card is a new rewards credit card that is offering 10,000 bonus points after your first purchase on the credit card, which can be redeemed for $100 cash. No annual fee.
As a rewards card, it offers 1 point for every dollar in purchases (100 points = $1, or the usual 1% back). The nice part is that redemptions are easy – you can even redeem in $1 increments as long as above $20, so you could cash out $27 or $113 without anything left over. There are no earning caps, or points expiration dates.

In addition, you can get double points on airfare booked through their Ultimate Rewards website. It also promotes a “premium, dedicated service line that gives you access to a live person anytime, 24/7.” I tested this out a couple of times and it really works! A real person picks up after a couple rings… it’s actually a bit disconcerting. Makes redeeming rewards much easier as well.

Fine print:

10,000 bonus points
You will qualify for and receive your bonus after your first purchase/first use of the card. First purchase/first use includes purchases, balance transfers, or any checks that are used to access your account, and excludes cash advances. After qualifying, please allow 6 to 8 weeks for bonus points to post to your account. This one-time bonus offer is valid only for first-time cardmembers with new accounts.

Free Equifax Credit Score Card

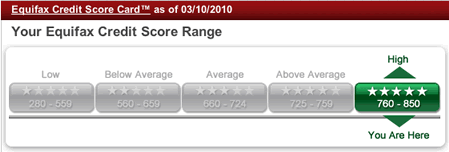
Don’t get too excited. Equifax is offering a free “Credit Score Card“, which in reality just gives you a range of what your credit score is. And the score is from their “Equifax Risk Score” system, not a FICO score. (You can still get 30% off a real FICO score with a current my FICO coupon code.) The Equifax Risk Score does range from 280-850, which basically the same as FICO from 300 to 850.

Well, it’s free and it’s from Equifax which has all my personal information anyway, so what the heck. Here are my results:

Key Factor(s) Affecting Your Score:
Because your credit score is in the highest range, you may qualify for some of the lowest interest rates and offers from lenders. Below are the top factors that may be preventing you from achieving an even higher credit score.

  • There is insufficient information, or no account history, for one or more types of accounts: for example, auto loans, mortgage loans, personal loans or credit cards.
  • The proportion of retail accounts, such as department store cards, compared to all of the credit accounts in your credit file.

It still seems stupid that to get a “perfect” credit score of 850, I’ll need to add an auto loan, a personal loan, and a department store card. I’ll hopefully never have any one of those, and I’m betting I can still get just about any loan out there. Nobody needs perfect credit.