Call Your Credit and ATM Card Issuers Before Traveling Internationally

I just finished calling all of the issuers for the credit and ATM cards that I plan on using internationally – Capital One, Citibank, WaMu, and Bank of America – in order to avoid my cards being frozen due to fraud concerns. I remember doing this occasionally before, but not for all of them.

Surprisingly, every single card issuer seemed to have a specific protocol to handle such concerns. I was either forwarded to some sort of Fraud Specialist or asked to fill out a form outlining where I was traveling to and the exact start and end dates. It seems like their fraud monitoring systems are getting quite advanced. All of them thanked me for calling ahead of time, which made me feel like they’ve probably had to deal with a lot of angry (stranded?) travelers.

Oh, and they also told me the international toll-free numbers to reach their customer service from abroad. Using them is easy. Go to a pay phone, reach the operator, and call the number collect. I decided to simply write these numbers on the signature panel on the back of the cards. I’m glad I called!

For more information, see my other post on this subject: Travel and Money: Best Way To Get Cash, Best Credit Cards, and Safety Concerns. It includes why I hate traveler’s checks, why I use my Capital One card exclusively while traveling, and emergency numbers for Visa and Mastercard.
Discover Card Holiday Mall Promotion: $20 off each $200 spent

Discover $20 Gift CardDiscover Card is again running their Holiday Mall Promotion, which gives you $20 back for every $200 that you spend at limited mall locations.
Get a $20 Discover® Gift Card when you make $200 in purchases with your Discover Card at a participating mall between 11/01/08–01/04/09, while supplies last. Original receipts and the Discover Card used to make the purchases must be presented to a participating mall’s Customer Service by 01/04/09. Limit 5 Gift Cards per account, while supplies last, during the promotion period. Gift Card is valid through July 31, 2009.

Basically, you can get up to 10% back if you spend an exact multiple of $200, with a maximum $100 off $1,000 per Discover card account. (Additional cardholders seem to count as a separate “account”.) Not a bad deal if you’re gonna spend that much anyways. Mmm… Macbook…

During a previous year, a reader happened upon a loophole: If you return your purchase, there is no requirement to return the gift cards. Maybe you found something cheaper elsewhere. This brought up some ethical problems. Keep them? Or try handing them back to the Customer Service clerk? But be careful, because if you end up deciding to buy more stuff again later, you won’t be able to participate again since they don’t have any official mechanism to return the gift cards.

New Discover Card Sign-Up Promotions: $50 to $100
This would go nicely with the Discover More Card which now offers 0% on balance transfers and purchases for 15 months. 1% cash back on most purchases, and 5% back on rotating special categories.

The Miles by Discover Card also offers 12,000 Miles (1,000 miles per month with any purchase for a year). This can be redeemed for $100 cash credit towards any travel purchase put on the card (air, hotel, car rental), or you can get a $50 gift card + $25 cash.

Discover More: 0% APR Balance Transfer Fee Cap Ends October 31st

It looks like the credit crunch continues to trickle down to everything financial, including tightening up in the credit card industry. I have it on good authority that the $75 balance transfer fee cap on the Discover More card will end on October 31st. (Update: Yes, the cap is now gone.)

Why care? The Discover More Card – No Balance Transfer Fee* is just about the last credit card with a 0% APR balance transfer for 12 months, as well as a $75 balance transfer fee cap. This is important because you may have noticed that nearly all other 0% APR cards have an uncapped 3% fee. So if you transferred $10,000, the fee would be $300. On a $20,000 balance, that would be $600!. The cap saves you lots of money, and these offers have only gotten more scarce with time.

Even though I don’t carry a balance, I have used this card to make some extra money off credit card arbitrage.

Getting Your Money
You can usually request a balance transfer to be sent directly to a card with a balance on it. (Or you could send it to a Citibank card without a balance on it, and request a refund check.) However, a reader wrote in last week to say that you can also call them up afterward and request a balance transfer check to be sent to you directly from Discover.

If you’ve been thinking about applying but putting it off, now would be the time to do it! According a Discover CSR, if you apply now to lock in the offer, you have until February to request your balance transfer. (Update: There is now no cap.)

Chase Freedom Rewards Card – 5% Back On Popular Spending Categories

Travel and Money: Best Way To Get Cash, Best Credit Cards, and Safety Concerns

I wouldn’t say my wife and I are well-traveled, but we do try and experience other cultures whenever we can. Given work constraints and Corporate America’s hatred of vacations (2 weeks a year??), we are lucky if we can manage one trip per year. However, I think we’ve worked out a pretty good system of managing money needs while abroad.
Travelers Checks?
I never buy travelers checks. You often have to pay a fee when you buy them, and then you might have to pay a fee for exchanging them to local currency. Or you’re searching all day for the American Express office. Less and less stores accept them for purchases, due to fraud and theft. If your signatures don’t exactly match, they give you grief. If you get them wet, they are useless and you have to replace them.

Most importantly: Any place that does take them will most likely accept credit cards, which are a better alternative (see below).

Best Credit Card For International Travel
Whenever possible, I use a credit card for making purchases while abroad. Hotels, transportation, sightseeing tickets, and so on. However, most credit cards are pretty expensive when it comes to foreign currency purchases. Visa and Mastercard charge a standard 1% “conversion” fee on top of the wholesale “interbank” exchange rate. Many major credit card issuers like Citi, Chase, and American Express charge you another 2%-3% on top of that. You’re losing up to 4% off the bat.

So what do I use? My favorite card, hands down, is my credit card from Capital One . I have used this card from China to France with no issues at all. Capital One charges you only the interbank currency exchange rate. They pay the Visa/Mastercard 1% fee for you, and they don’t have any self-imposed surcharge. Finally, this specific card gives you 1% cash back on all purchases (2% for groceries/gas) and has no annual fee.

Net result: Not only do I get the best exchange rate possible, but I actually gain 1% cash back on my foreign purchases. It’s better than cash!

(I only use this card internationally. While in the US, I prefer these cash back credit cards.)

ATM Cards / Getting Cash
I used to worry about bringing some local currency with me, but it is usually expensive to get this done in the US. (Always compare their rates with the interbank rates at Oanda.com.) Nowadays, if you are arriving in a large international airport, there is hardly any chance they won’t have ATMs available. I do bring $100 in US $20 bills in my money belt as an added backup.

When it comes to getting cash in local currency from ATMs, there are also fees to be aware of. The local ATM may charge a fee, although bigger banks are less likely to. Your bank may also charge a fee for using a non-network foreign ATM. Finally, they may charge a surcharge for the currency exchange itself.

Because I use a credit card for most large purchases, I usually only need cash for restaurants and other small things. Therefore, I usually take out all the cash I expect to spend during my stay all at once, as it is no more than a few hundred dollars. Since I only have to pay these fees once, I don’t worry about them as much.

For example, on a $300 withdrawal using my normal WaMu Free Checking account, I will be charged a 3% exchange fee + no ATM fees. I am okay with paying a one-time fee of $9 for this convenience. My backup card is with Bank of America, where it would have cost $8 total (1% + $5), though they do have some partner banks with no fees. I like sticking with big banks here.

A good comparison of all these card fees is located here.

Money Belt and Wallet
After experiencing firsthand how slick a professional pickpocket can be in an Italian train, I don’t go anywhere without my trusty money belt keeping everything hidden safely underneath my clothes. I usually put in my week’s worth of cash, my backup credit card, two ATM cards, emergency numbers, and my passport.

My wallet only holds a day’s worth of cash (~$40) and my primary credit card. I usually also have travel pants with zippered pockets. This way, if it gets stolen I am only out a small amount of money and one credit card.

Lost Your Credit Card While Traveling?
You can easily report your lost card to the major issuers while traveling internationally by calling these US numbers collect. Write them down and keep in your money belt, along with any credit card numbers.

  • Visa: 410-581-9994
  • Mastercard: 636-722-7111
  • American Express: 336-393-1111

US Mint Lets You Buy Cash With A Credit Card

Reader Chris sends in a way to turn credit into cash:

I just discovered a great way to turn credit into cash. This would be great to use with a 0% intro APR card and stick in the bank.

Circulating $1 Coin Direct Ship Rolls

If you go to checkout these have free shipping. You can only order $500 at a time. I haven’t tried doing it multiple times, but in theory you could do it over and over again. I am planning to max out my card and just take these coins up to the bank when they come in, and just pay the minimum payment each month. I’ll then put the money in a money market to get maximum interest. Just thought you might be interested. Thanks again!

In addition to 0% intro APR cards, it may be easier to just buy them with one that offers cashback or other rebates. Are we finally ready for dollar coins in the US? I know $1 paper bills are wasteful, but I still hate carrying around heavy coins. I used to ask for Sacagawea $1 coins for bridge toll booths until I signed up for the electronic auto-debit system.

$100 Bonus + 0% APR for 12 Months For Discover Business Card

The new promotion from the Discover Business Card has some nice features… First, you can earn a $100 Cashback Bonus when you make $1000 in purchases within 3 months after your account is opened. You can get 5% back on office supplies, 2% on gas, up to 1% on all other purchases.

On top of that, it has 0% APR for 12 months for both purchases and balance transfers for 12 months. Since the purchases are also at 0%, there is no hurry to pay that initial $1,000 off. For balance transfers, there is 3% fee for each balance transfer, with a minimum of $5 and a maximum of $75. This is not bad in the current credit card environment. Even if you do not have a higher interest balance to transfer here, this might be worth making some free money off of, especially since the $100 incentive basically negates the balance transfer fee and then some.

Another interesting feature is the advertised “Fee-free Purchasechecks that earn Cashback Bonus®. to pay merchants who don’t accept credit cards”. I was excited by the prospect of earning rewards by simply writing a check, but then I saw this in the fine print: “APR for PurchaseCheck Purchases: 13.99%”. Ouch.

As with all these business cards, individuals can apply as sole proprietors by simply using their name as the business name. You just need to put your Social Security number as requested, and leave the Federal Tax ID blank for this application (it will use your SSN). More $100 bonuses listed here.

Save $0.20/gallon Using Gas Rebate Credit Cards

Gas Rebate Credit Cards

I think the two most effective ways for most people to reduce gas costs is to simply (1) consciously attempt to drive less and (2) use a credit card that offer rebates on gas purchases. Getting 5% back is like saving nearly 20 cents per gallon (more in some places), much easier than to looking for a gas station with a lower price by a few cents or sweating profusely with no air conditioning on. Here are some good ones…

Discover Open Road
The Discover Open Road Card offers 5% cashback on gas from any station and auto maintenance purchases on your first $100 spent each billing period, and up to 1% tiered on all other purchases. No annual fee.

PenFed Platinum Rewards
The PenFed Platinum Rewards Card offers 5% back on gas purchases paid at the pump, 2% back at the supermarket, and 1% on all other purchases. No annual fee. To apply you must first join the Pentagon Federal credit union, where you must either have the appropriate military affiliation or join the National Military Family Association (NMFA) for a fee.

Chase Freedom Visa
The Chase Freedom Visa – $200 Bonus Cash Back offers a Rewards program includes 5% Bonus Cash Back in popular, rotating categories Like Gas, Home Improvement and Department Stores.

Business Cards
Here are some business cards with good cash back. Most individuals (sole proprietors) can simply use their Social Security number for the Business Tax ID number, and their name as the business name if asked.

American Express Costco TrueEarnings
The TrueEarnings Card from Costco and American Express offers 5% back on automobile gas bought anywhere, including at Costco gas stations. You also get 3% on all restaurants, 2% on travel, and 1% on everything else. No annual fee. (The regular (non-business) version of the card gets 3% back on automobile gas, 3% on restaurants, 2% on travel, and 1% on everything else.)

Updates: Earn $100+ In Free Money Trying Out Financial Services

Here’s an updated list of companies willing to pay you to try out their services. None of these listed require a credit check. See links for more info.

RevolutionMoneyExchange $25 Bonus. Offer extended to May 15th, so get in by then if you haven’t already. Just sign-up with this PayPal alternative and grab your $25. You don’t even have to make a deposit or buy anything. More details here.
Ebates $10 Bonus (+$18 possible). Ebates offers rebates on online store purchases. After your first transaction, you’ll get a $10 bonus. Just sign-up with your e-mail and you’ll see the $10 in your account. One suggestion: sign-up for a free trial of Netflix through Ebates and get another $18, and they’ll send you $28 during their next cycle. (Looks like you have to become a paying member, cheapest plan is $4.99/month.) Just remember to cancel in time. More details here.

Prosper $25 Bonus. Peer-to-peer lending means you get to earn interest by lending to people you choose. Make a loan of $50, and you’ll receive a $25 bonus on top of your interest rate. More details here.

Capital One 360 $25 Bonus. One of the earliest online-only savings accounts, Capital One 360 will pay you $25 immediately if your initial deposit is at least $250. The account currently earns 3.0% APY.

ShareBuilder $50 Bonus. If you open an account with this brokerage and make any one trade, you will earn $50. In the application, say you are responding to a promotion and use the promo code “50GO28“. More info based on a previous similar offer.

I have applied and received all of the bonuses above successfully except for the Prosper one, as I had signed up before the promotion started. You can also get $100 all at once by applying for one of these credit cards, although applying will require a credit check (and some spending restraint, I suppose).

ThankYou Points: Double Your Redemption Rate With The Fixed Flight Option

If you have a Citibank credit card and are collecting ThankYou points, you are probably familiar with the various gift cards available at approximately a 1 point to 1 cent ratio, or 10,000 points = $100 gift card. You may even be familiar with the Fixed Point redemption option for travel. This not-so-publicized option allows you to redeem 20,000 ThankYou points for any domestic coach flight up to $400 in value (per Expedia.com). That’s nearly twice the value, with no blackout dates, no seat availability issues, no 14-day advance booking requirement. You do have to pay the taxes and fees, however, which can be up to $50 if there are multiple stops. (For details see the FAQ, click on Travel Rewards.)

It’s actually quite nice, and I have booked a ticket before this way before. The problem is, they have been gradually restricting which credit cards are eligible to redeem this options. The list went from virtually all Citi cards to only a select few.

This only left me with either gift cards or the variable point flight option, which is not horrible but much worse in comparison. Essentially one point = 1 cent, so 20,000 ThankYou points would only cover a $200 ticket on Expedia.com. Double-checking, I see that one way to qualify for the fixed point redemption is to have or open up a bank account at Citibank, specifically the “Citibank Account” which has a minimum balance of $6,000 across your accounts.

However, there is another easier way. I missed the Expedia Account part! What did that mean? Surely this was some sort of special account, and not just that simple free account that tracks my itineraries at Expedia? Well, it was. But merging your Expedia account to your existing ThankYou account was very tricky, until I stumbled across this post at the FlyerTalk forums. Here is my simplified version, which worked great for me:

1. Create a new Expedia account. Unless you really use your Expedia account, this makes it easy. When you are signing up, do not enter your existing ThankYou account number. Have them generate a new one, and write it down.

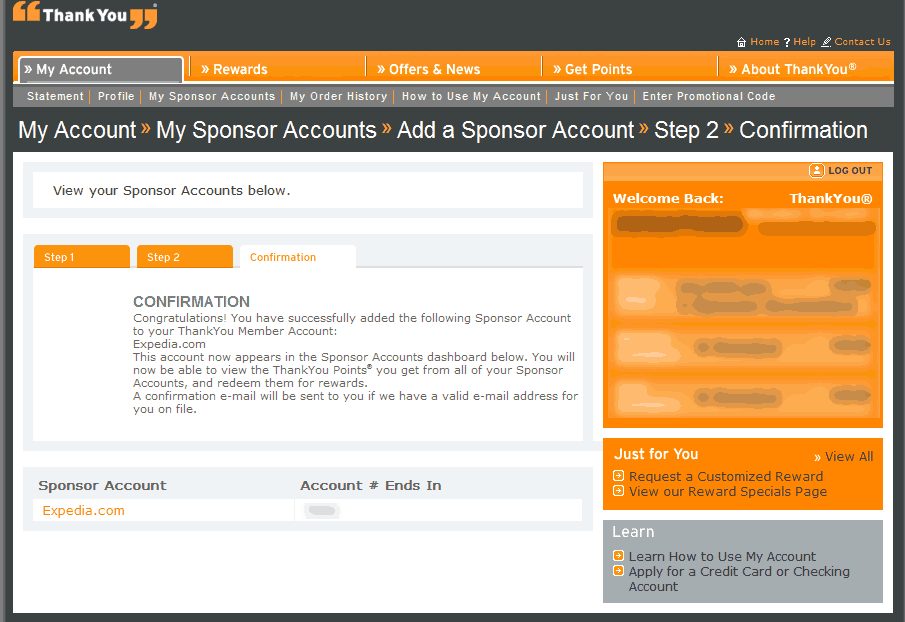
2. Now log into your ThankYou Network account that you wish to redeem points from. From the menu bars at the top, click on My Account » My Sponsor Accounts » Add a Sponsor Account. Type in your new ThankYou account number from above, and confirm. You should now have merged the two accounts together, with this result:

altext

Voila… now you have an Expedia Account as a sponsor account, and the fixed point redemption option is available to you. I just hope this window stays open long enough for me to use it again.

(Update: This option is set to go away at the end of February.)

TrueEarnings Card from Costco and American Express – Rewards Card Review

True Earnings Card from Costco and American ExpressHere’s another solid all-around rewards credit card that is much better than all those generic 1% back cards out there. The TrueEarnings® Card from Costco and American Express offers the following:

  • 3% cash back at U.S. gas stations and on gasoline at Costco  (up to $4,000)
  • 2% cash back at U.S. restaurants
  • 2% cash back on eligible travel purchases (airline, lodging, car rental, cruise line, travel agency and tour operators)
  • 1% cash back on other purchases, including Costco

I’m pretty sure this is also better than their previous offer, I don’t remember there being a gas rebate before (I might be wrong). If eating out and gas are your biggest expenses after housing (like us on many months), then this looks pretty good. There is also no limit on the cash back you can earn. Might go nicely with the 2% cash back from Executive memberships. Terms and restrictions apply.

There is no annual fee, but you must have a Costco membership to apply. (The TrueEarnings card can also replace your Costco Membership Card. ) Regarding getting the cash back:

“Rebate is awarded annually in the form of an in-store coupon redeemable for cash or merchandise at any U.S. Costco Warehouse.”

Why not cash in the coupon, and then charge your Costco purchase to get another 1% back? 😉

Reasons All Homeowners Should Get A HELOC? (Home Equity Line of Credit)

With my new fat mortgage, I’m considering whether to also take out a Home Equity Line of Credit (HELoC). This is not a home equity loan where you take out a lump sum at a fixed rate, but is a line of credit usually at a variable rate. I think of it as a credit card that is secured by my house (!). I don’t plan on actually using it, but I think it might nice to have around as long as the upfront costs to me are minimal. Here’s why:

Safety Net / Emergency Funds
Although having adequate emergency funds in cash is always preferable, it is nice to know that you have a HELOC as a backup in case of prolonged job loss or health problems. It’s always better to line up credit ahead of time while you have good credit rather than when you are already desperate. Using a HELOC can be preferable over paying sky-high credit card interest or falling behind bills (late fees, damaged credit score). Ironically, you might even use it to temporarily keep current on your mortgage to avoid penalties or even foreclosure. Let’s hope not.

Cheap and Flexible
The nice thing about a HELOC with no fees is that if you don’t take any money out, you don’t pay anything. And because the money is secured by your home, this assurance makes your interest rate relatively low. The rate is usually close to the WSJ Prime rate, which is currently 6% APR. On top of that, your interest paid might even be tax-deductible.

The interest is accrued daily, which makes it good for quick loans. So if you do need to take out $10,000 on short notice and you don’t have the cash on hand, using a HELOC might be the most economical way to do it. At 6%, your interest owed on $10,000 is only $1.64 a a day. Of course, for many folks this convenience might just provide too much temptation. All debt can turn into a double-edged sword. Know thyself, is all I can say.

Tool for Credit Card Profit Games
Here’s a trick to go along with making money with 0% balance transfers that is a good example of that flexibility. With certain credit card issuers it can be difficult to turn your balance transfer into cash in your pocket, especially when you have no existing balances. But here’s an example of how to use your HELOC to extract $10,000:

  1. Request a balance transfer from your 0% APR credit card for $10,000 directly to your HELOC. Since this is loan they won’t mind at all.
  2. Shortly before the balance transfer is scheduled to arrive, write a check for $10,000 from the HELOC to your interest-bearing bank account. Now you have created a temporary $10,000 debt at 6% and $10,000 bank balance earning ~4% (minus some possible lost days of interest).
  3. When the balance transfer payment arrives a fews days to a week later, your HELOC debt will be paid off.
  4. A week’s worth of interest at 6% APR ion $10,000 is only $11.50. And that is partially countered by interest earned in your savings account.
  5. Voila! For around ten bucks, you now have $10,000 at 0% APR in your bank account to do as you wish. 😉

Finding a HELOC – What To Look Out For
Now, I don’t want a home equity line if it’s going to cost me a bundle. Here’s a quick rundown of important factors when looking for a HELOC, based on an article by the Mortgage Professor.

  • Introductory rate and period. Temporary teaser rate to suck you in.
  • Margin. This is usually how your non-teaser interest rate is determined, relative to the Prime rate.
  • Minimum draw. How long can you take money out?
  • Required average balance. Do you have to take some money out?
  • Upfront lender fees. These days, you should be able to eliminate these.
  • Upfront third party fees. Harder to get waived, but try.
  • Annual fee. Just say no, again. Sometimes only waived for first year.
  • Cancellation fee. Many have these, I guess so you don’t bail and go to another bank. This is especially the case if they waive all the upfront costs above, since they are losing money on you so far. As long as you can keep your balance at $0 with no fees, just keep it open and don’t use it.

I see a lot of competition out there now that rates are low, so definitely shop around. As a data point, I just saw a special offer from Bank of America for a no closing cost, no application fee, no annual fee HELOC. Don’t forget to try your local credit unions as well.