 Fidelity just announced a new feature called Fidelity Solo FidFolios. You can make a custom index with up to 50 individual stocks, or a custom asset allocation portfolio using ETFs. You can then buy into your custom portfolio all a once using flat dollar amounts and Fidelity will juggle the fractional shares. For example, your $50 purchase could be split into 50 different individual companies.

“Now more than ever, investors want the peace of mind of trading, monitoring, and rebalancing custom stock portfolios in a simple way,” said Robert Mascialino, head of Fidelity’s retail brokerage business. “With the ability to align to a specific theme or individual values, Fidelity Solo FidFoliosSM helps leverage the power of direct indexing to build a customized portfolio while simplifying how investors manage what they own.”
Costs. Flat $4.99 per month, with a 90-day free trial. No stock commissions. Works within your usual Fidelity brokerage or IRA account. If you stop paying the fee, you just end up holding those individuals stocks and/or ETFs.
Note that this is different from their Fidelity Managed FidFolios, which is professionally managed by Fidelity and more about using tax-loss harvesting to gain a slight after-tax advantage. The cost for Managed Fidfolios is 0.40% annual management fee with a $5,000 initial minimum.
This may sound familiar, as it is pretty much what the start-up M1 Finance first introduced years ago, with the important distinction that M1 Finance is free (so far). Motif Investing also ran something similar before they shut down and their technology was acquired by Schwab.
I believe that a “custom robo-advisor” feature is going to be widespread in the future. Many DIY folks would like the ability to make your own customized all-in-one Target Retirement Fund. It’s really not that technically difficult to allow everyone to create their own custom glide path. I explored this with a small investment in M1, but in practice I have found it trickier to implement if you have to rebalance across various 401k plans, IRAs, and taxable brokerage accounts. Still, I’d rather use M1 Finance or this Solo Fidfolio over another robo-advisor that changes their model portfolios every few years to match up with whatever is currently trendy.


 Inside various financial forums, I am seeing the “anyone else worried?” 😓 posts as most portfolios are down double-digits. For a retiree with a $1 million portfolio, seeing $100,000 or $200,000 of value evaporate is understandably stressful. However, much of this is because you are comparing to your portfolio’s all-time high, or high-water mark, which is a relatively arbitrary number. Just because at one moment in time, there were a few willing buyers of your assets for a given price doesn’t mean you should anchor yourself to that number.




 Inflation (and thus I Bonds) 🚀🚀🚀! Savings I Bonds are a unique, low-risk investment backed by the US Treasury that pay out a variable interest rate linked to inflation. With a holding period from 12 months to 30 years, you could own them as an alternative to bank certificates of deposit (they are liquid after 12 months) or bonds in your portfolio.


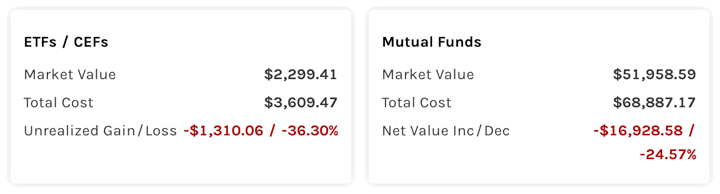
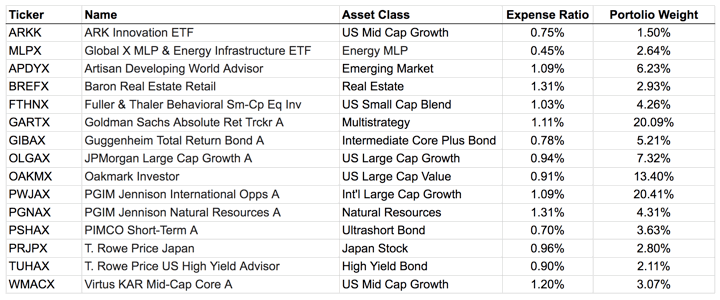
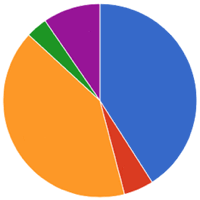 Here’s my quarterly update on my current investment holdings as of 4/8/22, including our 401k/403b/IRAs and taxable brokerage accounts but excluding a side portfolio of self-directed investments. Following the concept of
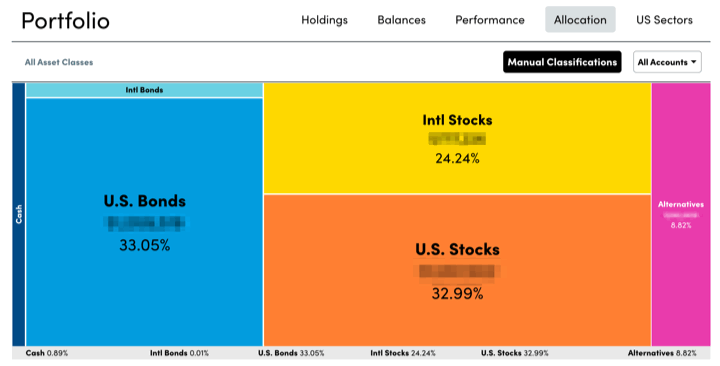
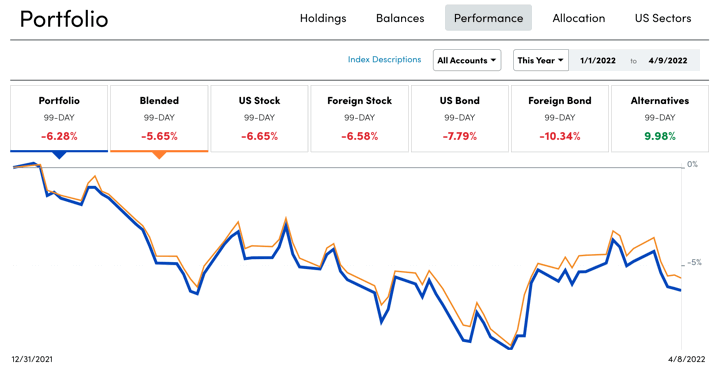
 The official IRA contribution deadline for Tax Year 2021 is April 15th, 2022. However, I choose to use April 15th as the informal deadline for my same-year IRA contributions (Tax Year 2022). By around April 1st, I have usually finished filing my income taxes and thus have handled any expected tax bills. I also have the first quarter of dividends arrive in my brokerage accounts, so I also have funds ready to re-invest. The optimal time would actually be make my contributions on January 1st, but sometimes we just have to settle for “good enough”.


 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)