 Like many others, I had a vague goal of $1 million net worth in my 20s. It’s easy to find a theoretical path a million. For example, $750 per month earning 8% returns for 30 years with get you there. Doing the actual earning, saving and investing is the hard part. It gets even harder during a bear market when your money feels like it is burning up in flames.
On the list of “Things I Would Tell My Younger Self”, I would include “Be patient and keep saving. You’ll get there.” Or by changing up the phrase “Always Be Closing” popularized in Glengarry Glen Ross – “Always Be Contributing” (ABC). One of the major benefits of writing this blog was keeping my focus on this path.
This is how a real couple could have gone from zero to $1 million from 2004 to 2017. My spouse and I both had our first full year of full-time jobs in 2004. From 2004 to 2017, we contributed the maximum allowable limit to both of our 401k and IRAs each year. The contribution limits rose gradually over the years. (Company match is not included here.) We invested our money in low-cost index Vanguard funds – mostly stocks with a little bonds – which can be closely approximated by the Vanguard Target Retirement 2045 fund (ticker VTIVX). This fund had its share of ups and downs with the market. It crashed a lot in 2008 and 2009. It went back up a lot afterward. We just kept contributing and buying each year.
Using Morningstar tools, I found the final amount today if the limit was invested on January 1st of each year. For example, if both of us invested $16,000 in Vanguard Target Retirement 2045 at the beginning of 2004 ($13k + $3k), that investment would now be worth $104,144 as of June 30, 2018. And so on for each subsequent year. As you can see, if you add all the years up, you would reach over $500,000 for an individual and over $1,000,000 for a couple:
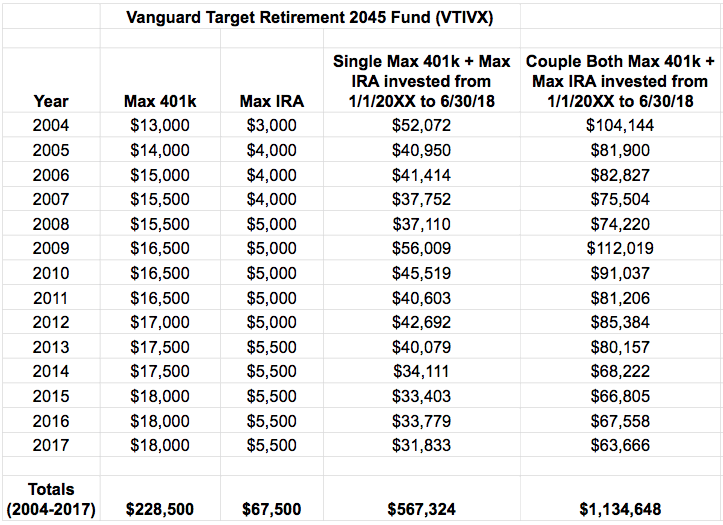
These numbers won’t be the same across other time periods, but they do represent a real-world experience. I’ve done a variation of this before in What If You Invested $10,000 Every Year For the Last 10 Years? 2008-2017 Edition.
According to Vanguard, 13% of their plan participants maxed out their 401k plans in 2017. 58% of participants had their entire account balance invested in a single target-date fund or similar managed allocation.
Bottom line. A real couple that started saving as 26-year-olds in 2004 and maxing out both their 401k and IRA plans each year could have reached $1 million by age 40 in 2018. All with a simple Vanguard Target Retirement index fund. This requires a lot of steady saving, but the important part is that it required no special investment skill. You didn’t need to recognize bubbles. You didn’t need to time bottoms. You didn’t need a fancy asset allocation, estimate future cashflows, understand price/book ratios, or even rebalance. Always be contributing.
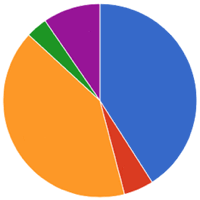


 Vanguard recently released How America Saves 2018 report [PDF], which looks at the nearly 5 million 401k, 403b, and other defined-contribution retirement plans that they service. If you are curious about how your 401k stats compare with others, there is a great deal of information in this report. Here are a few quick stats based on 2017 data:
 T. Rowe Price has a brochure The Benefit of Saving Regularly For Retirement [pdf] which has the common advice that you target saving at least 15% of your gross income each year to prepare for retirement. Of course, the earlier you start, the better. The added wrinkle here is that they offer an alternative route if you find 15% a stretch when you are young.

 Every time a large corporation stumbles, you will see something along these lines:
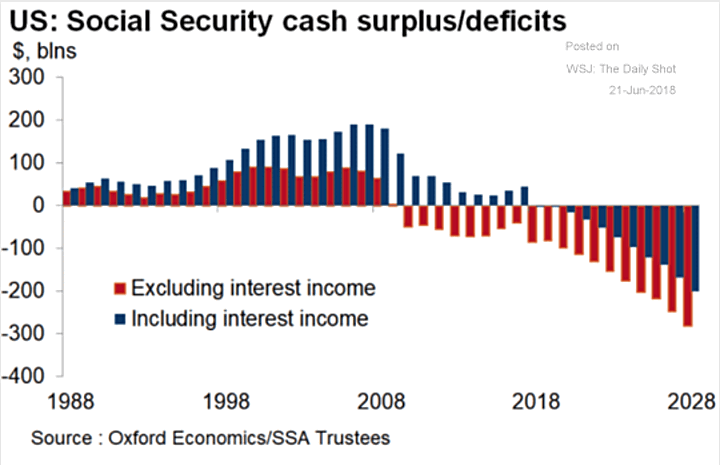
 You may have read recently that the Social Security Trust Fund is starting to shrink, and that it is projected to run out of money in 16 years. (Medicare’s trust fund is projected to run out in 8.) This is not the same thing as Social Security itself running out of money, as most Social Security payments to retirees come from the payroll taxes paid by current workers. As the

 If you have researched retirement at all (early or otherwise), you’ve probably ran across various retirement calculators online. You input how much money you have (or plan to have), your asset allocation, and it spits out some numbers. This


 Should a person who retires at age 70 withdraw the same amount of money from their portfolio as someone who is age 40? You’re talking about a retirement period that is likely twice as long as the other. In an article titled
 When it comes to making your portfolio last a lifetime, you may be surprised at how long that might be. According to this Vanguard longevity tool, for a couple both age 40 today, there is a 50% chance that one will live to 88. That’s 48 years.


 I’m turning 40 years old this summer. This number has always been a psychological marker for me. I’ve always wanted to be financially secure and have started a family by age 40. According to this
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)