While I often talk about your savings rate as an important metric for reaching financial freedom, I also follow that up by talking about managing both parts of that formula: earning more and/or spending less. Focusing your energy on a specific task is often better that trying to do everything perfectly and getting frustrated when you can’t juggle all the balls at once.
Financial planning expert Michael Kitces has come up with a helpful framework called The Four Phases Of Saving And Investing For Retirement that is related and also takes into consideration your portfolio size. This graphic he created explains it well:

Here are my own notes and paraphrasing (please read original post for his own words):
- Earn. First, you need income. Focus on your human capital to help you earn more. Invest energy into your education, career skills, and network (surround yourself with good people). If it fits your personality, take a risk and start a business.
- Save. Once you have significant income, be sure to save a big portion of it. Create systems and habits to help keep your spending modest. A 30% or 50% savings rate for above-average earners is not out of the question.
- Grow. Once you have significant savings, spend some time developing a set of solid investment beliefs and a written plan. Devote time specifically to learning about investing and/or find and hire a trusted advisor. Your money should always be making more money.
- Preserve. You should only need to get rich once. Do you have proper insurance in place? Create a long-term plan to preserve and ultimately live off the income from your investment portfolio and other assets.
You can pay attention to the other areas, but I like this lifecycle method of prioritizing your finite time and energy.


 In a Quora question



 I like the idea of living off dividend and interest income. Who doesn’t? The problem is that you can’t just buy stocks with the absolute highest dividend yields and junk bonds with the highest interest rates without giving up something in return. There are many bad investments lurking out there for desperate retirees looking only at income. My goal is to generate reliable portfolio income by not reaching too far for yield.
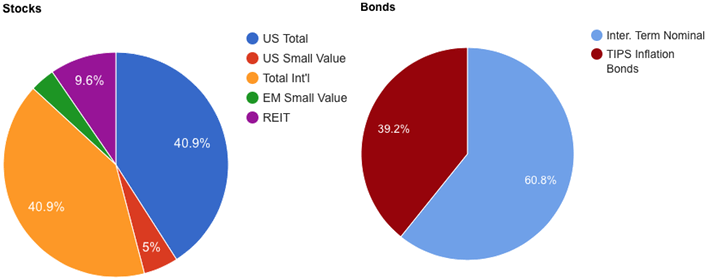
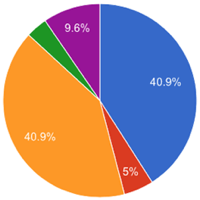 It has been a while, so here is a 2016 First Quarter update on my investment portfolio holdings. This includes tax-deferred accounts like 401ks, IRAs, and taxable brokerage holdings, but excludes things like our primary home and cash reserves (emergency fund). The purpose of this portfolio is to create enough income to cover household expenses.



 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)