I know there is plenty of bad advice out there, but this one just caused me physical pain. Mr. Cliff Mason impressively gained the status of Staff Reporter at TheStreet.com fresh out of college (did I mention his uncle is Jim “Mad Money” Cramer?). He hits the ground running with his recent article Young Ones, Go Forth and Speculate, where he bashes veteran Wall Street Journal reporter Jonathan Clements and proceeds to share some of his vast financial knowledge with us.
Pearl of Wisdom #1:
I believe that saving money is at best nonessential for the under-30 cohort, and that people my age will generally get more from spending their money than from buying stocks or bonds.
Pearl of Wisdom #2:
Buy small-cap stocks that trade under $10, have little analyst coverage and a reason to go higher. In a word: Speculate. […] With maybe $2,000 to invest a year, you won’t make serious money in the market unless you take enormous risks. It’s much more likely that you’ll get wiped out, but since you won’t have a lot of money on the line, it’s a worthwhile risk.
Wait, there’s more! You must see Mr. Mason in person in this TheStreet.com video showing off his brand new iPhone. Why did he buy this phone? “Well, I wasn’t doing anything… and I had money to burn… it is a babe magnet…” What about his current plan? “I have an old Verizon line that my dad still pays for [the iPhone is AT&T-only] … I should tell him about that…”
Hmm… sure sounds like someone I should listen to for financial advice!
I found this article via the Diehards Forum, where author Taylor Larimore submits his succinct reply:
If a young investor age 25 invests $4,000/year @ 10%, at age 65 he/she will have $1,947,407.
If a gambler waits until age 35 (and loses), he/she will have $733,774–less than half.
Investing for retirement should not be a gamble.
My response? As a 20-something who tries hard every day to balance enjoying life now, buying a house, and funding my own retirement someday, I’m a bit offended by his flippant views on saving.
I don’t really care what Mr. Mason does with his money. But to tell others to just gamble it away because it’s “not that much”? Being 25 and actually having $2,000 saved up is not something to be dismissed. Not only can you take advantage of the wonder of compound interest, but look at how risk decreases as your time horizon increases when properly diversified. Why increase your risk needlessly when you could be decreasing it?
Okay, maybe I’m being too harsh. When you’re young, you should take risks. Go into debt to pay for college or graduate school, work at a start-up company or at a non-profit that you love, or even start your own business. Take chances with money that can really reap huge rewards!
 It’s time to examine my mom’s 401(k) plan. The first thing that I wanted to do was to get an idea of what kind of fees she was paying. There are three basic types of fees, according to the Dept. of Labor:
 Let’s continue with the 401k/403b Rollover discussion. Previously, I explored some
 While visiting the parents, I was also asked to provide some input on their retirement savings. I don’t want to invade their privacy, but I’m sure they share common concerns with others out there. My father, who is in the non-profit/education sector, has much of his retirement money with
 While reading this month’s issue of Kiplinger’s Personal Finance magazine, I found that UC Irvine offers a free online course on the Fundamentals of Personal Financial Planning:
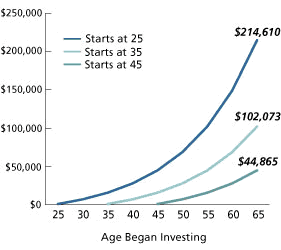 and one at age 45, investing a total of $20,000. Each earns 7 percent per year and, for purposes of this illustration, the effects of taxes and inflation are ignored.
 Vanguard has just announced some
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)