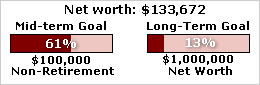
It’s time for another bi-monthly update on my investment portfolio.
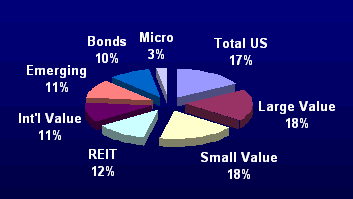
| Retirement Portfolio | ||
| Fund | $ | % |
| FSTMX – Fidelity Total Stock Market Index Fund | $12,599 | 17% |
| VIVAX – Vanguard [Large-Cap] Value Index | $14,082 | 18% |
| VISVX – V. Small-Cap Value Index | $14,146 | 18% |
| VGSIX – V. REIT Index | $9,229 | 12% |
| VTRIX – V. International Value | $8,294 | 11% |
| VEIEX – V. Emerging Markets Stock Index | $8,040 | 11% |
| VFICX – V. Int-Term Investment-Grade Bond | $7,726 | 10% |
| BRSIX – Bridgeway Ultra-Small Market | $2,086 | 3% |
| Cash | none | – |
| Total | $76,202 |
| Fund Transactions Since Last Update |
| Bought $1,500 of FSTMX on 4/5/07 (36.773 shares) |
Thoughts
Not much going on, I have been contributing a $500 a month to my Solo 401k while trying to build up my cash hoard for a house downpayment. I still plan on tweaking my asset allocation, but I’ve just been distracted by other things and kind of want to wait a full year before making any changes.
All of our Vanguard funds are held at Vanguard.com, where there are no commissions for trading their mutual funds. Currently, everything there is in Roth IRAs, one each for my wife and I. Even though Roth IRAs rock, we haven’t contributed to one this year yet because we might be over the income limits for 2007.
The Fidelity fund is also held in-house at Fidelity, where I have my Self-Employed 401k. Funds are also no transaction fee (NTF) there. It’s a bit annoying that both their Spartan Total US and International funds have high $10,000 minimums, but the 0.10% expense ratio is nice. I could also trade ETFs, but at $20 a trade it’s a bit expensive.
You can see some older posts on how this portfolio came to be here, as well as my previous portfolio snapshots here.
 I’ve been trying recently to try and make some minor adjustments to the target asset allocations of my portfolio. I want to create something that I won’t be tempted to change again for many years. While attempting this, I keep noticing how hard it is for a beginning investor to try and figure out where to put their hard-earned money. So many websites, books, magazines, television shows… and the amount of information being thrown at you just seems to multiply daily. Everybody has an opinion, including me. Am I right?
 One
 I’ve always thought of 403(b)s as identical to 401(k)s, just for non-profit and educational institutions. But upon discussing this with a teacher, I found out that they can have their own unique problems: primarily high-priced annuities. Did you know that 80% of 403(b) funds are currently invested in fixed or variable annuities? This is really surprising, considering that annuities are usually only a good idea for high-income people who’ve already maxed out all their other tax-deferred options – why put a tax-deferred product inside another tax-deferred product?
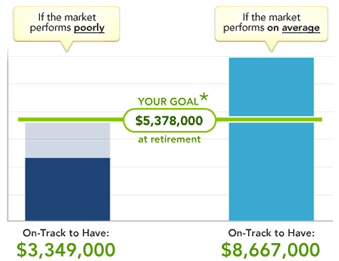
 Fidelity has a new tool called the
 The Best Credit Card Bonus Offers – 2026
 Big List of Free Stocks from Brokerage Apps
 Best Interest Rates on Cash - 2026
 Free Credit Scores x 3 + Free Credit Monitoring
 Best No Fee 0% APR Balance Transfer Offers
 Little-Known Cellular Data Plans That Can Save Big Money
 How To Haggle Your Cable or Direct TV Bill
 Big List of Free Consumer Data Reports (Credit, Rent, Work)